


Private Debt Intelligence – 3/19/2018

UK-Based Private Debt Fundraising: An Overview
Chart
Download Data
[wpdm_package id=’17206′]
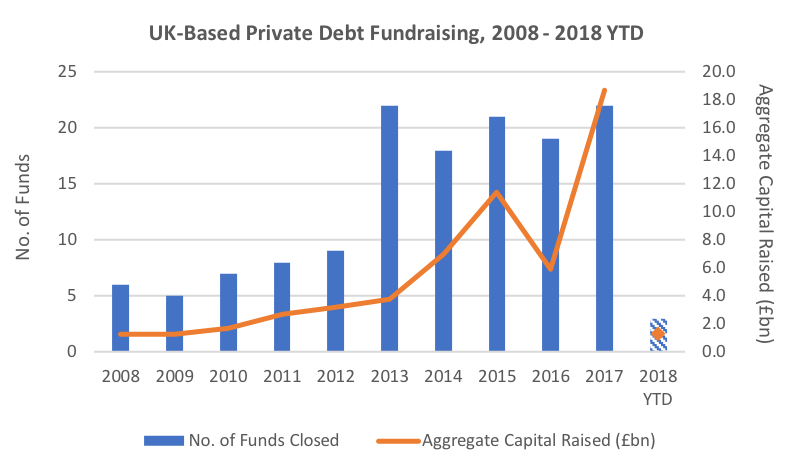
The UK-based private debt fundraising market witnessed a record 2017, with 22 funds securing a total of $19bn in capital, exceeding the previous record of $11bn raised by 21 funds in 2015. 2017 also marked a sharp uptick from the previous year: in 2016, 19 UK-based private debt funds raised just $5.9bn.
The largest UK-based private debt fund manager by total capital raised in the last 10 years is Intermediate Capital Group. The fund manager has an estimated £7.3bn in dry powder and has raised over £16bn over the last 10 years. The firm also raised the largest UK-based private debt fund to close in 2017: the direct lending vehicle Senior Debt Partners III secured a total of €5.2bn (£4.6bn).
In 2018 so far, three UK-based private debt funds have held a final close and have secured £1.3bn. The largest fund to have closed is the distressed debt Alchemy Special Opportunities Fund IV which closed on £900mn. Alchemy Partners is the eighth-largest UK-based private debt fund manager by total capital raised in the last 10 years, having raised £2.2bn.
As of February 2018, there are 43 UK-based private debt funds in market with an aggregate target of £18bn. Direct lending vehicles make up the largest portion of UK-based private debt funds in market: there are 25 direct lending vehicles looking to raise a total of £13bn. Special situations funds also make up a significant number of funds in market with 10 funds seeking £3.2bn. Additionally, there are four distressed debt funds targeting £1.8bn, two mezzanine funds with an aggregate target of £0.2bn and two venture debt vehicles seeking £0.1bn. The largest of these funds in market is the Intermediate Capital Group’s mezzanine vehicle ICG Europe Fund VII which is seeking €4.0bn (£3.5bn) in capital commitments.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
