


Private Debt Intelligence – 4/2/2018

Credit Strategies Start 2018 with Positive Performance
Chart
Download Data
[wpdm_package id=’17469′]
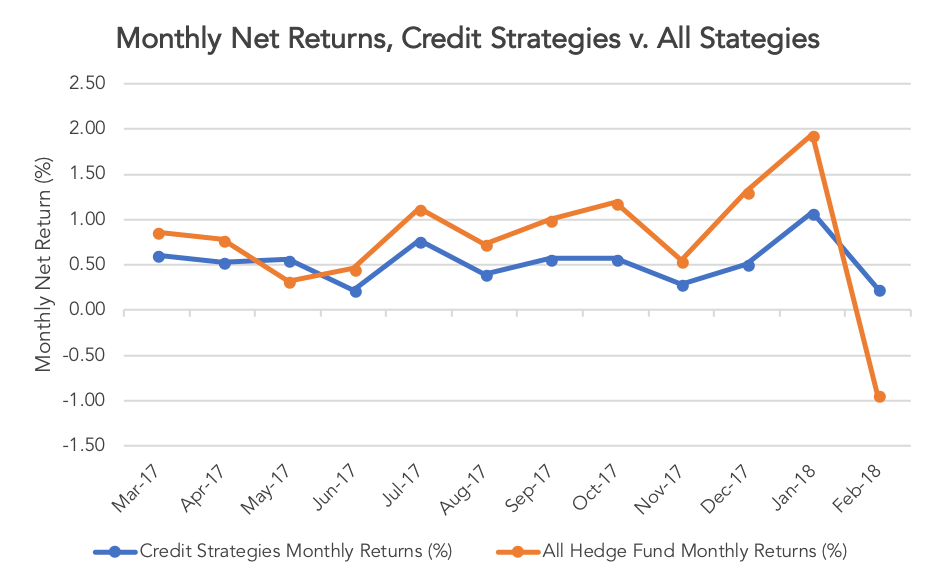
Preqin finds that credit strategy hedge funds have maintained their streak of positive performance, having generated positive returns on a yearly basis since 2009, and seeing returns of 7.41% in 2017. The strategy has started 2018 with a bang, producing positive performance in the first two months of the year, outpacing the Preqin All-Strategies Hedge Fund benchmark in some regards.
Credit strategies generated returns of 6.53% in the 12 months leading up to February 2018, failing to outperform the 9.71% produced by the All-Strategies Hedge Fund benchmark over the same time period. The strategy also fell behind equity strategies (12.57%), multi-strategy funds (10.86%) and event driven strategies (8.45%). Credit strategies did, however, maintained stable levels for the majority of those 12 months, with monthly returns hovering around 0.5%, while the All-Strategies Hedge Fund benchmark fluctuated more violently.
Despite credit strategies producing lower returns than the Preqin All-Strategies Hedge Fund benchmark in the 12 months leading to February 2018, it was the only hedge fund strategy which generated positive returns in the month of February (0.24%). In 2018 year-to-date, credit strategies have generated 1.32% in returns – the highest of any major strategy for that time period after multi-strategy hedge funds which produced returns of 1.51%. Hedge funds overall saw February net returns slump to -0.93%, although 2018 YTD returns remain positive at 0.99%.
Looking ahead, investors are pleased with the returns generated by credit strategies: while 63% of investors surveyed in December 2017 plan to maintain their exposure to the strategy, 22% plan to increase their exposure in 2018. If credit strategies continue along this pace, the strategy will likely see a fantastic year.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
