


Private Debt Intelligence – 4/29/2019

Private Debt Keeps Performing Well
Chart
Download Data
[wpdm_package id=’24846′]
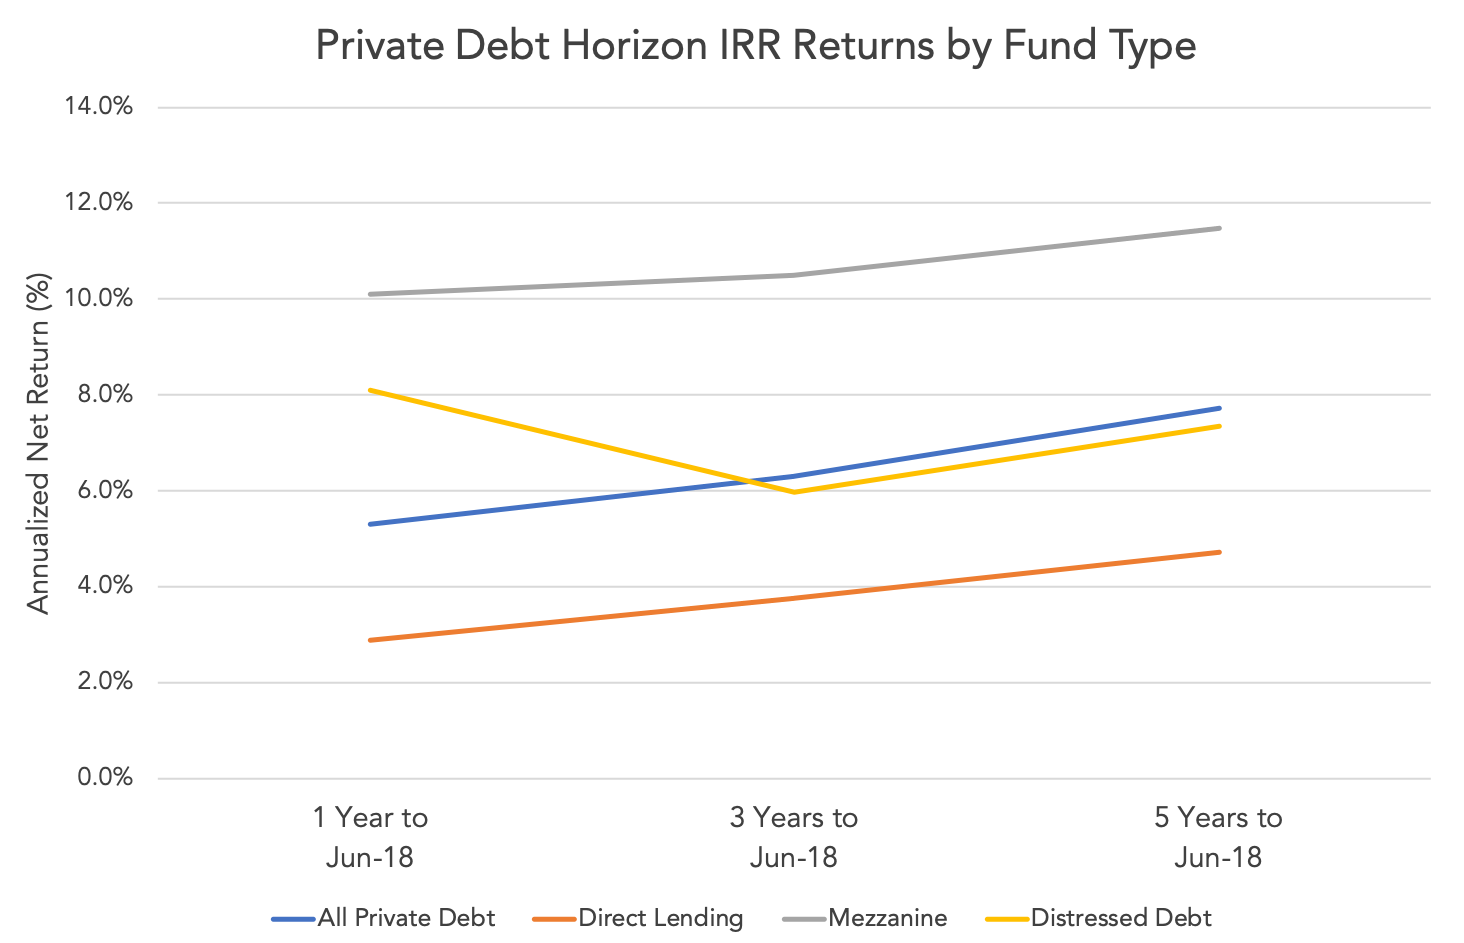
Over the one-, three- and five-year periods to June 2018, mezzanine funds have outperformed all other private debt strategies, generating an annualized return of 11.5% over five years. In contrast, direct lending funds have produced the lowest returns over these timeframes, generating just 4.7% over five years, while distressed debt funds have returned 7.4%.
Private debt funds invested in the years following the Global Financial Crisis have performed well, with the top quartile boundary for 2009 vintage funds peaking at 21.7%. Vintage 2000 funds generated the highest median net IRR at 15.4%, while the lowest median net IRR (7.4%) was recorded in vintage 2005 funds. The most recent vintage 2016 funds display a median net IRR of 9.9%.
Vintage 2001 private debt funds have generated a median distributed to paid-in capital ratio of 158%, demonstrating the high returns received by investors.
As of March 2019, private debt dry powder stands at $286bn, 40% ($115bn) of which is held in direct lending funds. Distressed debt funds currently hold $72bn, followed by mezzanine funds, which hold $59bn. Private debt dry powder has smoothly been increasing, except for 2014, where a decline of $16bn was registered. After this, direct lending dry powder boosted, and since 2017 it makes up the largest percentage of private debt dry powder. With no change, venture debt and special situations continue to make up the smallest portion of overall dry powder.
Comparing targeted markets, North America-focused private debt funds have $174bn of capital available to invest, while vehicles focused on Europe have $91bn.
Contact: William Clarke
william.clarke@preqin.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.