


Private Debt Intelligence – 4/9/2018

Private Debt: Slowdown in Q1 2018
Chart
Download Data
[wpdm_package id=’17564′]
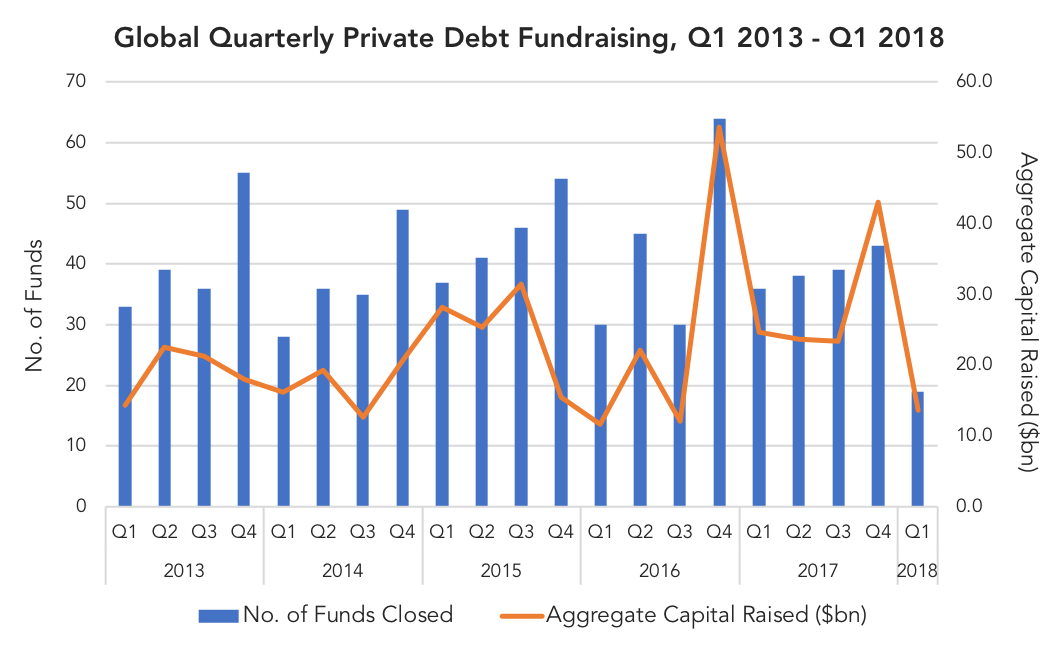
The private debt industry had a banner year in 2017 in which 156 funds held a final close securing a record $115bn. This marked a significant increase from the previous record in 2015 when 178 funds raised a little over $100bn in capital. 2017 was also the only year in which private debt funds raised over $20bn in each quarter.
The first quarter of 2018 has not seen the same fundraising levels of 2017. In Q1 2018, just 19 funds held a final close, the smallest numbers of funds to reach a final close in a quarter over the last five years. The quarter also saw a slowdown in capital secured: a little under $14bn was raised, a drop from the $43 secured in the previous quarter, as well as a drop from Q1 2017 when 36 funds raised a total of $25bn.
Despite the slowdown from the frenetic pace of 2017 fundraising, fund managers have no immediate need to panic; the industry may be pausing before a new fundraising cycle. The majority (51%) of investors surveyed by Preqin in December 2017 have a positive perception of the industry and 42% of investors plan to allocate more capital to private debt funds in 2018. Dry powder also remains high, standing at $235bn as of the end of March, and investors may be waiting for firms to begin putting capital to works before making further commitments. Additionally, out of the 348 funds in market (as at 3rd April 2018), 158 vehicles have already held an interim close, securing a total of $27bn. Although the first quarter of 2018 saw a fundraising slump, the year could very well see a bounce back in fundraising levels.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
