


Private Debt Intelligence – 4/17/2017

Private Debt Fundraising in Q1 2017 by Fund Type
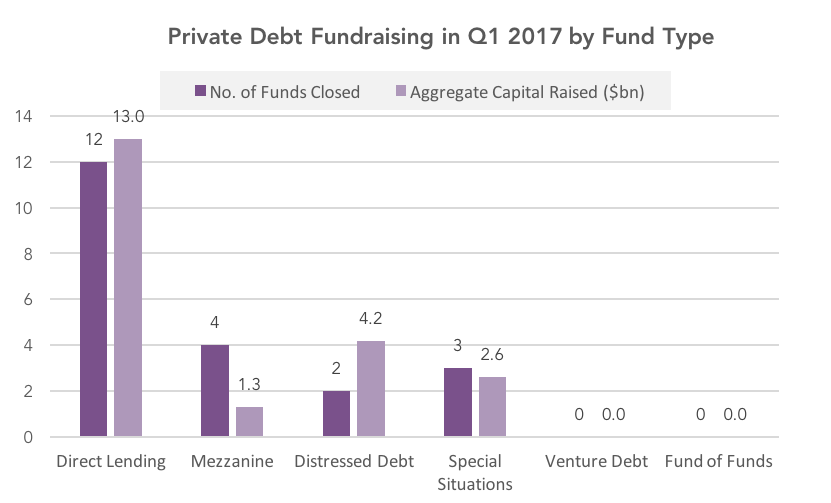
The private debt industry recorded a strong start to 2017, as 21 vehicles reached a final close attracting $21bn in investor capital, despite marking a downturn from the record $50bn raised in Q4 2016. However not all strategies were able to capitalise on healthy investor appetite and attract high levels of commitments.
Direct lending funds in particular drove fundraising, securing their highest quarterly total of all time. Twelve funds raised a combined $13bn of capital commitments, exceeding the previous high of $12bn in Q3 2015. The largest private debt vehicles to reach a final close through the quarter both operated direct lending strategies, and raised an aggregate $6.8bn between them.
Just two distressed debt vehicles closed in the quarter however they raised a combined $4.2bn with Carlyle Strategic Partners IV and ($2.5bn) and Varde Fund XII ($1.7bn) both securing substantial levels of capital. Three special situations funds reached a final close securing $2.6bn of investor capital, their highest quarterly fundraising total since Q3 2015 ($3.3bn), and the best start to a year since Q1 2012 ($5.7bn).
All other private debt strategies suffered lacklustre fundraising. No venture debt or private debt fund of funds reached a final close, the first time this had happened since Q1 2016 for both types, although the niche strategies within the private debt industry often see inconsistent fundraising trends on a quarterly basis.
Mezzanine funds enjoyed an unprecedented end to 2016 when 15 funds secured $23bn of investor commitments in Q4. As such, it was no surprise to see a marked decline in fundraising with four vehicles closing through the opening quarter of 2017 raising $1.2bn, the same level of capital as was raised in Q1 2016.
The fundraising momentum generated by a record Q4 2016 has not dissipated in Q1 2017, however direct lending funds have secured the vast majority of commitments. Looking ahead, the fundraising pipeline looks strong across all strategies, but direct lending funds are likely to continue to attract the bulk of investor capital.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
