


Private Debt Intelligence – 5/1/2017

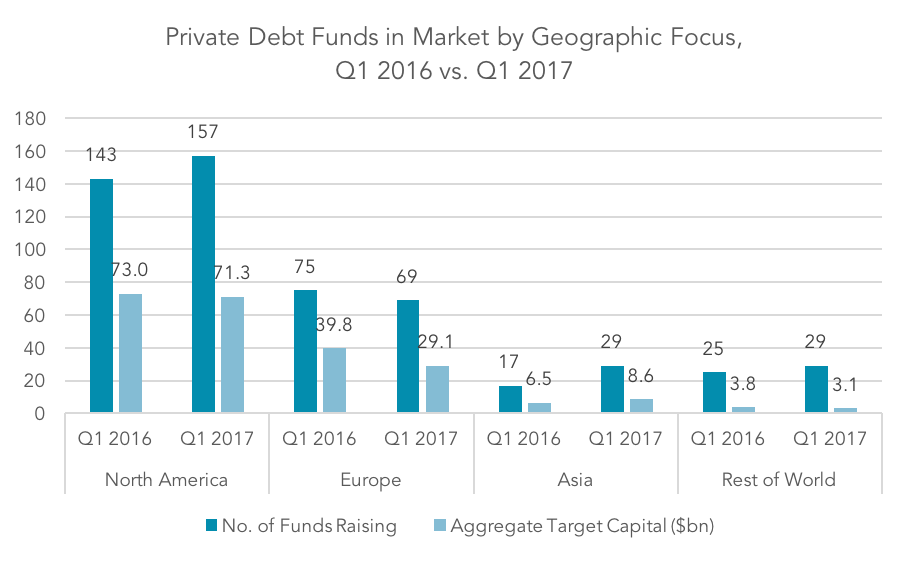
Private Debt Funds in Market by Geography
[wpdm_package id=’12214′]
As at the start of Q2 2017, there were 284 private debt funds in market seeking an aggregate $112bn of investor capital. These figures were roughly the same as they were a year previous, when 260 funds were targeting $123bn globally.
Europe was the only region which recorded a decrease in the number of funds on the road over the course of the year, falling from 75 to 69 private debt vehicles marketing themselves to investors between the start of Q2 2016 and Q2 2017. The aggregate capital targeted for investment in the region has also fallen by over $10bn, decreasing from $40bn to $29bn following a number of large final closes towards the end of 2016.
The number of funds targeting North America has increased as the region continues to develop as the pre-eminent location of the private debt industry. As of the start of Q2 2017, there are 157 vehicles on the road, an increase from 143 at the same point in 2016, however the total commitments sought for the region by private debt fund managers has seen a slight downtick, with $71bn now being targeted.
The private debt industry is beginning to mature in Asia and so it is unsurprising that the region has seen the number of vehicles targeting investor capital grow by 71%, from 17 at the start of Q2 2016 to 29 a year later. The aggregate target capital has also risen by nearly a third (32%), with $8.6bn now being sought by firms for investment in the region. Elsewhere, 29 funds are currently seeking $3.1bn as managers look for opportunities around the world that may offer better value for money amid an environment of high valuations.
Private debt funds are poised to post strong returns and despite an intensely competitive fundraising market, it would seem likely that more vehicles will continue to enter the fundraising pipeline. Investor appetite remains strong, and therefore fund managers will hope that capital will continue to be allocated to private debt vehicles and they can achieve a successful fundraising process.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
