


Private Debt Intelligence – 6/3/2019

Private Capital Subscription Credit Usage on the Rise
Chart
Download Data
[wpdm_package id=’25659′]
Very few developments in alternative assets have attracted such a mixed response as subscription credit facilities (also known as equity bridge facilities, subscription line facilities or capital call facilities). Although they are nothing new, there is a wide range of views between fund managers and investors – and even within each group. With labels ranging from ‘window dressing’ to ‘operational excellence,’ there is a clear disconnect between intention and perception across the board.
The advantages – cash flow management, increased liquidity, reduced administrative burden – are touted by many fund managers, and those investors that back their use. But there are also drawbacks. While subscription credit facilities historically have had short repayment periods, those periods have been getting longer in recent years, increasing the overall cost of the loan and leaving the fund in debt for longer. It can also affect IRR calculations, especially in the early life of a fund, making it more difficult for investors to compare their portfolios on an equal basis or to fairly evaluate a fund manager’s previous performance.
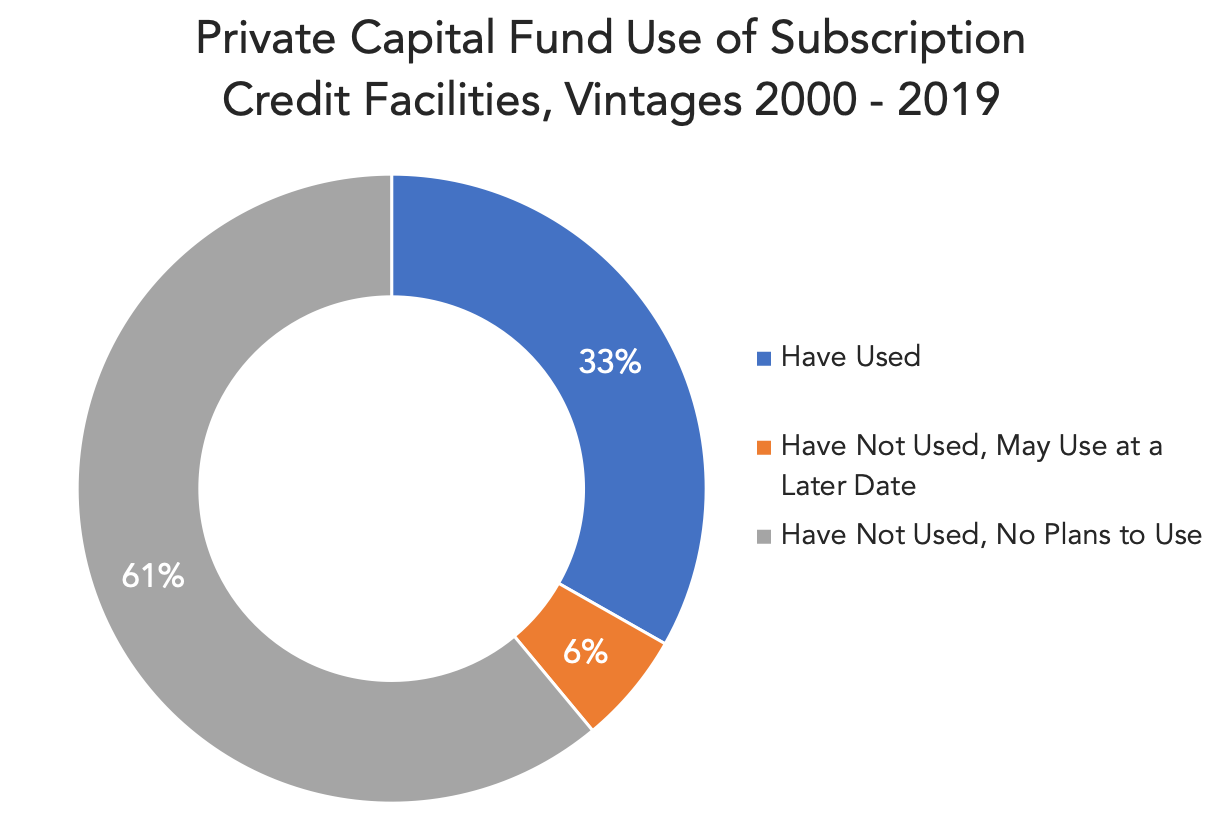
It is worth noting that subscription credit facility usage is lower than one might expect. A sample of nearly 3,000 private capital funds shows that only 33% have used a subscription credit facility, with a further 6% considering it in the future. But the proportion of funds using it in recent vintage years has been increasing. Just 26% of 2010 vintage private capital funds have used subscription credit facilities, but this has risen to 43% among 2017 vintage funds. This has been seen across almost all private capital asset classes.
Next week, we will look at some of the ways to account for the impact of subscription credit facilities, and ask what the future of these loans might be.
Contact: William Clarke
william.clarke@preqin.com



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…