Secondary Buyouts Still a Primary Route for PE Sellers
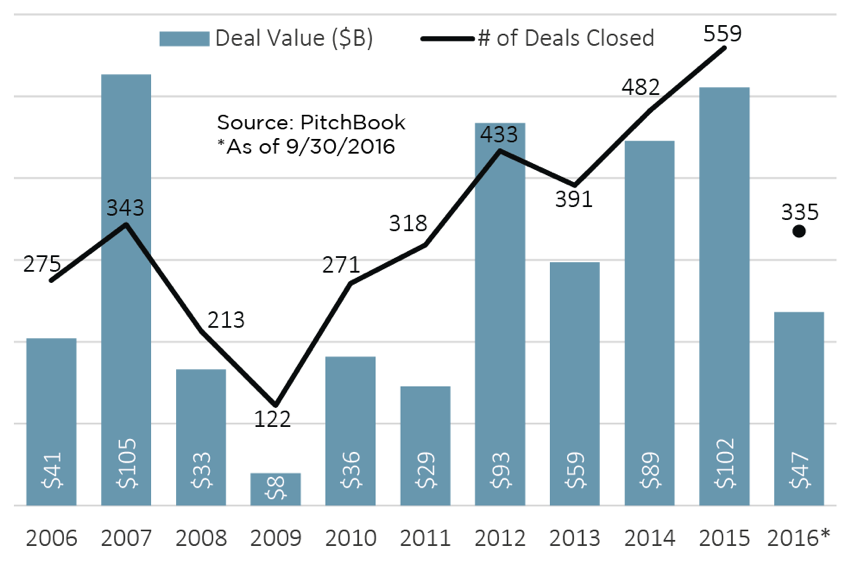
335 secondary buyouts have been closed through the end of September, putting the year on pace to fall short of 2014’s tally of 482 but still third-highest of the decade. Given the impact of outliers, this year’s total secondary buyout value may not impress as much as much as those of 2007 or 2015, but it is still quite considerable. In short, private equity sellers are still utilizing fellow sponsors as an exit route nearly as avidly as they were in the past two years, which only further underscores the ongoing debate as to whether they should be as frequent as they are. On the one hand, one could argue that limited partners may in some cases find themselves invested in both the selling and the buying funds, which could contribute to material impacts given fees and transaction costs. On top of that, concerns over just how much further value creation can occur after one round of PE backing persist.
The tropes around general partners being overly influenced by the incentive to burn capital near the end of a fund’s lifecycle are certainly factors in this discussion. However, there are arguments to be made that secondary buyouts do not necessarily impact LP returns that much. Some smaller PE funds may well be able to make some operational improvements at a certain scale, but then larger PE firms could take things to the next level, without incurring too much additional debt. Beyond that aspect of scale, complementary and/or niche skillsets come into play—generalist managers can add some kinds of value, other kinds take dedicated specialists. The crux of the matter really comes down to whether both PE sponsors’ skillsets are complementary and thus true value can be added to a degree sufficient to negate the impact of potentially paying fees twice over. Even if the likelihood of exposure to both PE funds may be fairly slim, such transactions are best dealt with by GPs by alerting their investors and laying out the rationales. The truth of the matter is that even if they are motivated to burn unspent dry powder, PE fund managers are not going to throw good money after bad since they wish for their current LPs to recommit. They are going to work just as hard to tune up a company acquired through a secondary buyout as they would in an original platform buyout (which frankly is harder and harder to find these days). So the risk proposition is mainly the same as in any other PE transaction, with only a few extra question marks such as a potential, slight hit to returns based on potentially longer hold periods and GPs’ willingness to generate a lower multiple as long as it still clears overall fund thresholds.



Latest news
Number of smaller funds dwindles
Analysis of fund-close data found that vehicles valued at under $250m have seen a rapid decline since 2024.While PEI Private…

US Private Credit Transparency Highlights Uneven BDC Performance
Credit performance across business development company (BDC) portfolios remains uneven, although reported losses and non-accruals were broadly stable quarter over quarter, according to Fitch Ratings’ Private Credit Transparency Monitor for 2Q26.