


Expect More of the Same in 2015
Final PE numbers for 2014 are in. U.S. deal flow nearly matched 2013 levels at 2,955 investments, but the bigger story was in total value, which grew to $523 billion over 2013’s $501 billion. And that was without the kinds of mega-deals like Dell ($24.9bn) and Heinz ($23bn) that typically inflate final numbers. The largest buyout that closed in 2014 was the $5.4bn Gates Global deal. Without much activity at the upper end of the market, it was the U.S. middle market that propped up 2014 value, which represents a new post-crisis record for capital invested.
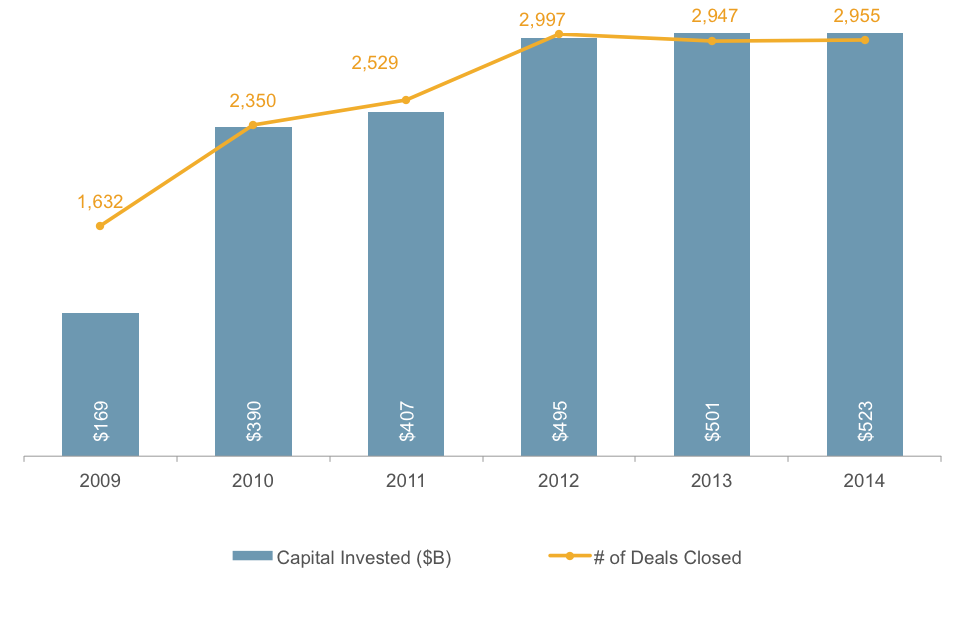
We expect to see similar numbers in 2015, if not higher. A handful of big buyouts are already set to close this year, including the $9.2bn Safeway buyout and $8.7bn Petsmart deal. Even if activity remains stagnant at the upper end, the middle market should remain buoyant. PE firms and lenders are migrating there for deal generation, and in some cases lenders were known to be the aggressors in pushing deals. PE firms raised over $400 billion in fresh dry powder over the last two years, and they’re motivated to put it to work. High valuations are bringing more companies to market as sellers take advantage of the conditions, which may mean another good year for secondary buyouts. And look for a healthy number of PE-led carve-outs in 2015 as strategics keep shedding non-core businesses.
Contact: Alex Lykken
alex.lykken@pitchbook.com




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.