


View PitchBook’s Research Note Here
Is private equity performance consistent? Managers will tell you yes – according to marketing materials, nearly every manager boasts of top quartile performance. Squishy numbers and contestable metrics have clouded the industry for years, and investors apparently fall for them every cycle.
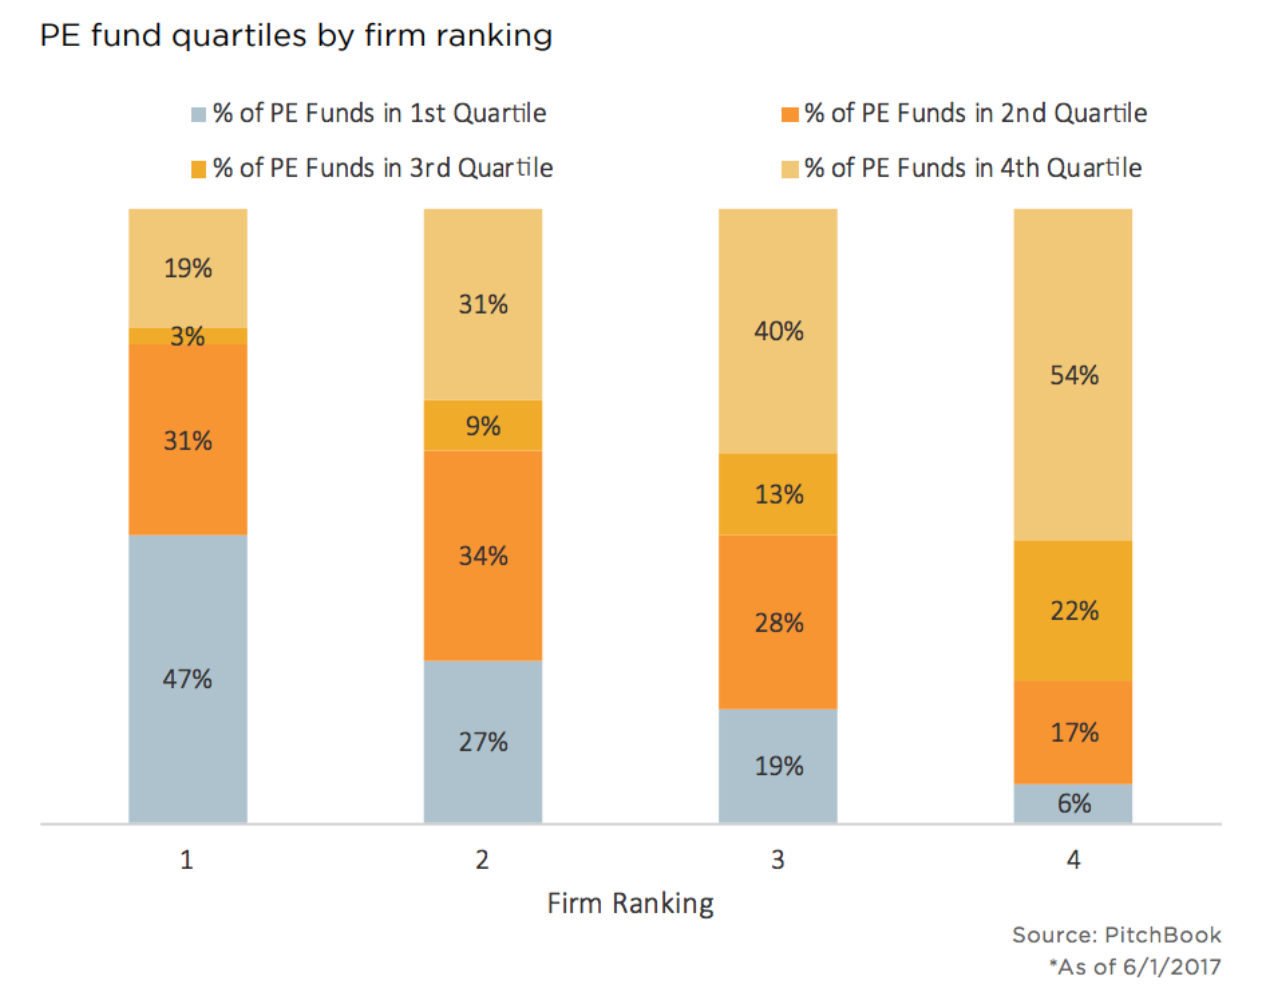
While PE fund performance obviously varies, PitchBook’s Analyst team wanted to see if the firms themselves performed consistently over time. After assigning quartiles to 1,300 individual funds across 310 PE firms, we averaged out and collated the fund quartiles (organized by vintage) into firm quartiles, graphed below. As we argue in a recent research note (linked here), there is a pronounced discrepancy between top-performing firms and bottom performers – for first- and fourth-quartile firms, roughly half of those funds were consistent with their firms’ rankings.
This isn’t news per se. Several academic studies also reach this conclusion, but often find top-quartile PE firm performance, net of fees, to be roughly equal to their public market equivalents. In other words, even the best GPs don’t outperform stocks and bonds when their PE funds are bundled together. Our research note found the opposite – top-performing firms outperformed the Russell 3000 at every horizon, but especially at the 10- and 15-year marks (1.35x and 1.42x, respectively). What’s more, even bottom-performing firms held their own, notching a 1.06x multiple against the PME at the 1- and 15-year horizons. That helps explain one head-scratching trend: 41% of consistently bottom-quartile firms manage to raise at least three follow-on funds, and another 9% raise five or more. We might joke about all the “top-quartile” teams running around asking for more money, but even the poor performers have a few numbers on their side.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
