


Reorg Credit Intelligence – 9/27/2021

Structure of Revlon’s BrandCo Loan May Advantage BrandCo 2L Recoveries
on RemainCo Collateral at the Expense of 2016 Term Lenders
Chart
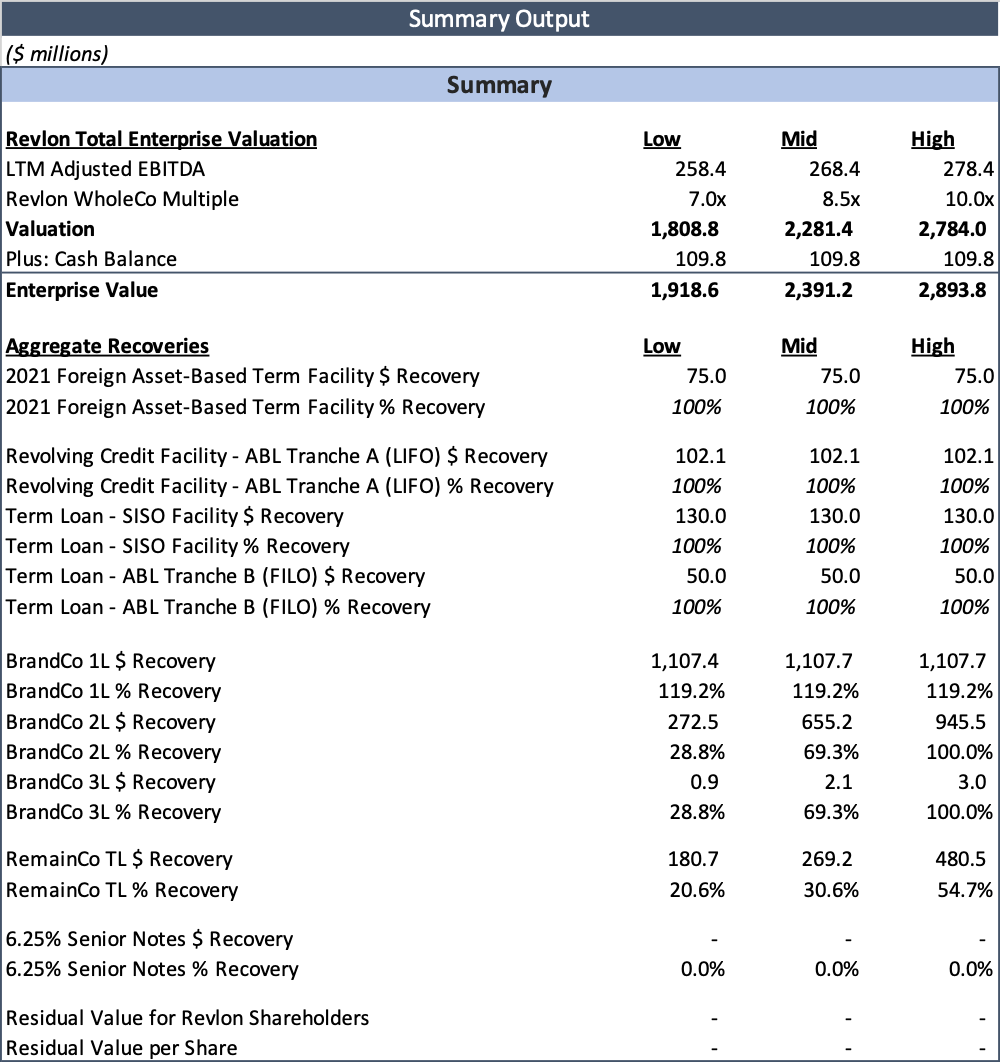
Numerous refinancing transactions in recent years, including Revlon’s success in addressing its 2021 unsecured note maturity last year with an out-of-court solution, leaves the company with an incredibly complex capital structure consisting of foreign term loans, a three-tiered ABL facility, a three-tiered “BrandCo” facility, a partially paid-down regular-way term loan and one unsecured note issuance. Click through for our Americas Core Credit experts analysis of the Revlon refinancing situation.
Contact: Matt Danese
mdanese@reorg.com




Latest news

LevFin Issuance Slows Across Products in August; DCM Remains a Bright Spot
The leveraged capital markets business continued to decelerate from just about every aspect, even for August standards. Overall issuance (including…
Fitch Ratings’ U.S. Private Credit Default Rate Rose to 6.3% in August 2026
Fitch Ratings recorded a U.S. Private Credit Default Rate (PCDR) of 6.3% for the trailing 12 months (TTM) ended August 2026, up from 6.1% in July 2026 and a record high.