



Download PitchBook’s Report here.
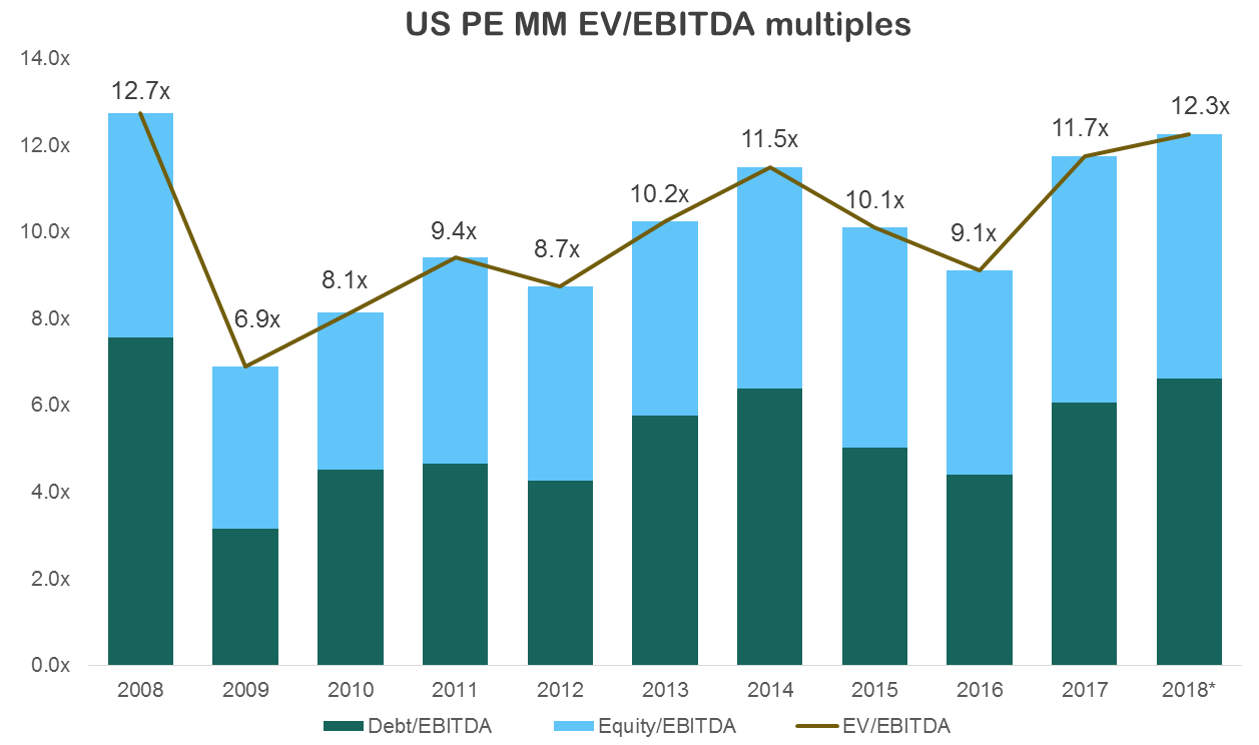
Middle-market purchase price multiples have nearly doubled since 2009. To be sure, most metrics and indicators have bounced back substantially from the crisis, and private equity is no exception. PE valuations have risen moderately from year to year, sometimes in fits and starts, and now stand close to where they were in the halcyon days of 2008. To call attention to pre-crisis similarities often implies a feeling of déjà vu, that another downturn is around the corner. For private equity, however, most crisis-era problems were concentrated at the highest end of the market, the multi-billion-dollar deals for companies that would eventually be caught flatfooted by energy prices or changing consumer behaviors or burdensome debt.
Investors are more modest today—at least they say they are—yet multiples have catapulted back to pre-crisis levels. The middle market is a somewhat unique case, in that investor enthusiasm at this end of the market is much more palpable today than it was ten years ago. Through Q3 2018, combined deal value in the middle market is almost double 2008 value, $312 billion to $169 billion. With a quarter left to go, the US middle market is almost assured of record numbers for both volume and dollars. Should another significant correction be lurking around the corner, it may be the middle market that absorbs most of the pain the next time around. The optimism is understandable—middle market companies have more runway in terms of revenue growth and geographic expansion versus their blue-chip peers. But paying a 12x multiple at entry requires some pretty aggressive exit assumptions, especially when interest rates are expected to be visibly higher in 4-6 years. Investors are confident at the moment—add-ons help boost in earnings and help blend down the multiples paid for the original platform, so 12x could turn into 10x over time. Meanwhile, the recent fundraising surge has provided the resources PEGs need to out-compete each other at every auction. Price tags have ballooned as a result, with no end in sight at the moment. High entry prices are a given today, and it’s worth wondering how many investors have modified their assumptions based on the current environment.
Contact: Alex Lykken
alex.lykken@pitchbook.com



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.