


Download PitchBook’s Report here.
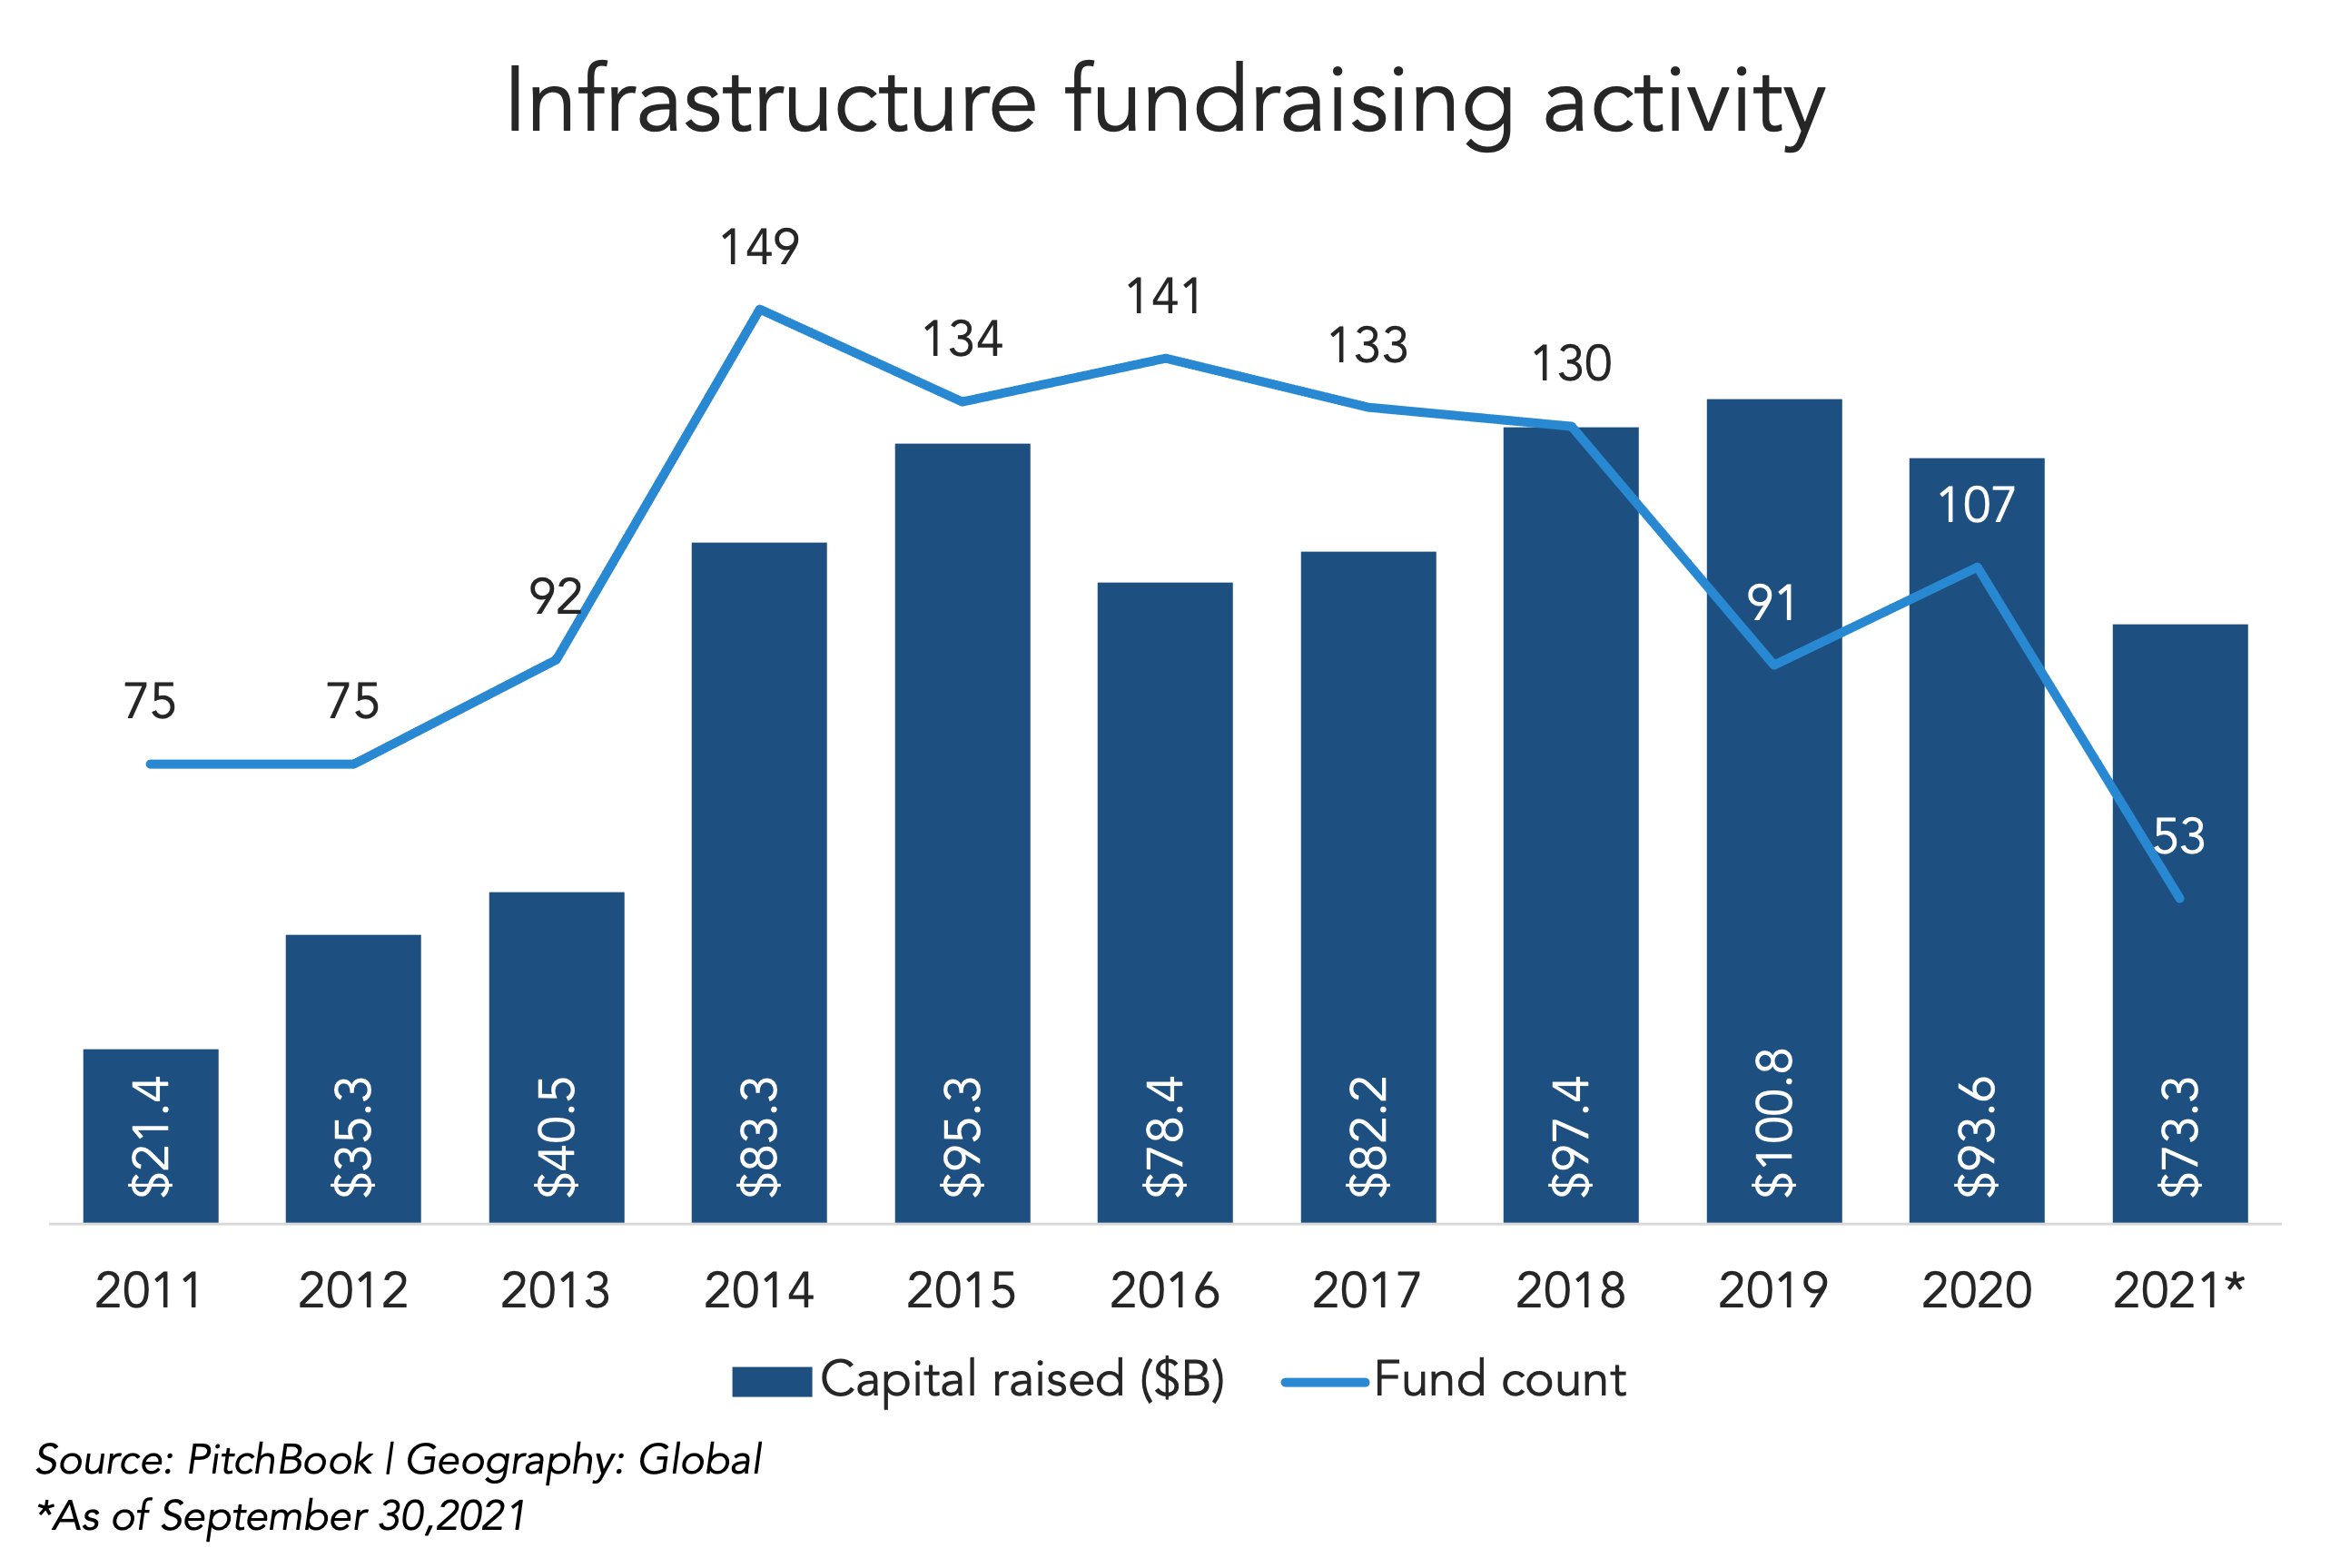
Infrastructure is much in the news these days, given the massive spending bill currently being legislated in the US government, as well as even more earmarks being discussed worldwide by other nations. The potential implications of such significant investment in infrastructure, particularly in digital and energy, pose an interesting array of opportunities for private players. Based on the latest PitchBook datasets from the recently released Q3 2021 Global Real Assets Report, infrastructure funds have close to $290 billion in dry powder as of Q1 2021—meaning a new record has likely already been set at the time of this writing. That immense tally is due to the steadiness of fundraising over the past half-decade worldwide, in a testament to limited partners’ desire for exposure to the classically resilient infrastructure asset class. However, given the imperative for investment in upgrading aging grids, roadways and more, especially in an era that seems determined to head toward inflationary pressures, there could be even more capital flowing into infrastructure funds raised by PE groups. In particular, PE giants like Blackstone or Carlyle are likely to tackle the larger end of the market given their mega-vehicles, while smaller managers can differentiate themselves with a value-added approach toward smaller, fledgling assets.
(Past performance is no guarantee of future results.)




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.