


Download PitchBook’s Report here.
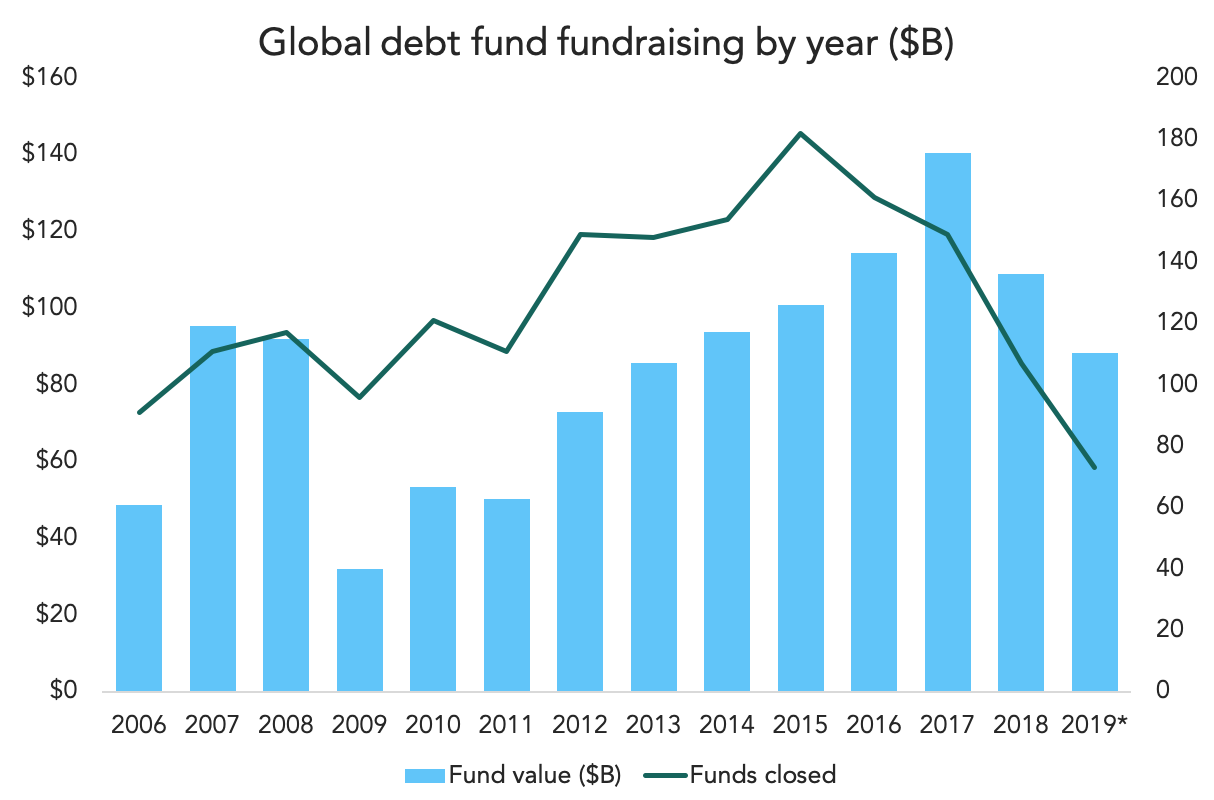
Last week we previewed our upcoming webinar with ACG on how our 2019 private equity predictions panned out. This week’s rearview assessments is one of our misses—we thought private debt fundraising levels would rebound off of a slower 2018. Slow being relative, as it was still one of the highest years on record, just not as high as a record-breaking 2017. Through mid-November, we can’t call 2018 a rebound for fundraising, as fund counts and combined commitments were both below 2018 levels. Fund counts in particular were lower than we expected, with only 73 closes compared to 107 last year and 149 in 2017. Fund sizes evidently remained healthy, with $88.3 billion committed across those 73 funds versus $109 billion across 107 vehicles in 2018. That would put this year’s average around $1.2 billion, a touch higher than a ~$1 billion average in 2018.
Nonetheless, fundraising hasn’t been as good this year as we expected. We noted in our prediction last December that there were, at the time, 40 open or announced private debt funds in the market of at least $1 billion each. That turned out to be not a solid enough floor to leap past 2018 levels, which makes us wonder if private debt fundraising has normalized following an exuberant 2017. Capital availability is at a strong point; if we add up the past three years instead of comparing them, the market has been inundated to the tune of $338 billion. Perhaps LP appetite has waned, though we’ve highlighted the strong returns for the private debt asset class in past notes. Compared to the Bloomberg Barclays US Corporate High Yield Index, private debt funds have outperformed in 10 of the 15 years between 2001 and 2015. If anything, the past several years have only increased LP interest in the asset class.
One asset manager told the Financial Times in 2017 that “if you can breathe fog in a mirror” you could have qualified for loans out of these funds. Industry leaders warned last year of possible “bubble status,” not only because of the amount of capital floating around but also because of recent cov-lite worries. 2019’s poor showing may have to do with broader market concerns, as well.



Latest news
PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.