


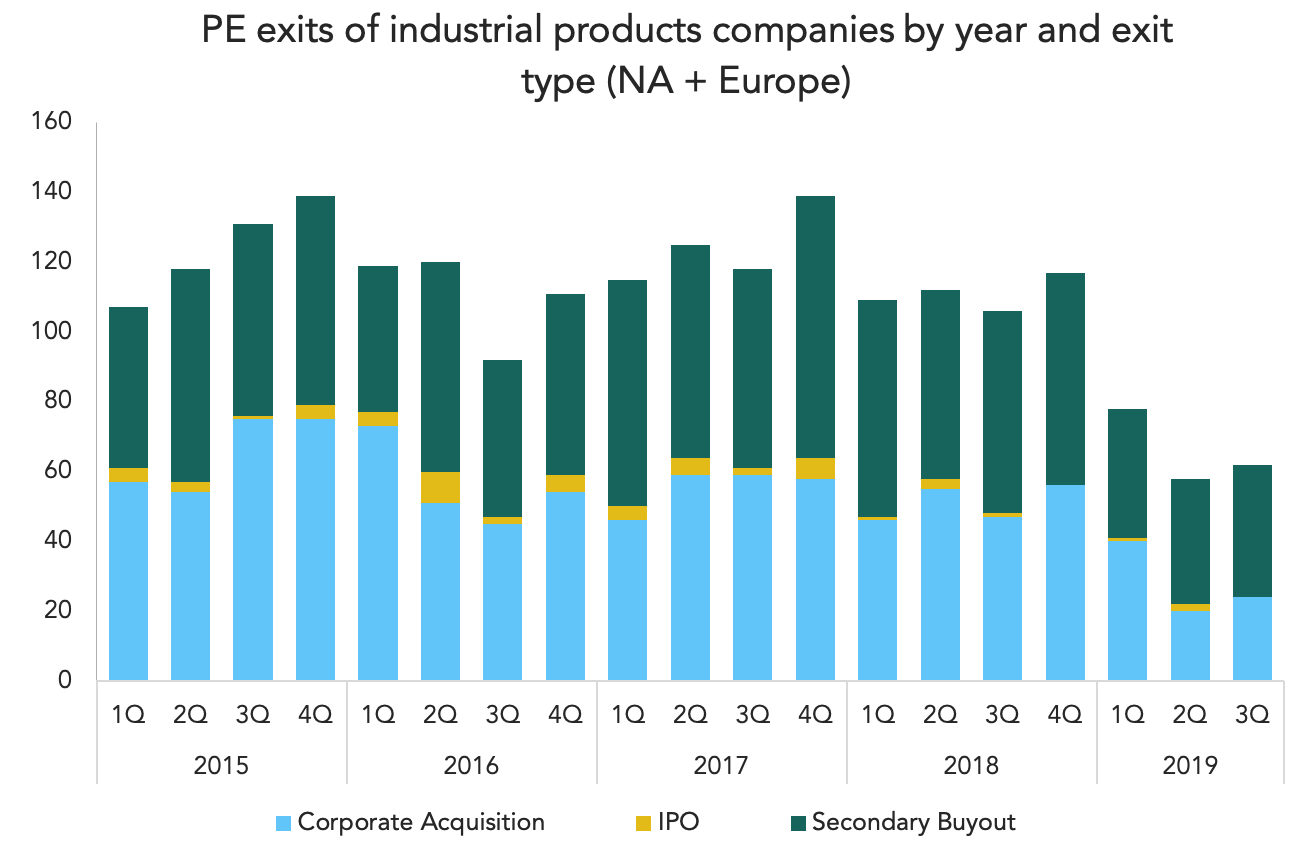
We covered China-driven M&A last week, noting that activity has taken a nosedive this year. Chinese acquirers aren’t buying many American companies at the moment, thanks in part to the broader trade war. According to a newly released report from PitchBook and RSM, however, PE is having a rough time exiting manufacturing companies across the board this year, regardless of where the buyer comes from. Sales to strategic buyers are way down, totaling only 84 through Q3. Barring a miraculous fourth quarter, PE-to-corporate sales on the manufacturing side will fall below 200 (by volume) for the first time since 2010.
The numbers suggest the trade war is more of a sell-side problem than a buy-side one. Across North America and Europe, it’s within the realm of possibility that 2019 PE deal activity will approach last year’s record numbers, despite the rollercoaster ride on the policy front. It would take a strong Q4 for that to happen, but it’s shaping up to be another strong buy-side year for manufacturing in any event. One evergreen explanation is the amount of dry powder that has to be put to work: “Of course deal volume is healthy, what else are they going to do?” Also at play, perhaps, is some long-term thinking on the part of PE firms. The market has been dealing with tariffs for almost two years now, and while we haven’t had a trade war in a while, long-term investors understand that they don’t last forever. In fact, it’s a bit easier to see where things are going today compared to January 2018, when the first tariffs were slapped on solar panels and washing machines. Short-term bets would be harder to justify in today’s market, which is working through evolving supply chain disruptions and other major headaches. Long-term investors are likely game-planning for several scenarios before finalizing any deals. PE firms can adjust if they have to.
The thinking appears different for corporate buyers, who are said to be waiting out the uncertainty. It’s hard to blame them, but it’s fun to see the supposedly risk-averse PE industry barreling ahead while strategic acquirers sit on the sidelines. It must be frustrating, though, to be a sell-side PEG.




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.