


Download PitchBook’s Report here.
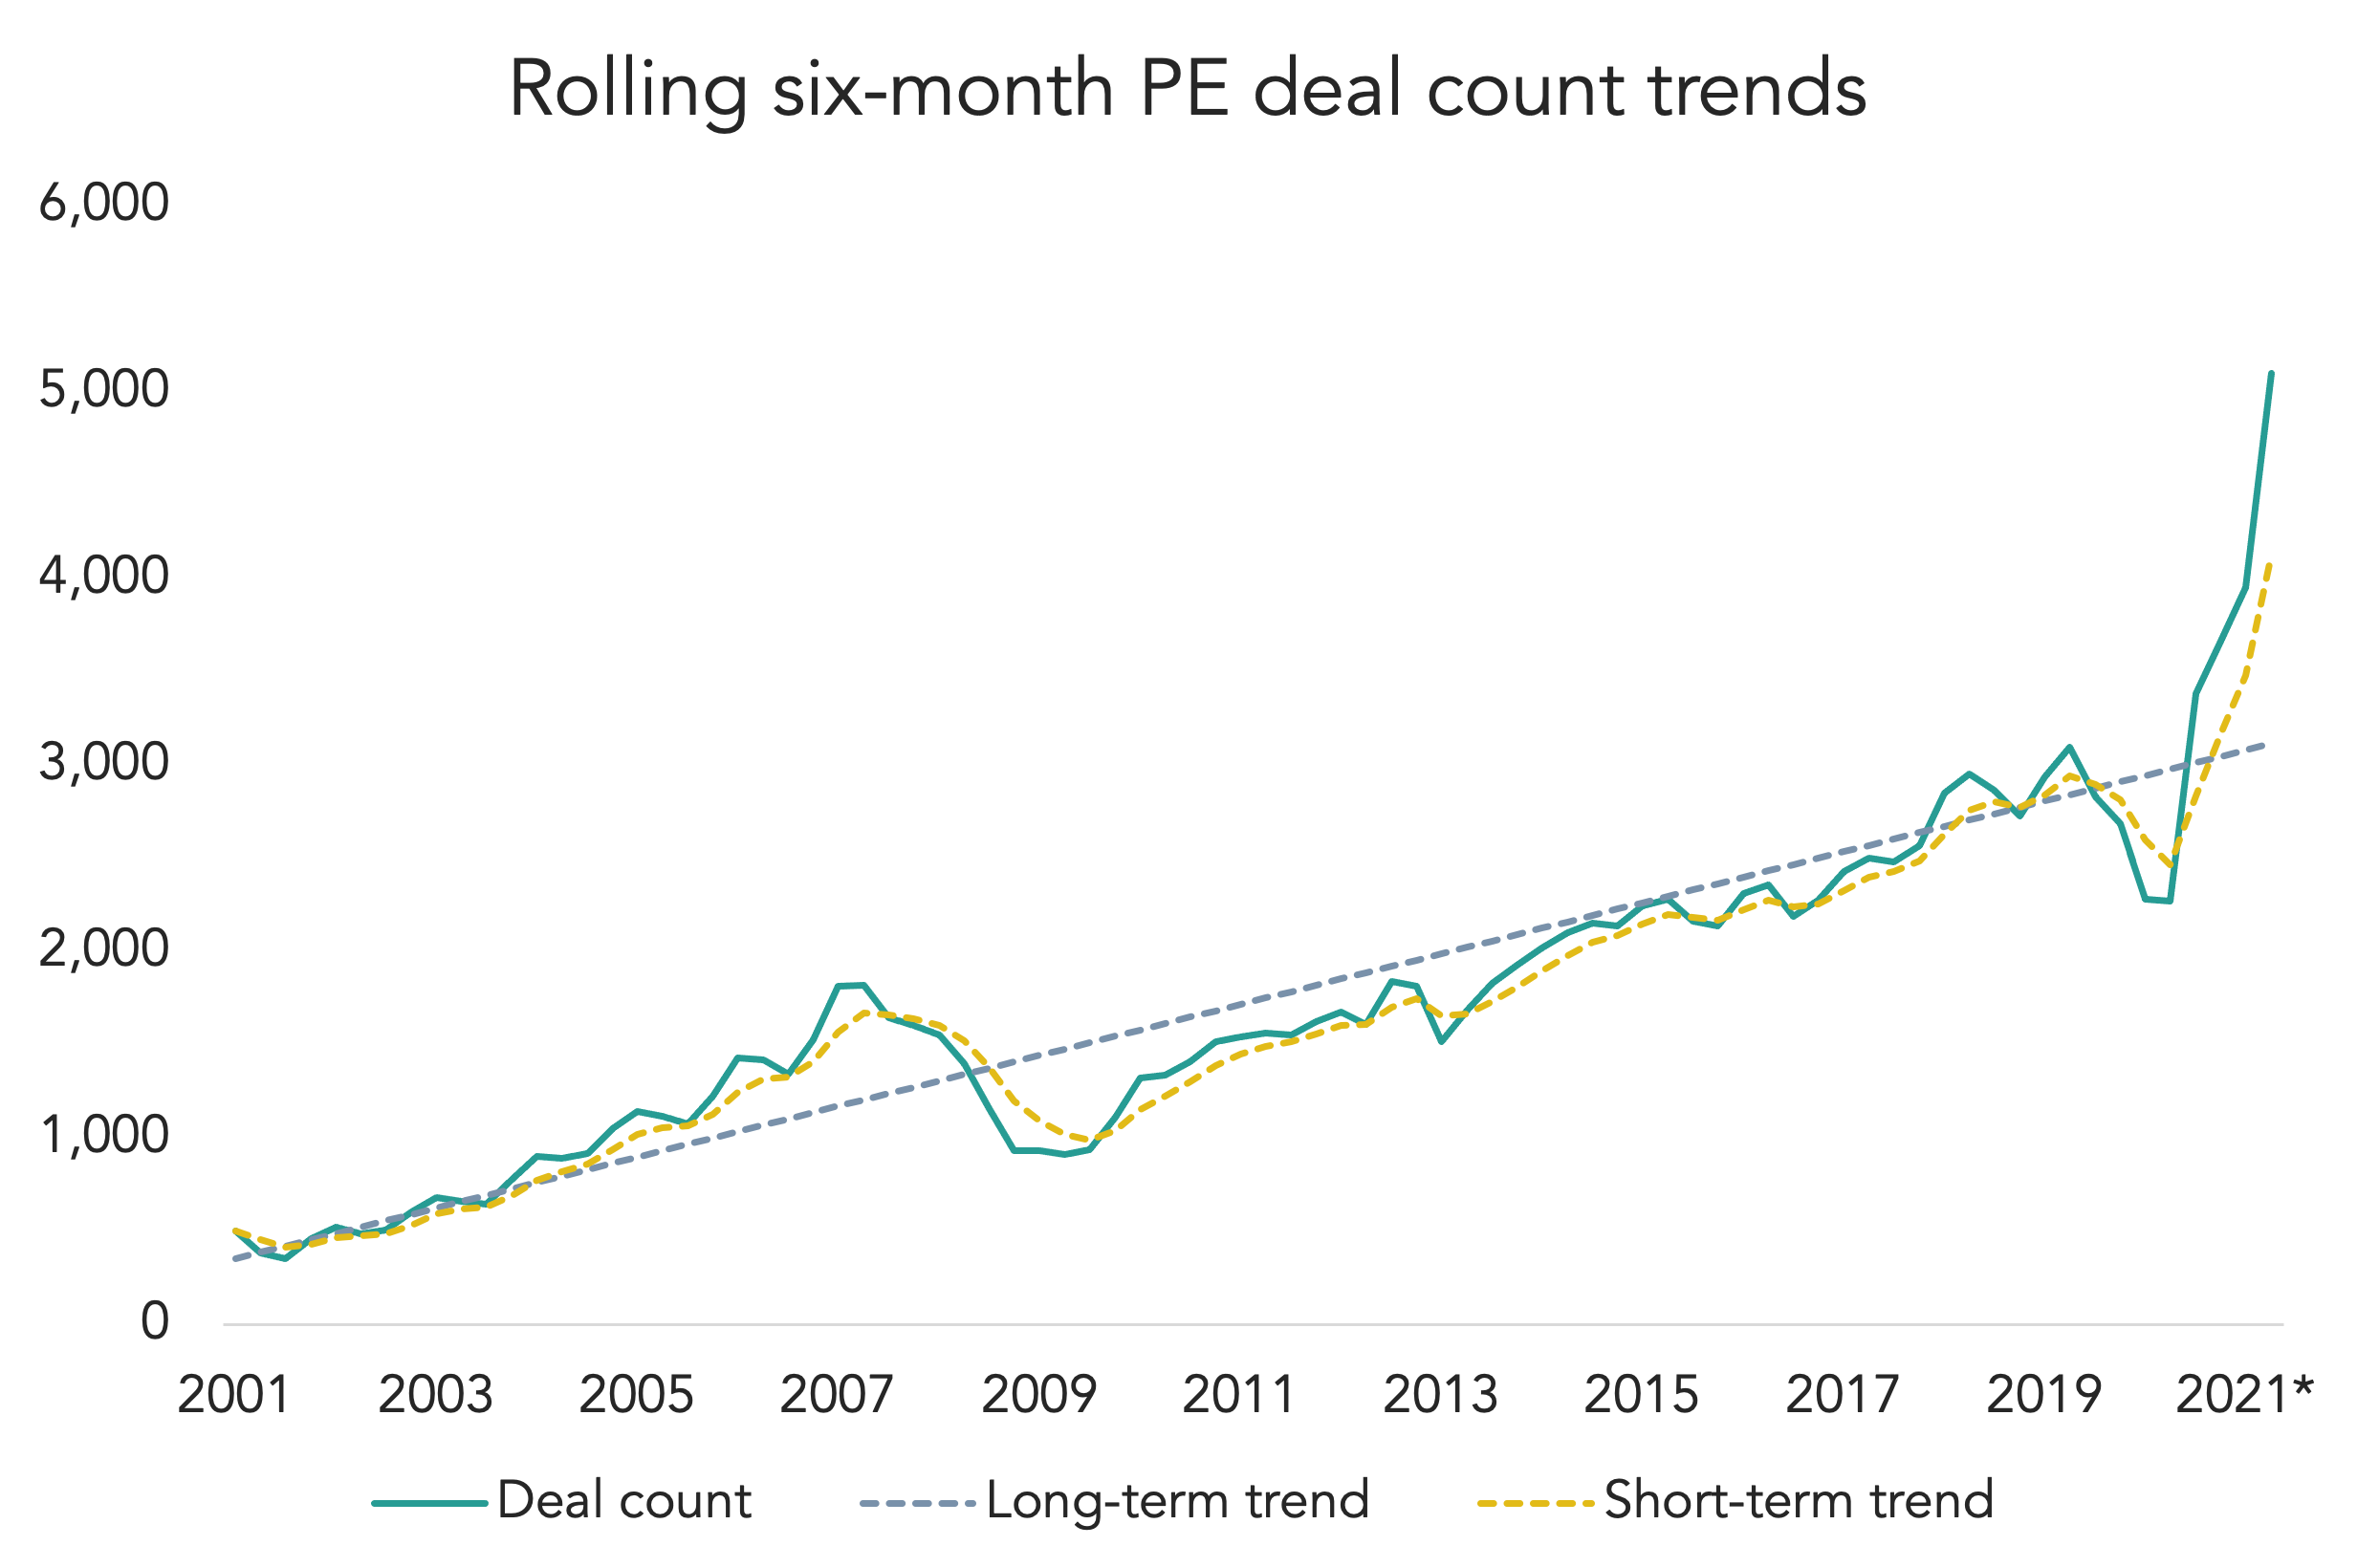
It’s no secret that private equity is having a big year. A new PitchBook Quantitative Perspectives report, US PE: Recovery and Beyond, helps put this year into historical context. The past few quarters have been such a pronounced recovery that deal volume is now well above the 20-year, long-term trendline. If technical analysis mattered in private equity, the chart above would cause heart palpitations. To a certain degree, the spike in the short-term trendline is investors making up for lost time, combined with opportunistic dealmaking. But today’s recovery is nothing like the 2008 financial crisis: dealmaking declined swiftly that year and remained below the long-term trendline until 2014. In other words, it took about five years for PE dealmaking to get back on course after the financial crisis. For the COVID crisis, dealmaking jumped back to the long-term trendline in about three quarters, and is now way, way above it heading into 2022.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
