


PE’s Other Overhang
For several years now, the increase in the inventory of companies backed by private equity in North America and Europe has essentially plateaued. In stark contrast to the steady ramp-up in inventory during the buyout boom era, this trend can be ascribed to a few key drivers, including the healthy exit environment, elevated deal multiples and a competitive dealmaking environment, as well as the fact many firms still hold a fair amount of aged inventory already. 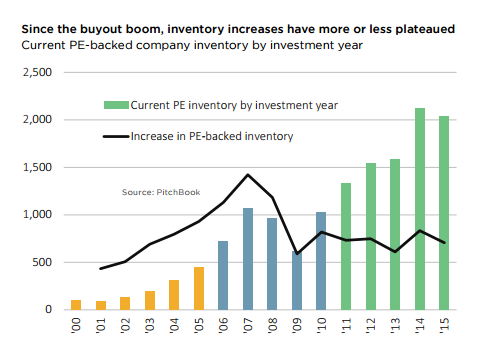 PE firms have been putting their money to work in other ways than strict buyouts, such as taking minority stakes, looking to reduce the industry’s other overhang of undeployed capital. As investment strategies have diversified, accordingly, it’s worthwhile to wonder if inventory will ever increase again at even half the rate seen last decade. If fears of an oncoming economic malaise if not outright recession are proved true, PE firms could take advantage of growing distress across more sectors than just, say, energy, where investors are anticipated to ramp up activity soon. That could produce a boost of sorts to the inventory. Yet by and large, the seller’s market may well counterbalance the company inventory, simply as PE firms seek to liquidate the most elderly of their holdings, in what could be the waning stages of an M&A boom cycle.



Latest news

European mid-market direct lending margins face steady compression since 2024
European mid-market direct lending margins have seen consistent compression over recent years but recorded a slight increase in the second quarter of 2026…

US leveraged loan issuance rebounds in September
Following three consecutive months of declining issuance, the US leveraged loan market has reversed course in September. Approximately $48.7b of…

Reversion to the Mean
Climbing toward the average is a very different story than surpassing it.