


Download PitchBook’s Report here.
Perpetual vehicles for the private wealth investor, also known as semiliquid funds, raised $122 billion in 2024. We estimate that 55% of that fundraising has flowed to private debt strategies ranging from nontraded business development companies (BDCs) to interval funds with broader mandates to tender offer funds with more opportunistic or specialty credit approaches. This puts the category in line to have raised $67 billion for the year for various private debt strategies—an approximately 40% YoY increase. Several of the megaalternative managers targeted 25% of all fundraising to come from the wealth channel, and a few have already arrived— including Blue Owl, which derived $13.7 billion of its $27.5 billion in 2024 fundraising from the private wealth channel, primarily in its private debt products.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

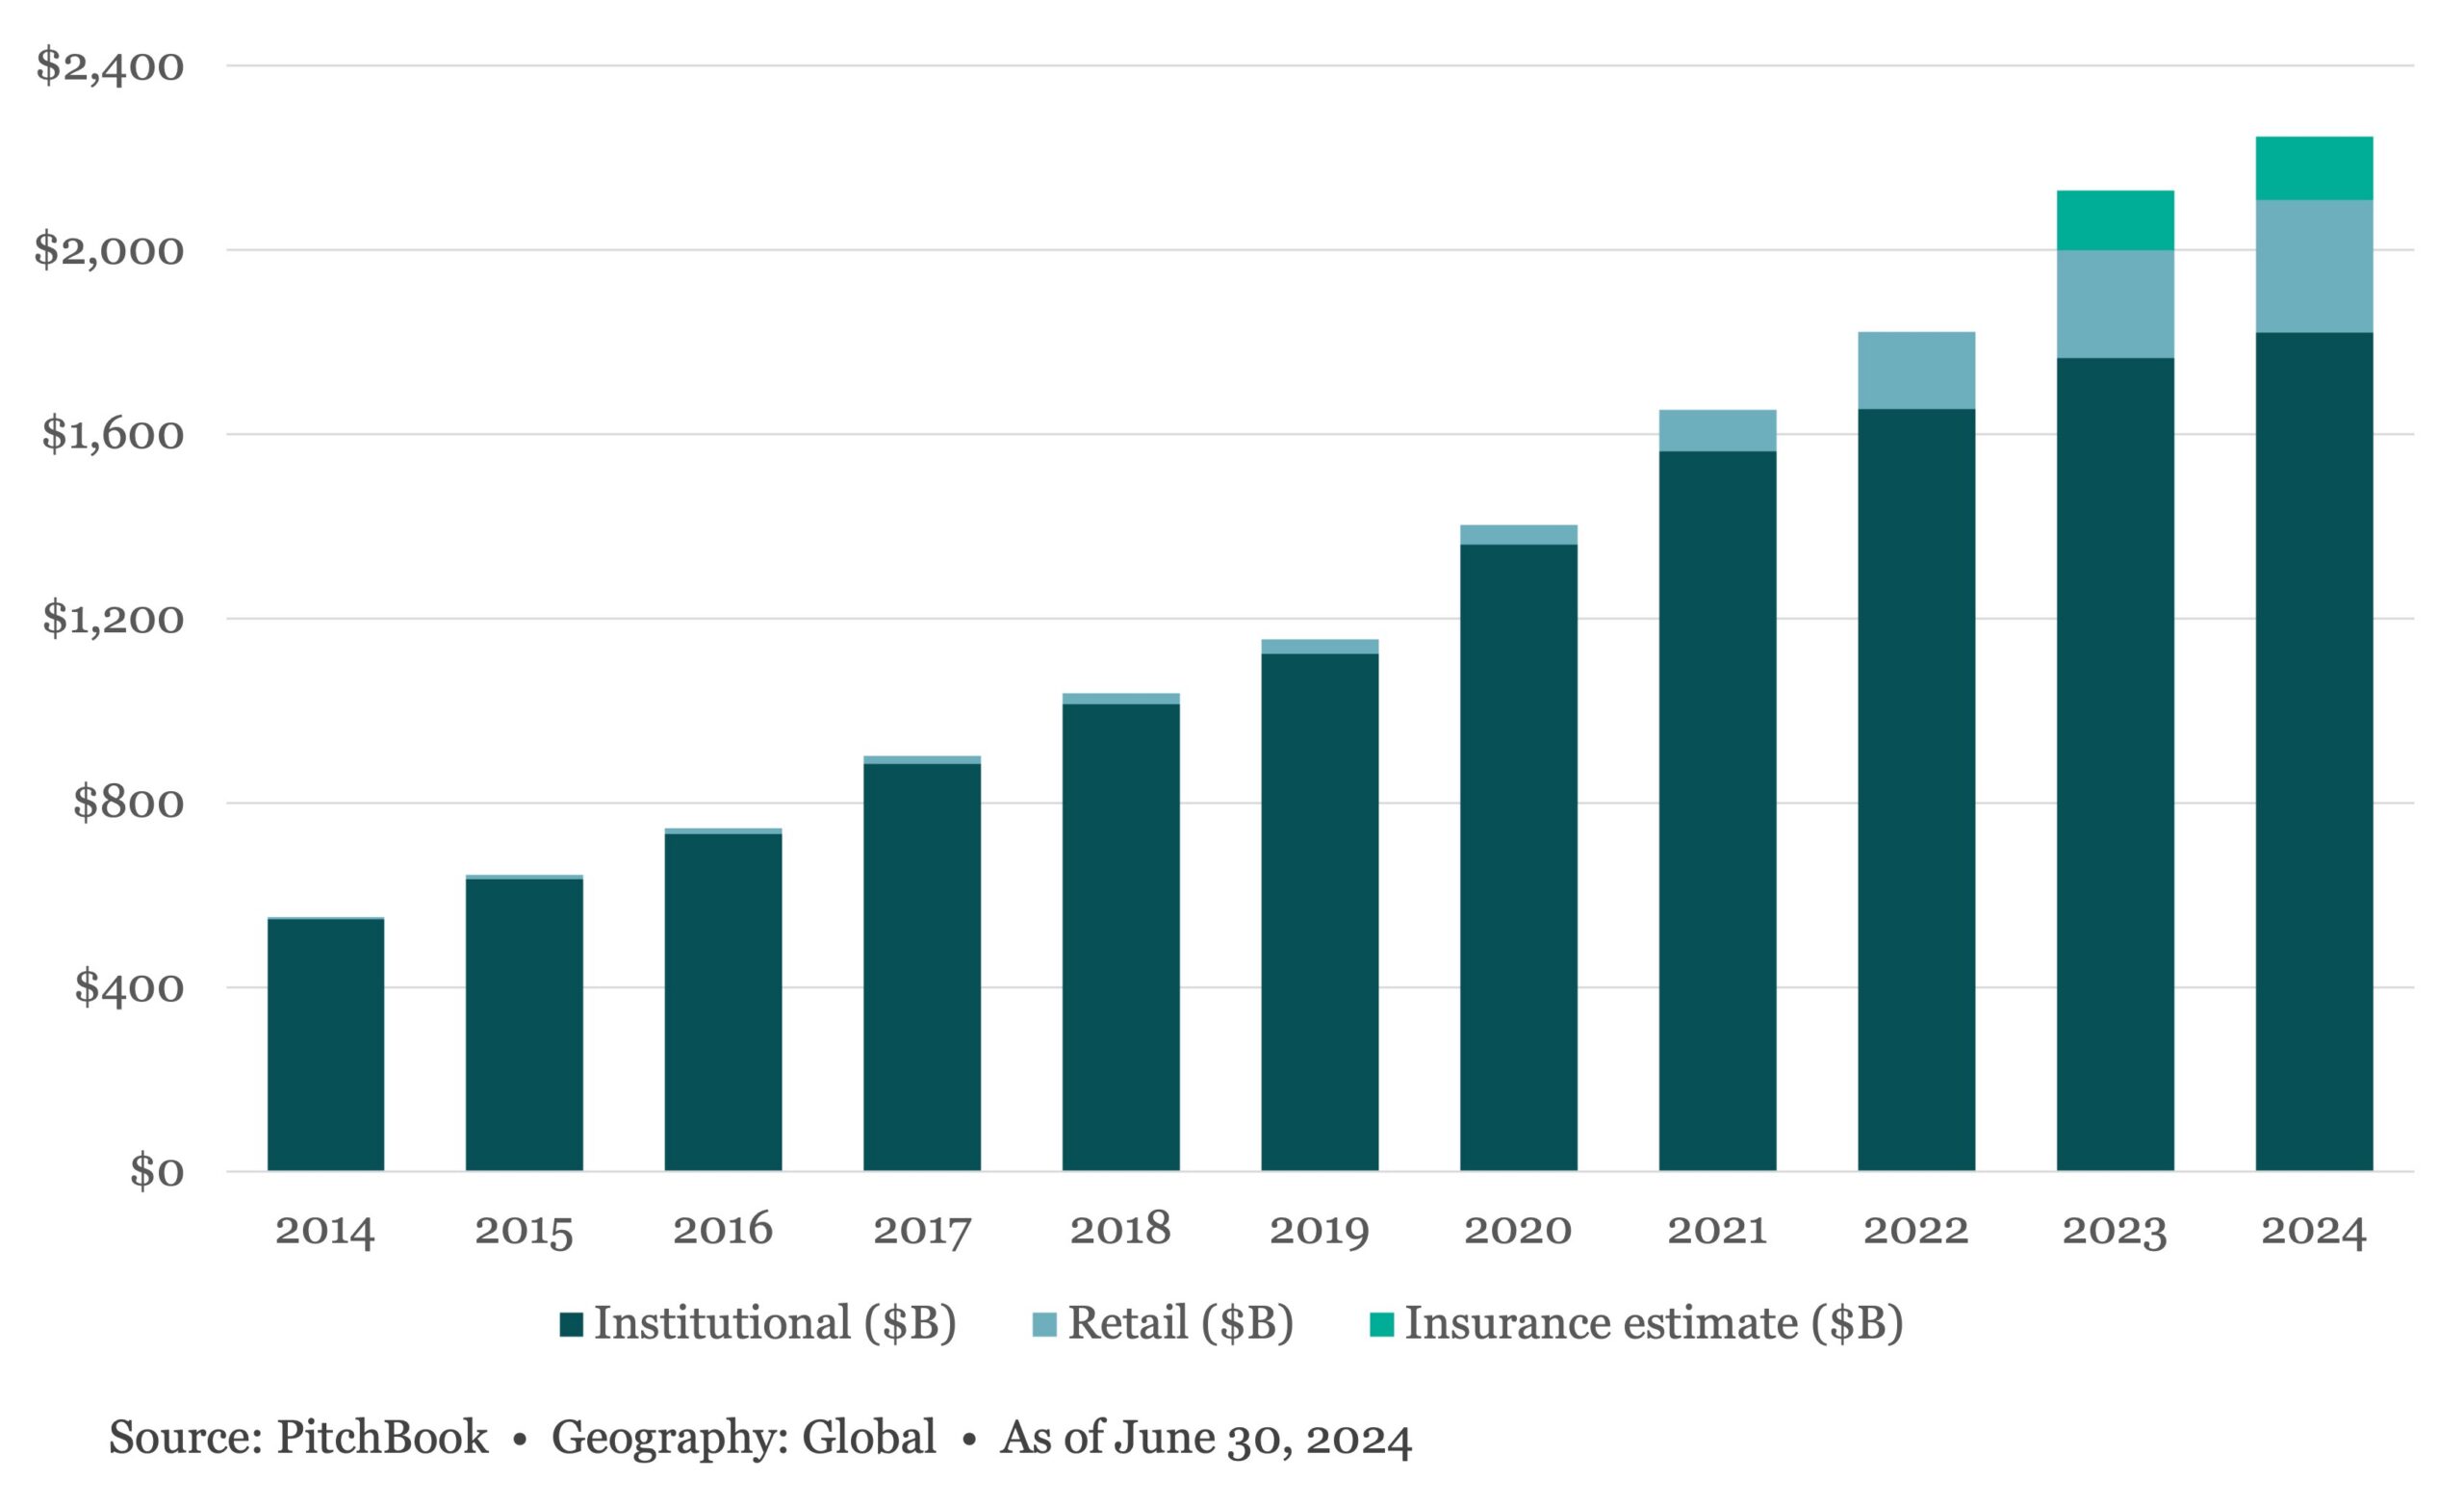
US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
