



Download PitchBook’s Report here.
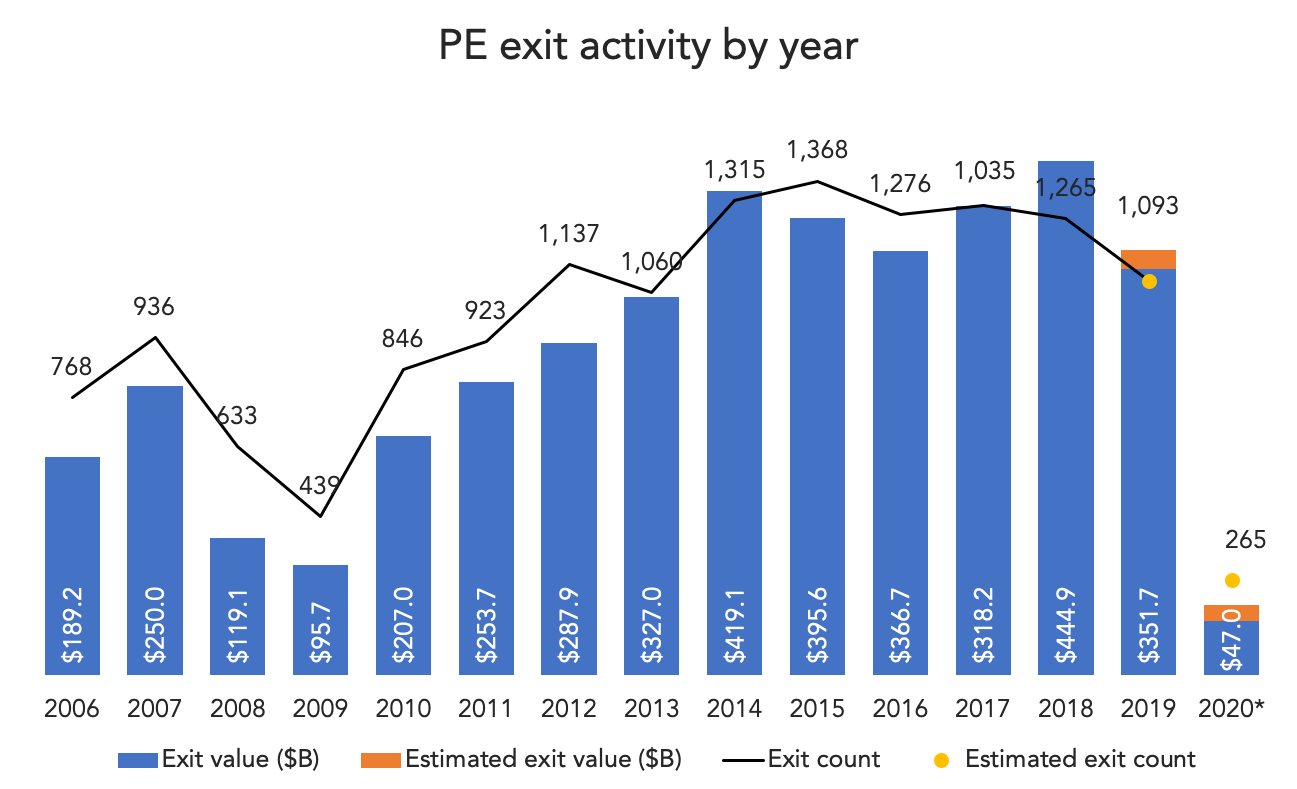
Exit activity is bound for a tough year, as preliminary Q1 numbers confirm. Historically, first quarter exit totals are typically on the low end anyway; it’s common to see a lull coming off of fourth quarter sprints. Q1 2020 was slow even by that forgiving standard, down 37.3% YoY on a value basis, according to PitchBook’s just-released Private Equity Breakdown Report. Counts, interestingly, were flat, but we expect volume to be hit just as hard in the months ahead.
All three standard exit routes are problematic. IPOs are hard to consider; 1,000-point swings have become routine, and even intraday trading can oscillate wildly on an afternoon news report. Until a vaccine is approved, the public markets are reserving the right to assume the worst, and PE sponsors will look elsewhere. M&A is just as unpredictable. Until we’re confident we’ve hit bottom, both pandemically and economically, buyers won’t be buying and sellers won’t be selling, particularly sell-side PE. Sponsors are loathe to sell at these types of discounts, and secondary buyouts should see a steep drop in volume for the same reason. Most M&A will come to a standstill as everyone waits for prices to stabilize; for PE that will translate to longer holding periods. Post-GFC, holding times became progressively longer over the next five years. Perhaps the aftermath of this crisis won’t stretch as long, but the historical data suggests a slog is ahead.
Adding to all that is the energy sector, which is being hit the hardest. Energy makes up a material percentage of overall PE exit activity and will contribute to slowing volume as long as trends continue.
Many exits are in limbo, having been agreed to months ago but now thrown into question. Buyers are blanching and trying to get out of those agreements legally. Force majeure (unforeseen calamity) clauses are popping up, but even global pandemics don’t always get them off the hook. The “unforeseen” argument is getting struck down in some courts, in the cases where the agreement was signed after reports of the Wuhan outbreak emerged. If that’s the standard, agreements signed in December appear to be out of luck. For the first time since 2008/09, PE exit activity will be partially impacted by court decisions.


Latest news

Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.

Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.

Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…