


Download PitchBook’s Report here.
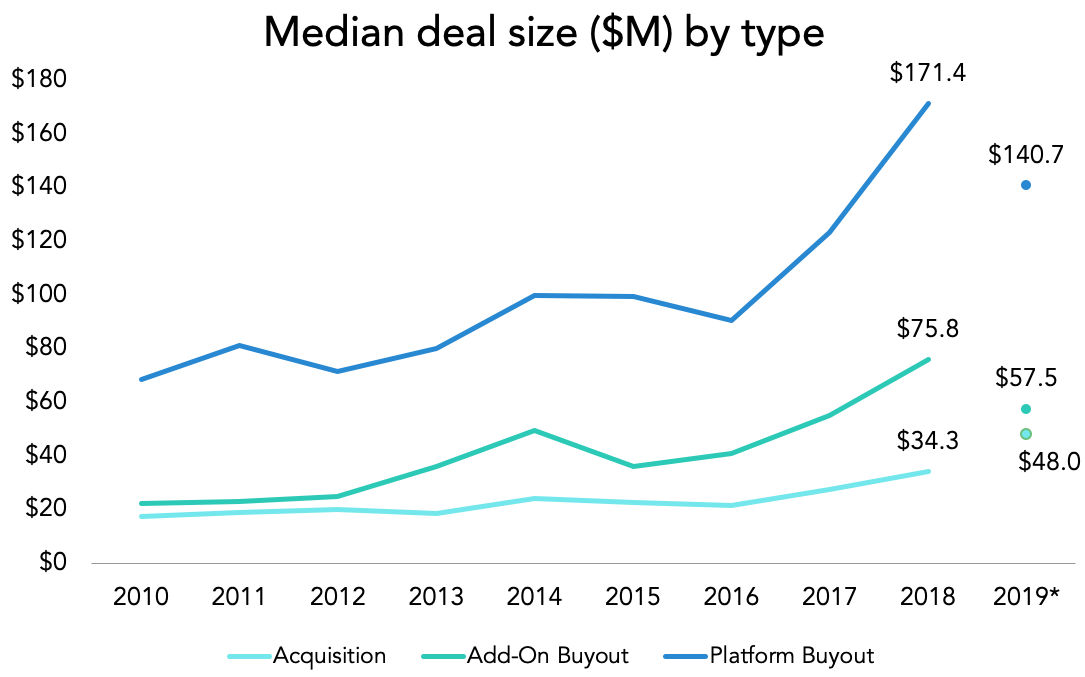
The median add-on size almost doubled in the span of two years. The $41 million median seen in 2016 ballooned to $76 million last year, an 86% difference. At first glance, it looks like platform deal sizes have gone up much more rapidly, but charts can be deceiving—platform buyout sizes increased by 89% in the same timeframe. There are more off-the-shelf explanations on the platform side, however, since platform targets see much more competition, both from fellow PE firms and often from strategic buyers. It’s rare to see any stories about heated auctions for add-on targets. Have you seen any?
The most likely explanation is probably benign. Companies across the board are that much more expensive, whether they take the form of a platform investment or an add-on. There’s also the fact that the buy-and-build model is no longer a secret. In fact, it’s probably one of the most talked-about aspects of today’s PE industry. Management teams of add-on targets might feel they have more leverage on pricing these days, since many add-on targets are specifically identified as ideal add-ons for specific platforms. Investors are still going to go after certain add-ons because their platform thesis might depend on sticking to plan, even if they end up paying a higher price. But at the end of the day, add-on multiples and deal sizes are best analyzed on a case-by-case basis, since each situation is unique. That said, we can point to at least one broader takeaway for the industry as a whole: PEGs have to set aside more capital not only for platforms but for the add-ons they plan to make, as well. Buy-and-builders need to have strong conviction these days, considering that the median add-on size in 2018 ($75.8M) is actually higher than the median platform buyout from only seven years ago ($71.7M in 2012).



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…