


Download PitchBook’s Report here.
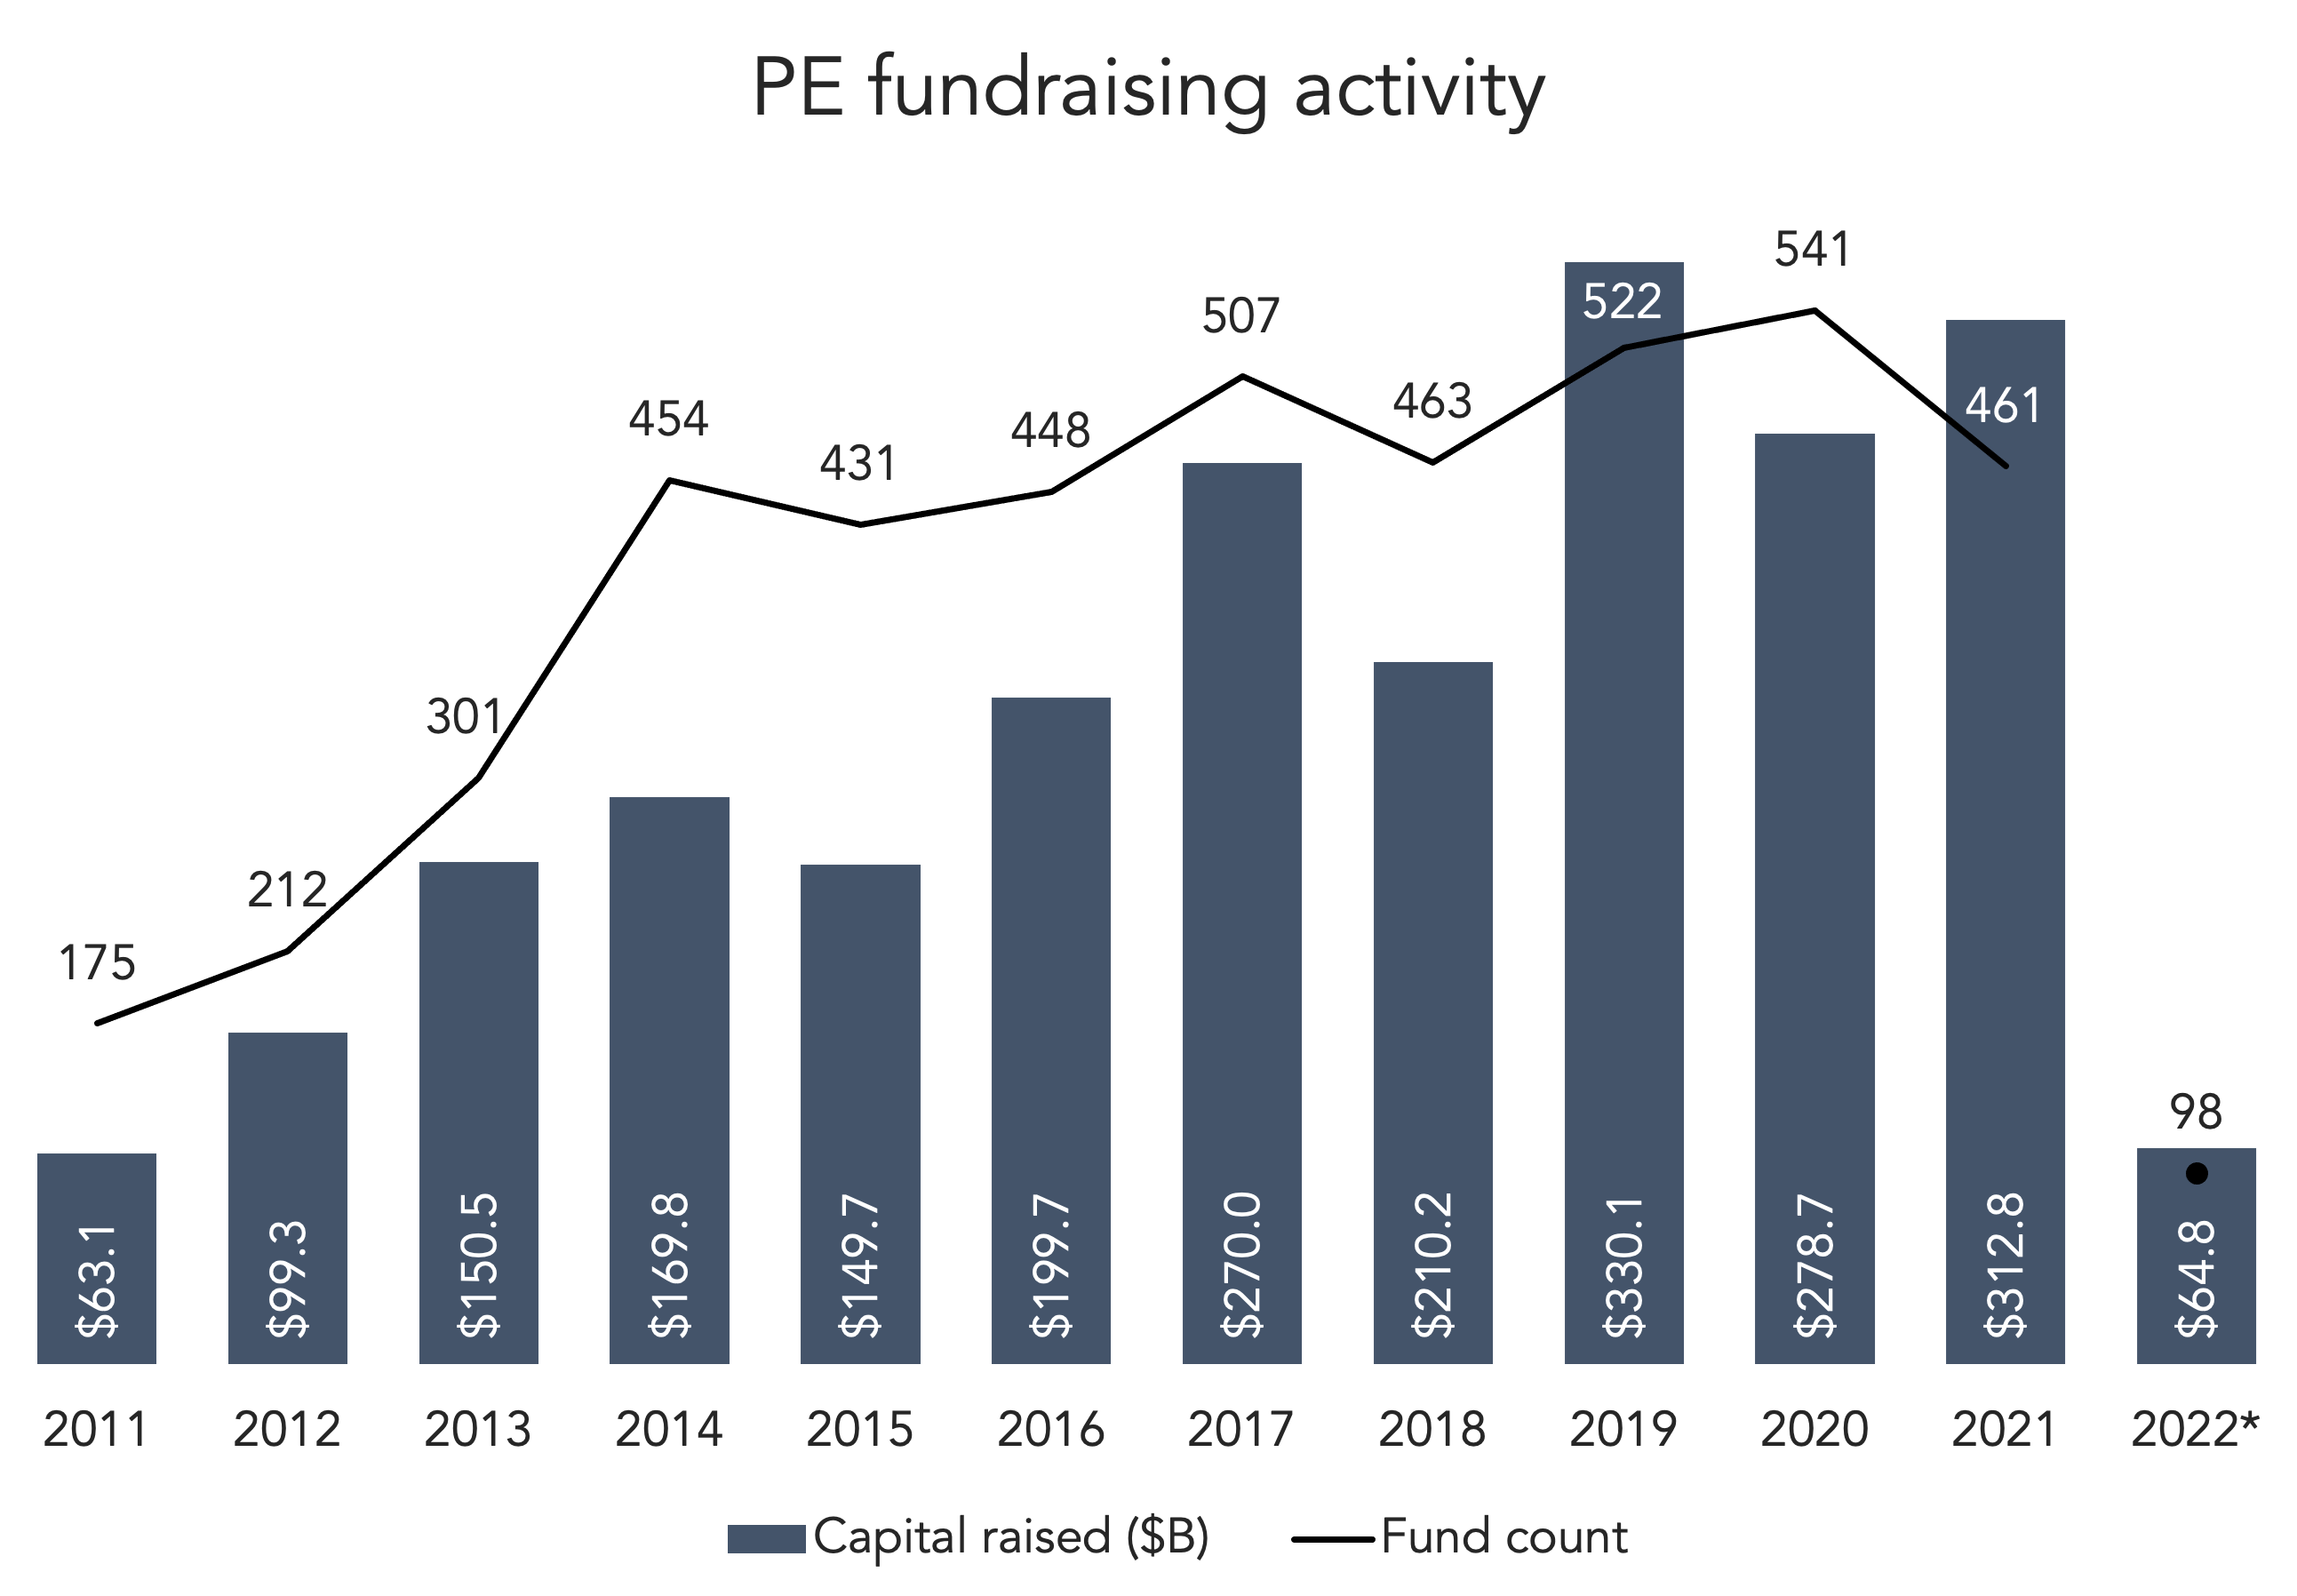
Market turmoil continues. The ripple effects will impact private equity deal flow and exits, and it will certainly impact fundraising. Our latest analyst note sees fundraising “tapering as demand outstrips supply.” PEGs have been returning and re-returning to the fundraising trail over the past few years, inundating LPs with new opportunities. The note points out that “some top-decile buyout firms with track records of 20 years or longer are struggling to raise capital.”
If equities continue to slide, the PE market may be facing a denominator effect in coming quarters. Any sustained decline in an LP’s public equity allocation could artificially push the LP’s PE exposure well past its allocation target. LPs will have a better sense of where they are when their PE managers report their quarterly portfolio valuations to investors. Funds already on the market may need to close below their target size, or would need to anticipate delayed closes. All of this would be a sharp reversal from recent history, which has been partially fueled by the reverse denominator effect: rising equity prices can inflate equity allocations and shrink PE allocations, almost forcing LPs to invest in more PE funds just to keep up.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
