


Download PitchBook’s Report here.
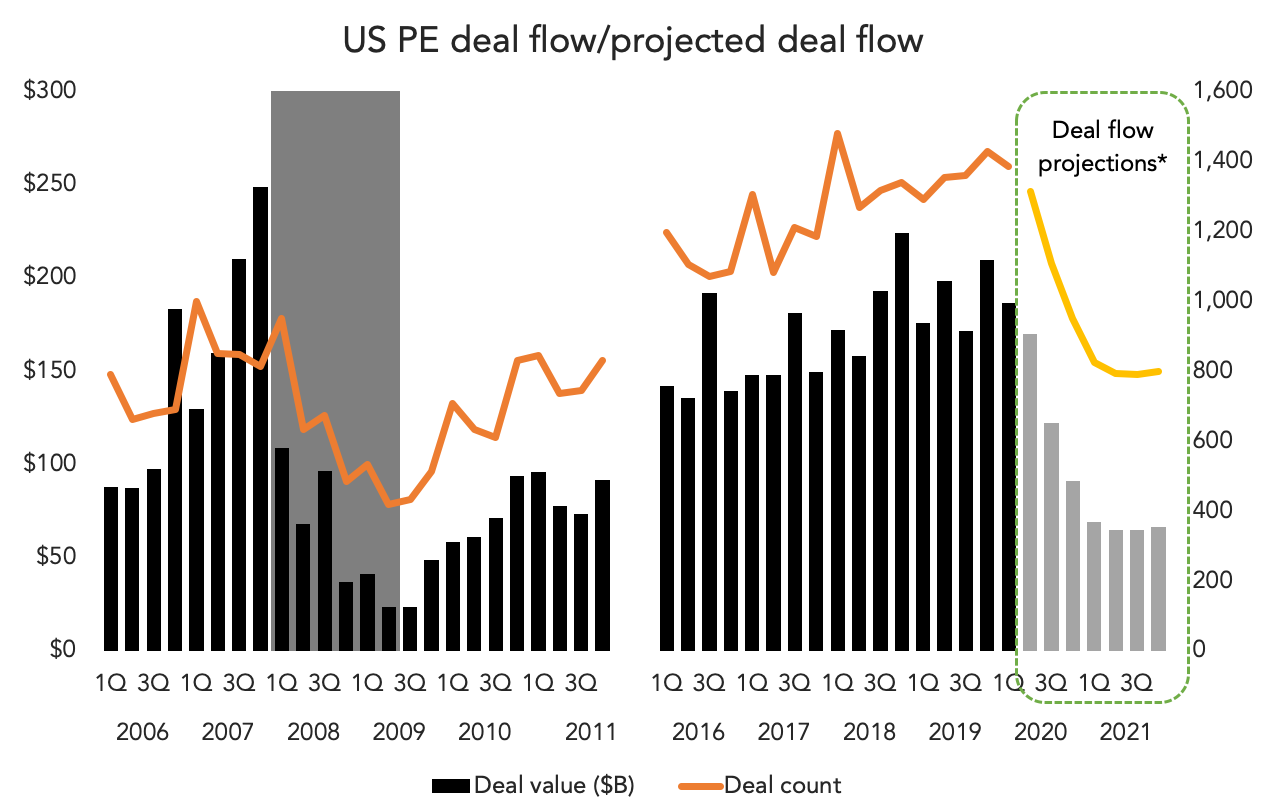
PitchBook analysts expect deal flow to drop fairly substantially over the next several quarters. The trajectory is similar to the drop during the 2008 financial crisis but doesn’t reach the depths that it did in 2009. If our forecasts come close to the truth, deal volume will dip to 2011 levels at its worst. Not great, but not cataclysmic either.
Forecasting deal value is trickier. Outside of dire situations like impending bankruptcies, business owners will be hesitant to sell at depressed prices. We’ve heard anecdotes of owners being bewildered by their current valuations, especially if nothing drastic has changed for them over the past few months. That’s probably a sign of things to come. PE firms will be taking a microscope to cash flow projections while would-be sellers will emphasize how healthy and well-run the company was before the pandemic. In many cases they’ll probably both be right. Perhaps we’ll see fewer disclosed deal prices as a compromise. No need to air dirty laundry and make the company look less valuable than it really is.
Meanwhile, current portfolio companies are already positioning themselves for a post-COVID world. With the worst of the initial fires put out, PE-backed companies are starting to position themselves to scale up and improve operations when the country comes back online. More broadly, many PE-backed companies will end up being well-served by their sponsors when this crisis subsides. It isn’t being talked about yet, but the PE industry has an opportunity to refurbish its image compared to 2008. Last time around, PE was casually lumped in with other bad actors, even though private equity wasn’t remotely responsible for the crash. In the background, and perhaps too quietly, the asset class helped salvage the vast majority of its companies and even made many of them much stronger. They have the opportunity to do the same this time around, but without federal stimulus dollars to lean on. For an industry as maligned as private equity, it should trumpet its role as rescue capital in a scenario like this, before it gets blamed for “taking advantage” of a risky situation while not getting credit for saving companies that may otherwise go out of business.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…