


Download PitchBook’s Report here.
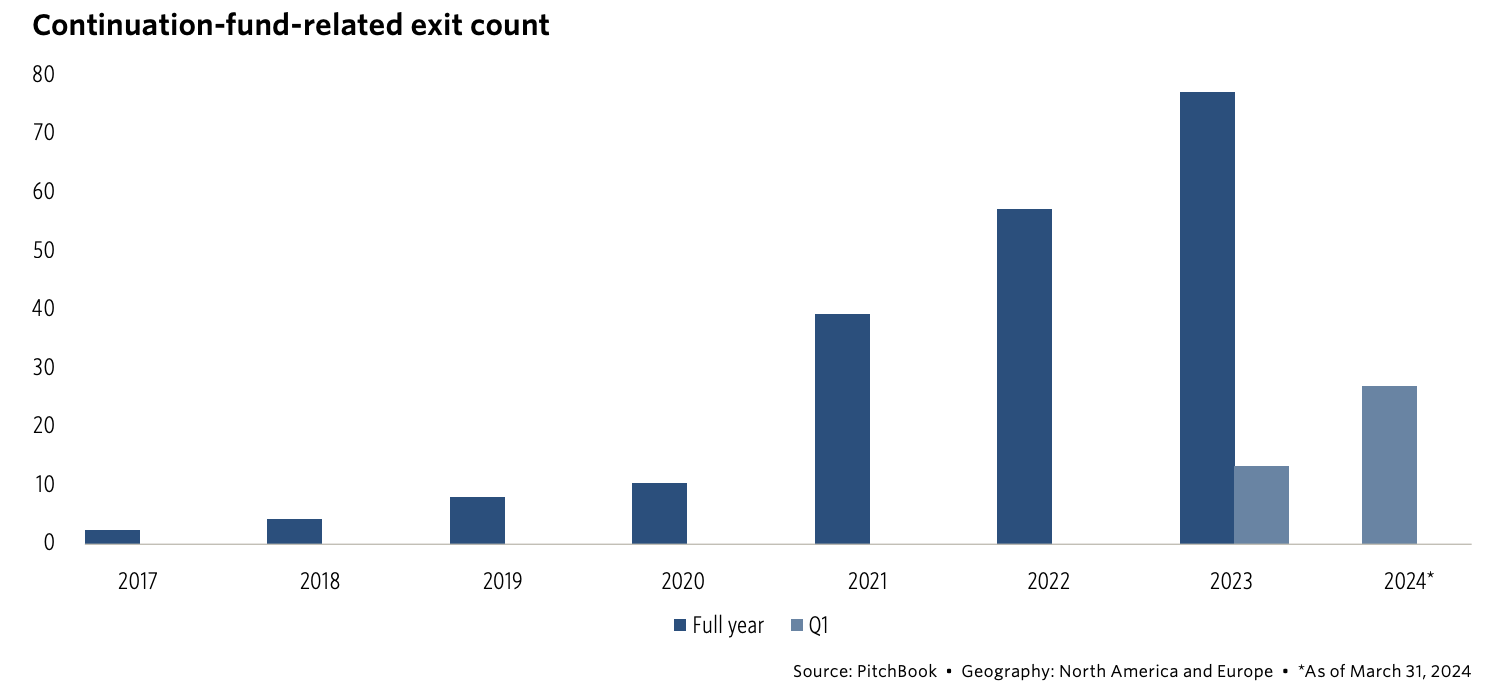
In PitchBook’s 2024 US Private Equity Outlook, we forecast this would be the year that continuation funds hit critical mass and would reach 100 or more exits of this nature. To maintain continuation funds’ growth as a viable liquidity solution, GPs that have launched continuation funds will need to demonstrate successful outcomes. Sure enough, the final day of Q1 yielded the fourth-largest PE exit ever, with Leonard Green & Partners’ (LGP’s) $18.3 billion sale of SRS Distribution (SRS) to Home Depot. The exit was a vindication for PE’s GPled playbook; a percentage of LGP’s stakes in SRS were rolled from two LGP funds into a continuation fund. That transaction provided liquidity to existing investors and secondary access for new investors led by Carlyle’s AlpInvest. We tracked 27 exits relating to continuation funds through the end of Q1 2024 in the US, all hoping for a similar outcome. Q1 2023 saw only 13 continuation-fund-related exits, indicating that this type of exit activity has roughly doubled YoY.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
