


Download PitchBook’s Report here.
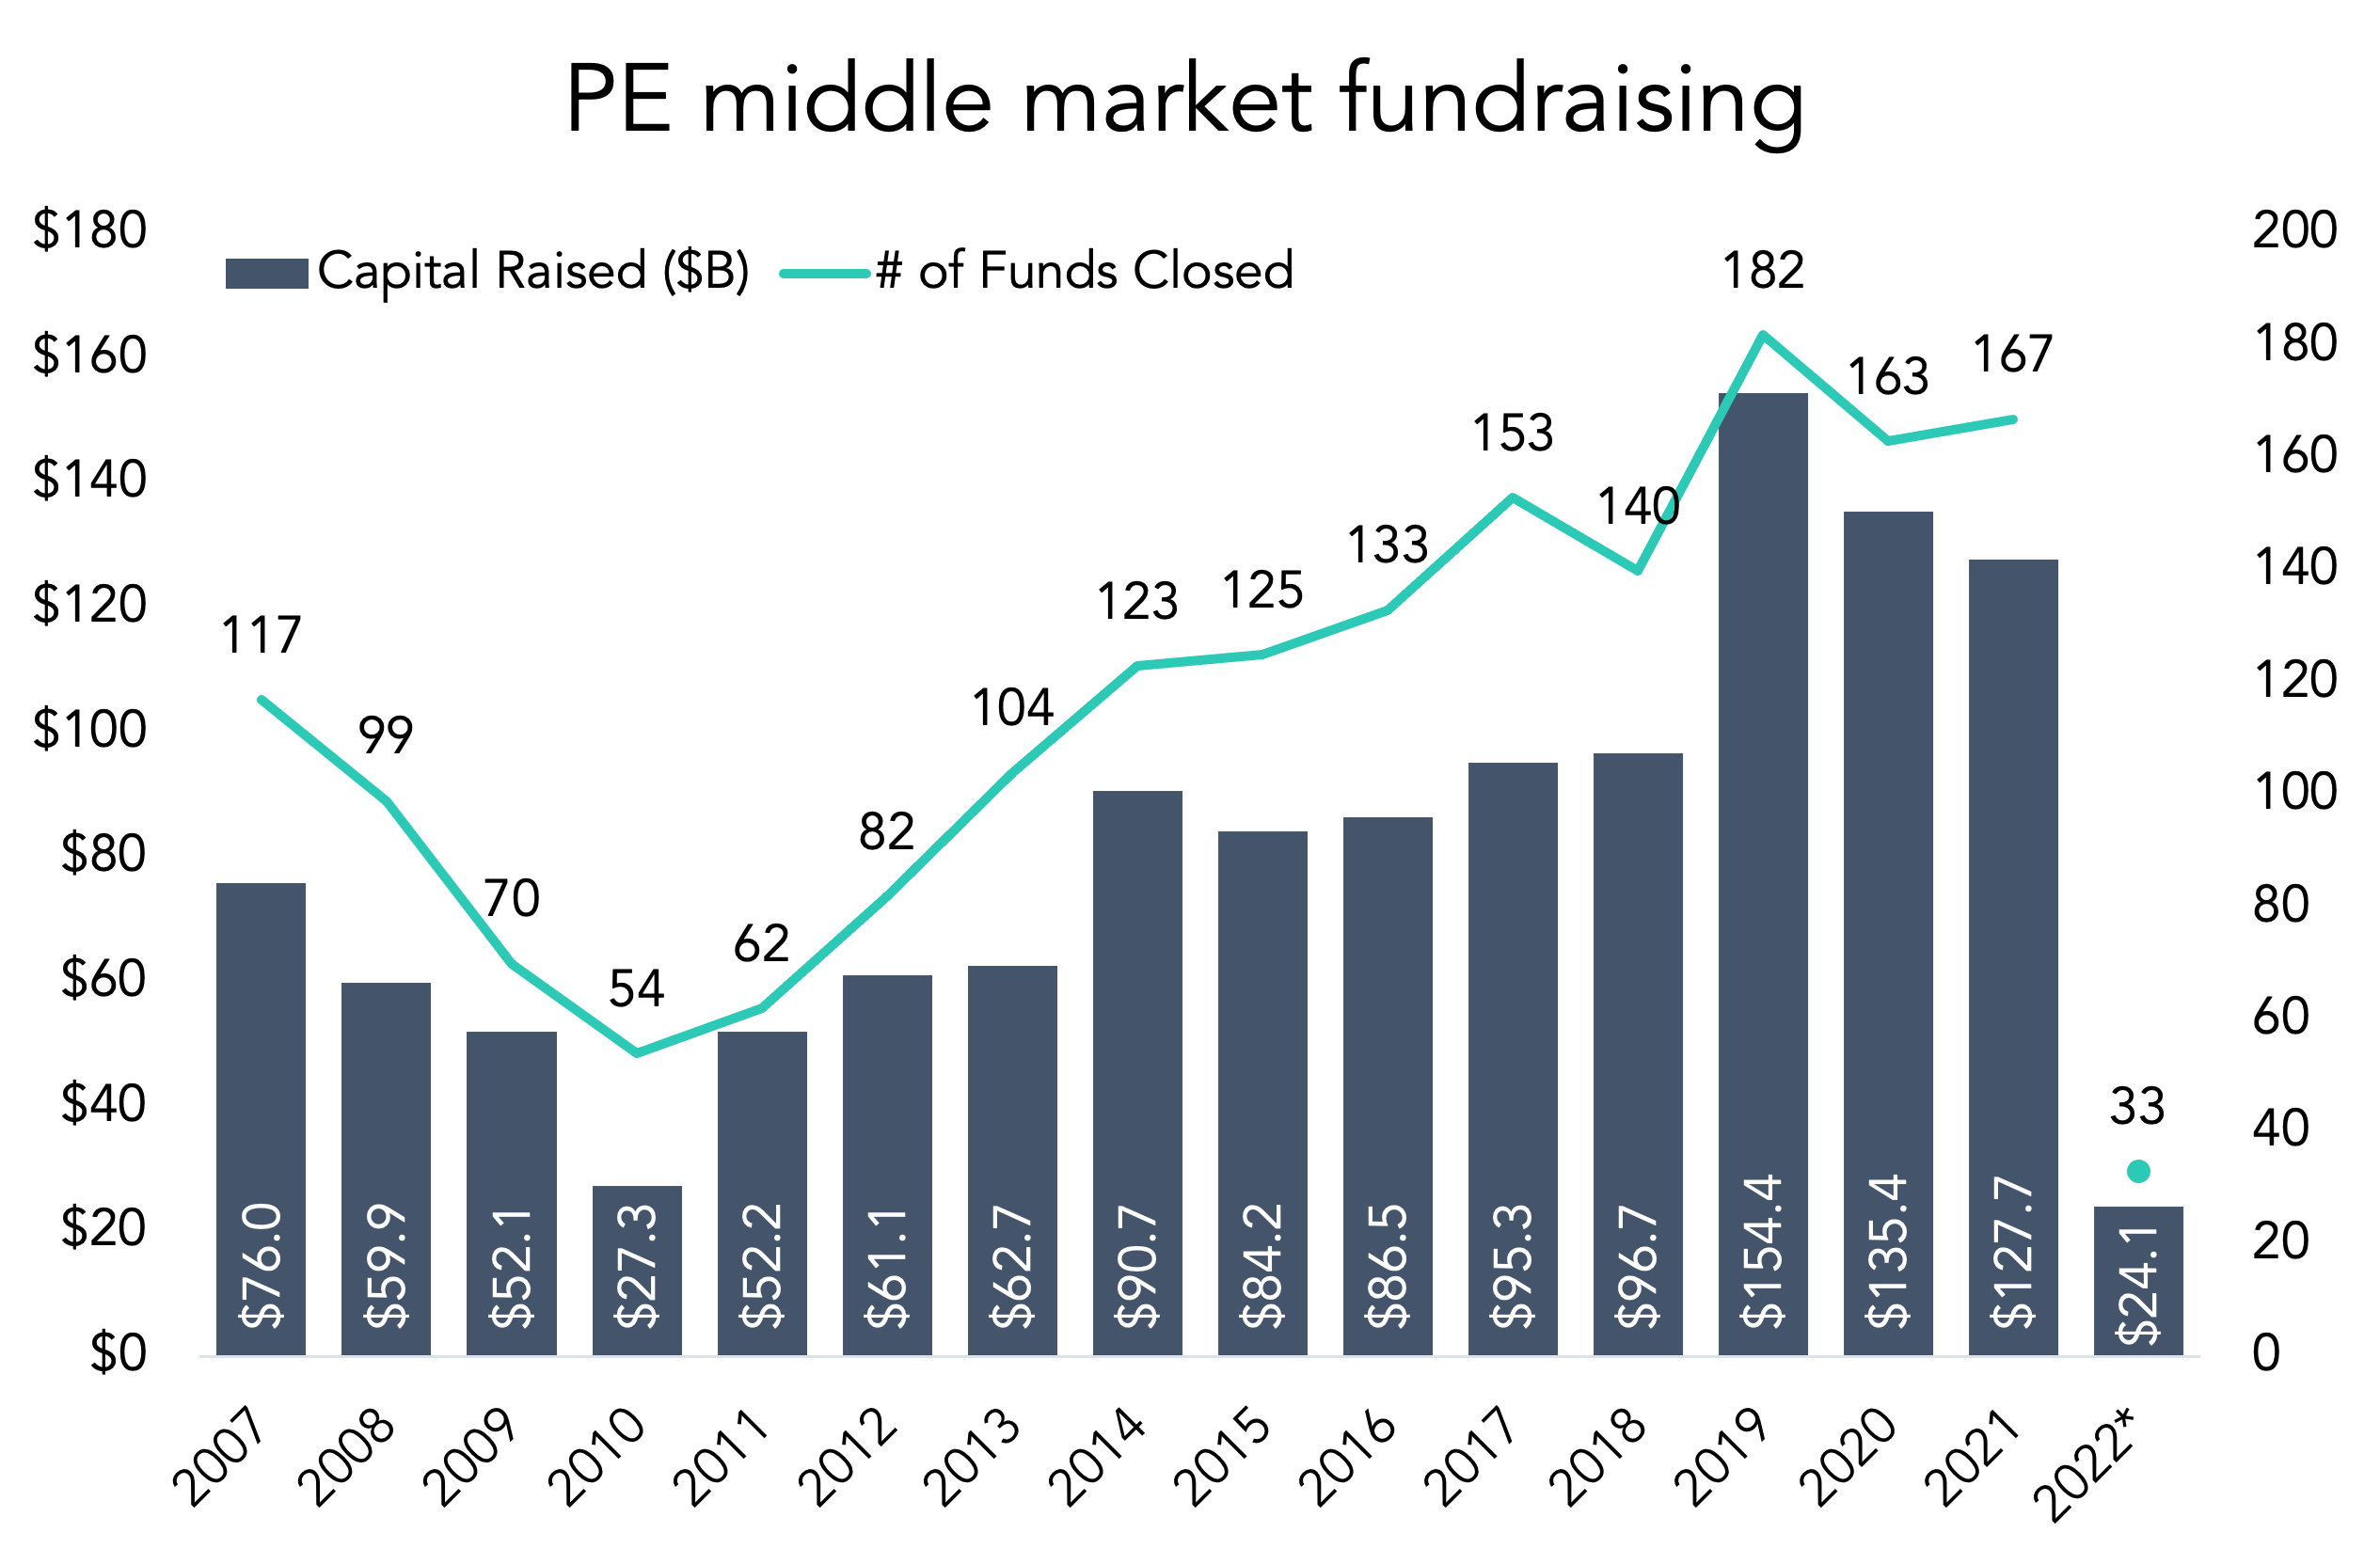
PitchBook’s latest US PE Middle Market Report is now out. Many of the overall deal trends mirror those of the broader PE market. One standout figure was early 2022 fundraising, which is off to a slow start. Only 33 middle-market funds closed in Q1, a visibly slower pace than the past three years. Middle-market dry powder levels fell by just 6.5% between 2020-2021 versus a 12.3% drop across the entire PE industry. About $423.1 billion was at the ready as of Q4 2021.
LPs are trying to maintain balance in a volatile market while hearing pitches from GPs. The denominator effect isn’t having a universal impact right now, but it is popping up in places. The Alaska Permanent Fund, one of the biggest LPs in the country, is reducing its PE allocation by 25% for the upcoming fiscal year, citing the denominator effect. Other LPs are prioritizing their existing GP relationships, especially the biggest ones, while keeping an open mind on smaller, niche GPs. PitchBook analysts think that dynamic will be a headwind for middle market fundraising, prompting sponsors to dedicate more time to raising money or delaying fund closes. There are anecdotes of even top-quartile managers having a hard time getting on the calendars of LP investment committees. “Challenging but not impossible” is the theme for now.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
