


Download PitchBook’s Report here.
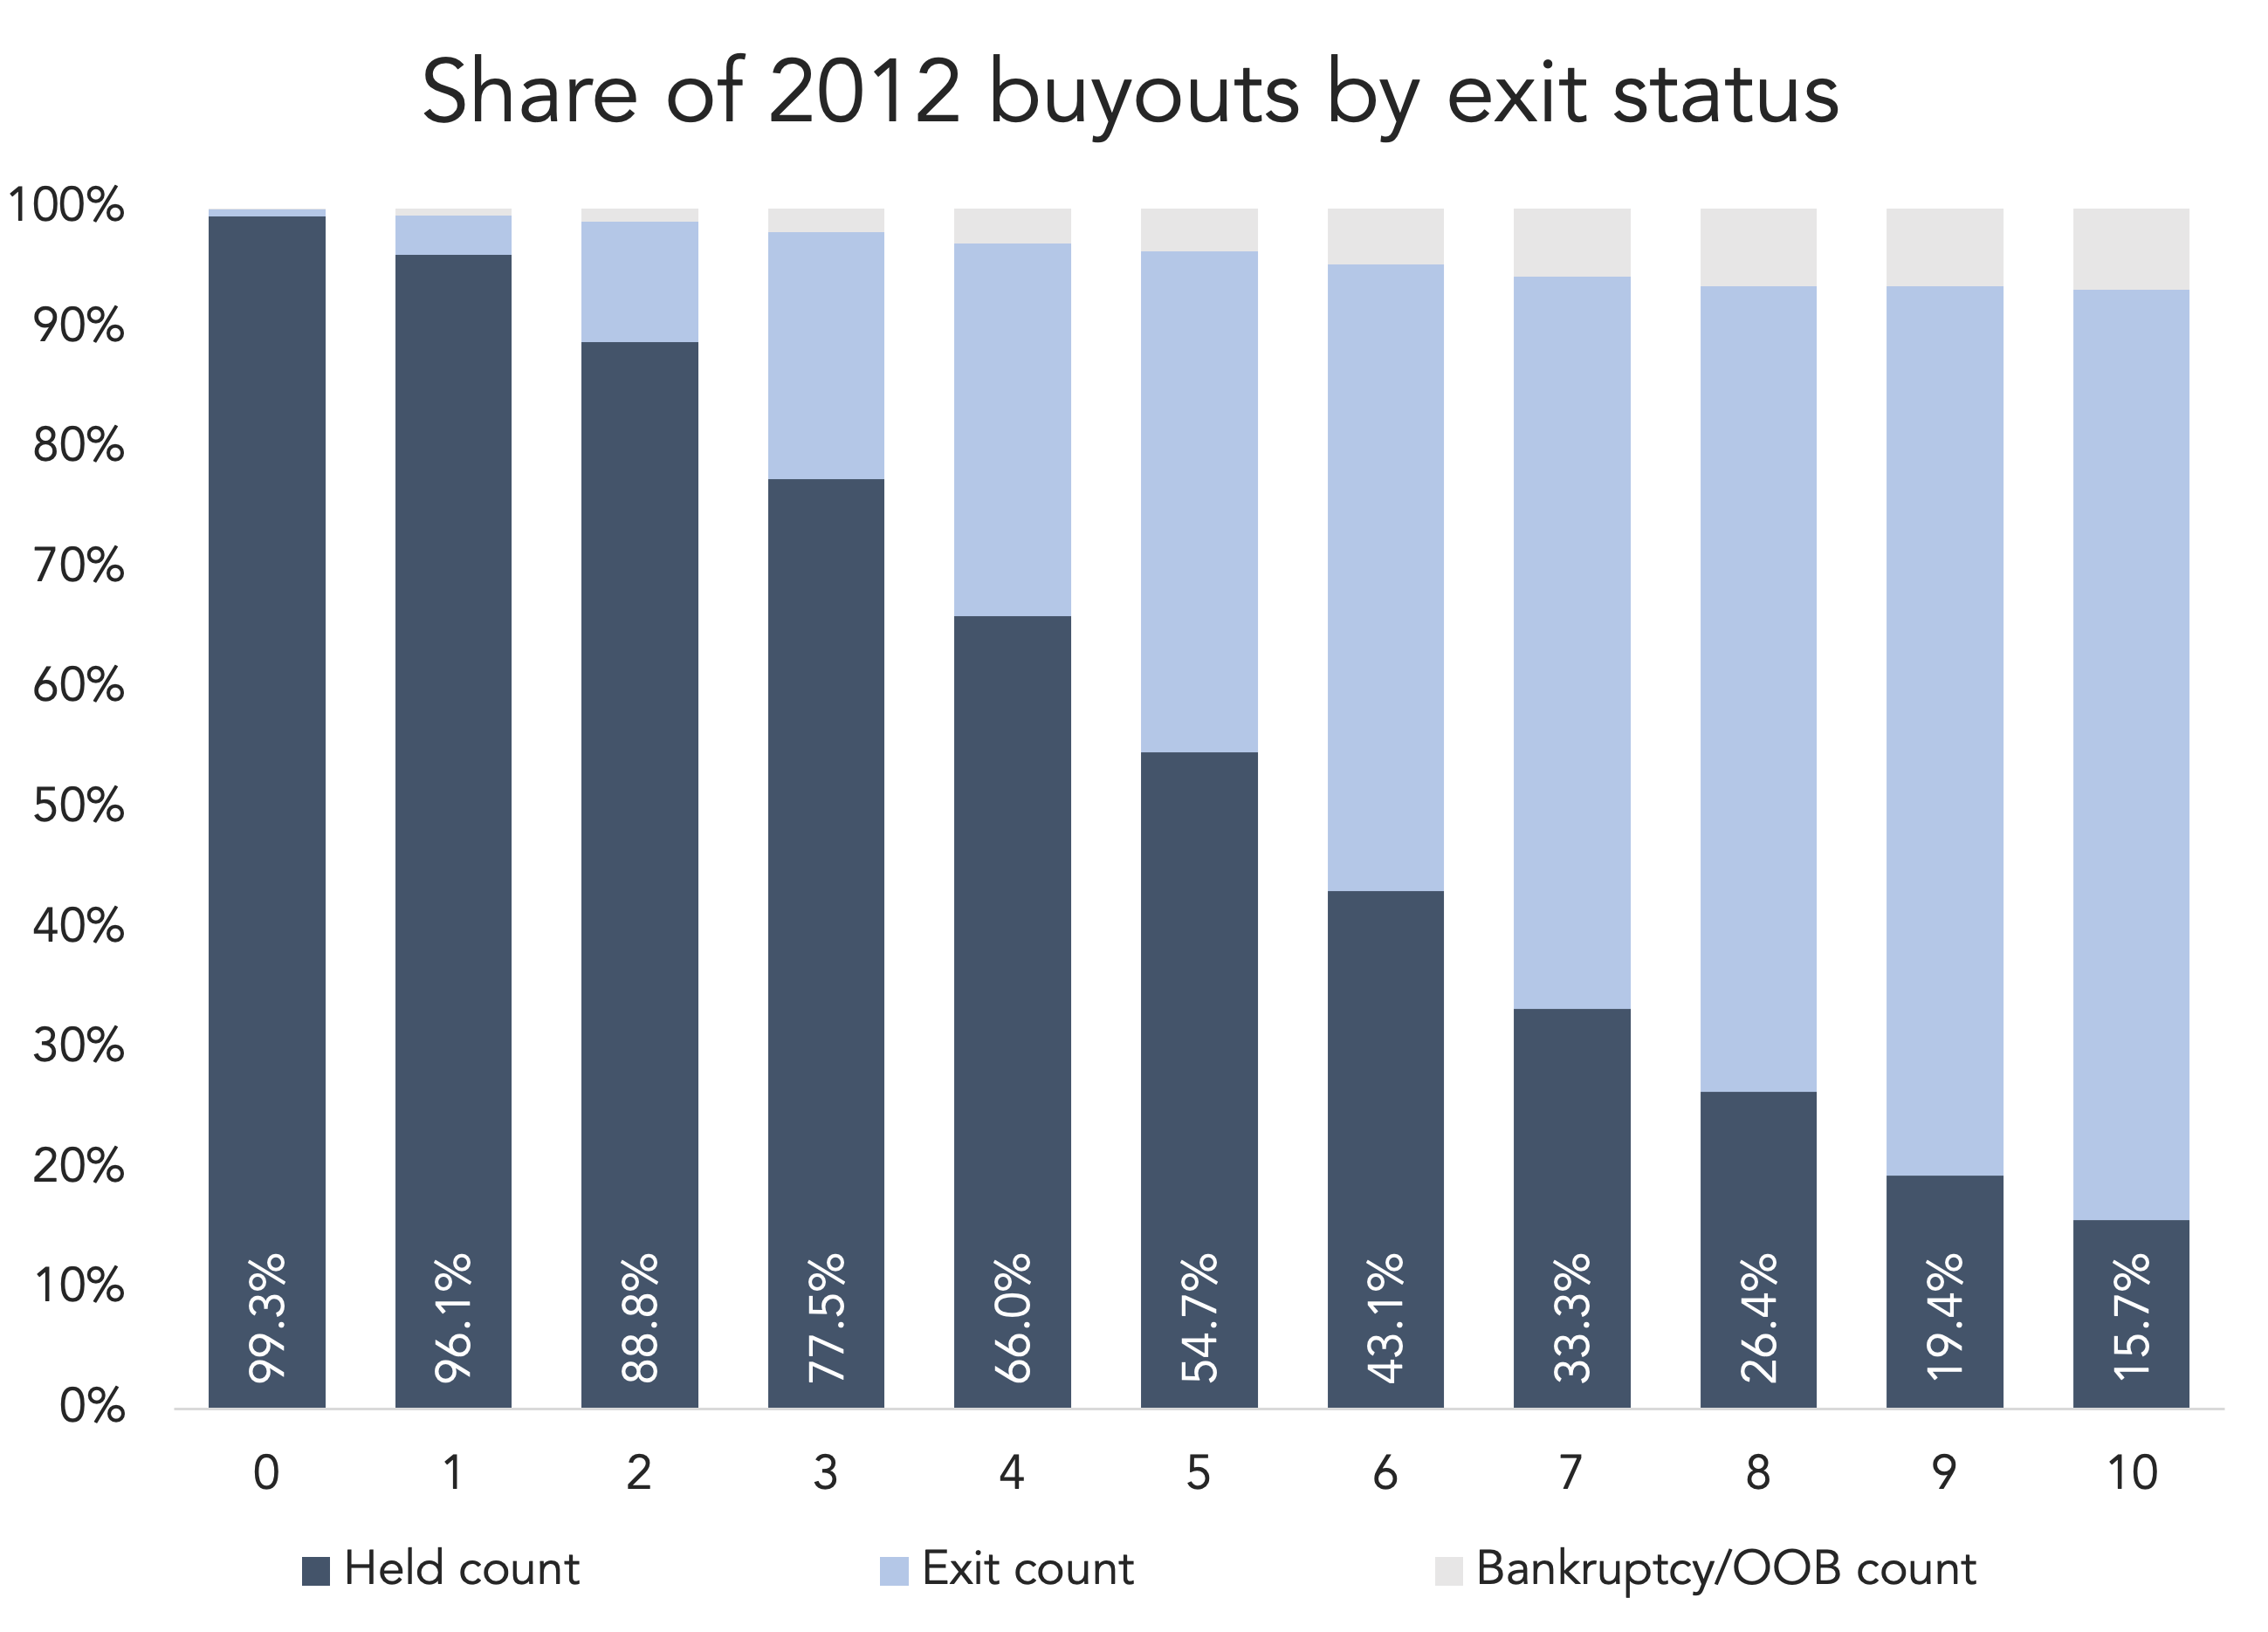
Private equity’s stunted exit market is now several quarters old, and it comes on the heels of a historic run of deal activity. A new PitchBook analyst note looks ahead to an “impending maturity wall” and the ripple effects it could have on the industry. If exit paces don’t pick up to more historical standards, upwards of 26% of capital invested will hit a maturity wall—a 10-year holding period in this case. 26% is a comparably high percentage; for 2012 investments, 15.7% of capital invested was still held after ten years. In a hypothetical extrapolation, the combined value of all those portfolio companies could eclipse $360 billion over the next 12 years.
It’s a far way out, but it’s safe to predict an increase in continuation funds if all this plays out. Continuation funds have already emerged as a tool for GPs, though LPs have expressed frustration with them. Even in healthy years, there are situations where companies need to be held longer than expected. It’s possible that many more of them will be needed in the years ahead, alongside more secondary sales and NAV lending, if sponsors want to avoid becoming forced sellers.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
