



Download PitchBook’s Report here.
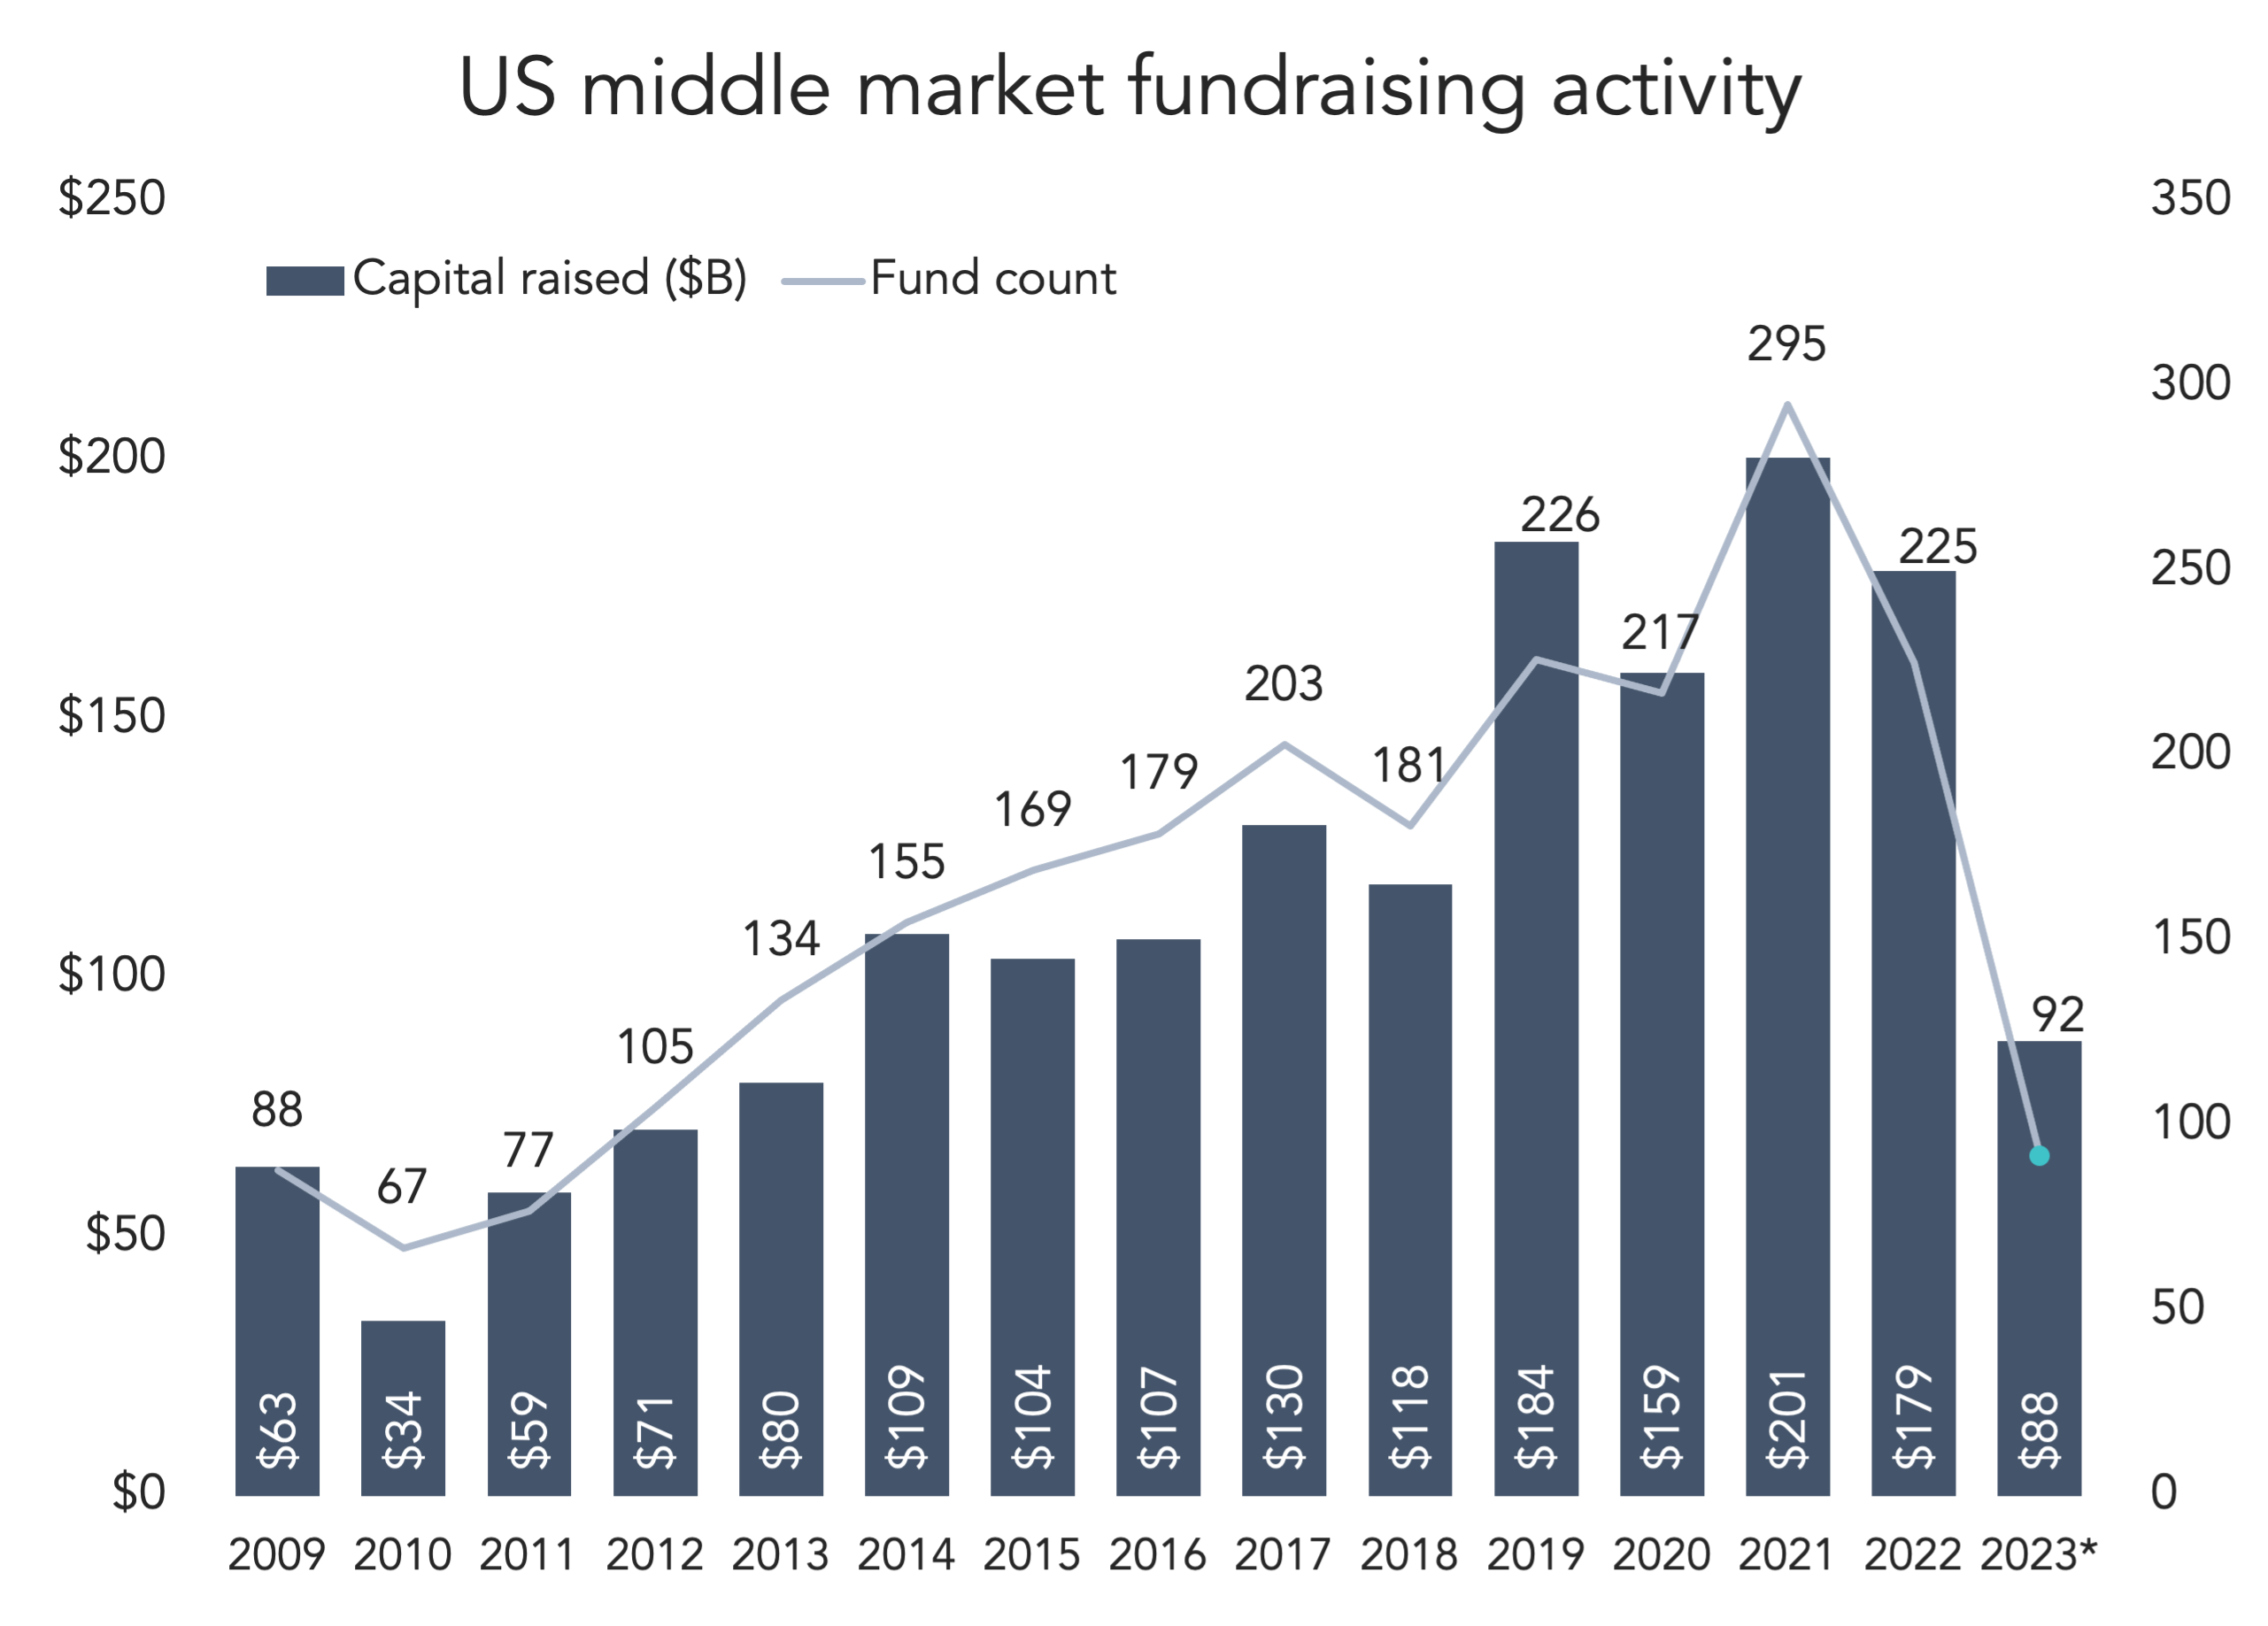
Last week we mentioned the overall fundraising slowdown, which was highlighted in PitchBook’s US PE Breakdown. Much of that is due to fewer mega fund closings. Many are still on the market, but firms like Blackstone, TPG and Carlyle have acknowledged their latest flagships will be smaller than anticipated. Middle-market funds, on the other hand, are on a good run, and they’re outpacing their bigger counterparts in both fundraising and performance. At the halfway point, the middle market has seen 92 funds close worth a combined $88 billion. Those figures are in line with four consecutive years of strong fundraising.
The same dynamics that are stymying bigger transactions—debt financing being the biggest—are providing a tailwind to smaller deals and, by extension, smaller funds. Valuations are more palatable in the middle market, which makes it easier to finance them without significant borrowing costs. Middle-market funds are also likelier to invest in companies that haven’t been touched by private equity before. That makes a difference for both the companies (some of which can’t wait out the economic downturn) and the investors (who can invest at lower entry points and closer to a turn in the business cycle). Middle-market fundraising has several things going for it at the moment, and we can expect to see relative strength for smaller funds, regardless of what happens at the higher end.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
