Download PitchBook’s Report here.
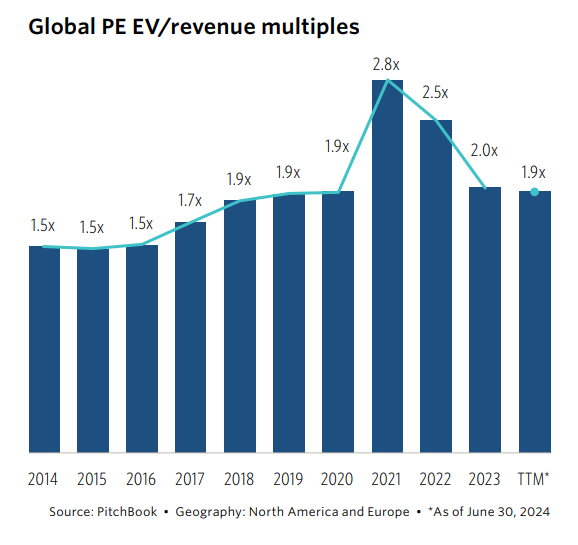
Revenue multiples saw a much more aggressive run-up to the peak reached in 2021 and a much faster descent thereafter. In Q1 2024, we saw initial signs of distressed selling and capitulation. EV/revenue multiples lurched downward to 1.4x from a median TTM of 2.0x at the beginning of the quarter. We normally do not extrapolate three-month trends in multiples given the volatility of the data, and we were keen to see evidence of any follow-through in Q2. The snapback in Q2 multiples to a median of 1.9x indicates that the storm may have passed for now, and we suspect it reflects the breathing room gained from lower borrowing costs and the halo effect from strong public markets.
(Past performance is no guarantee of future results.)


Latest news

US leveraged loan issuance stalls in October amid secondary market rout
US leveraged loan issuance took a significant hit in October amid deteriorating secondary market conditions. Approximately $41.3b of loans have…