


Download PitchBook’s Report here.
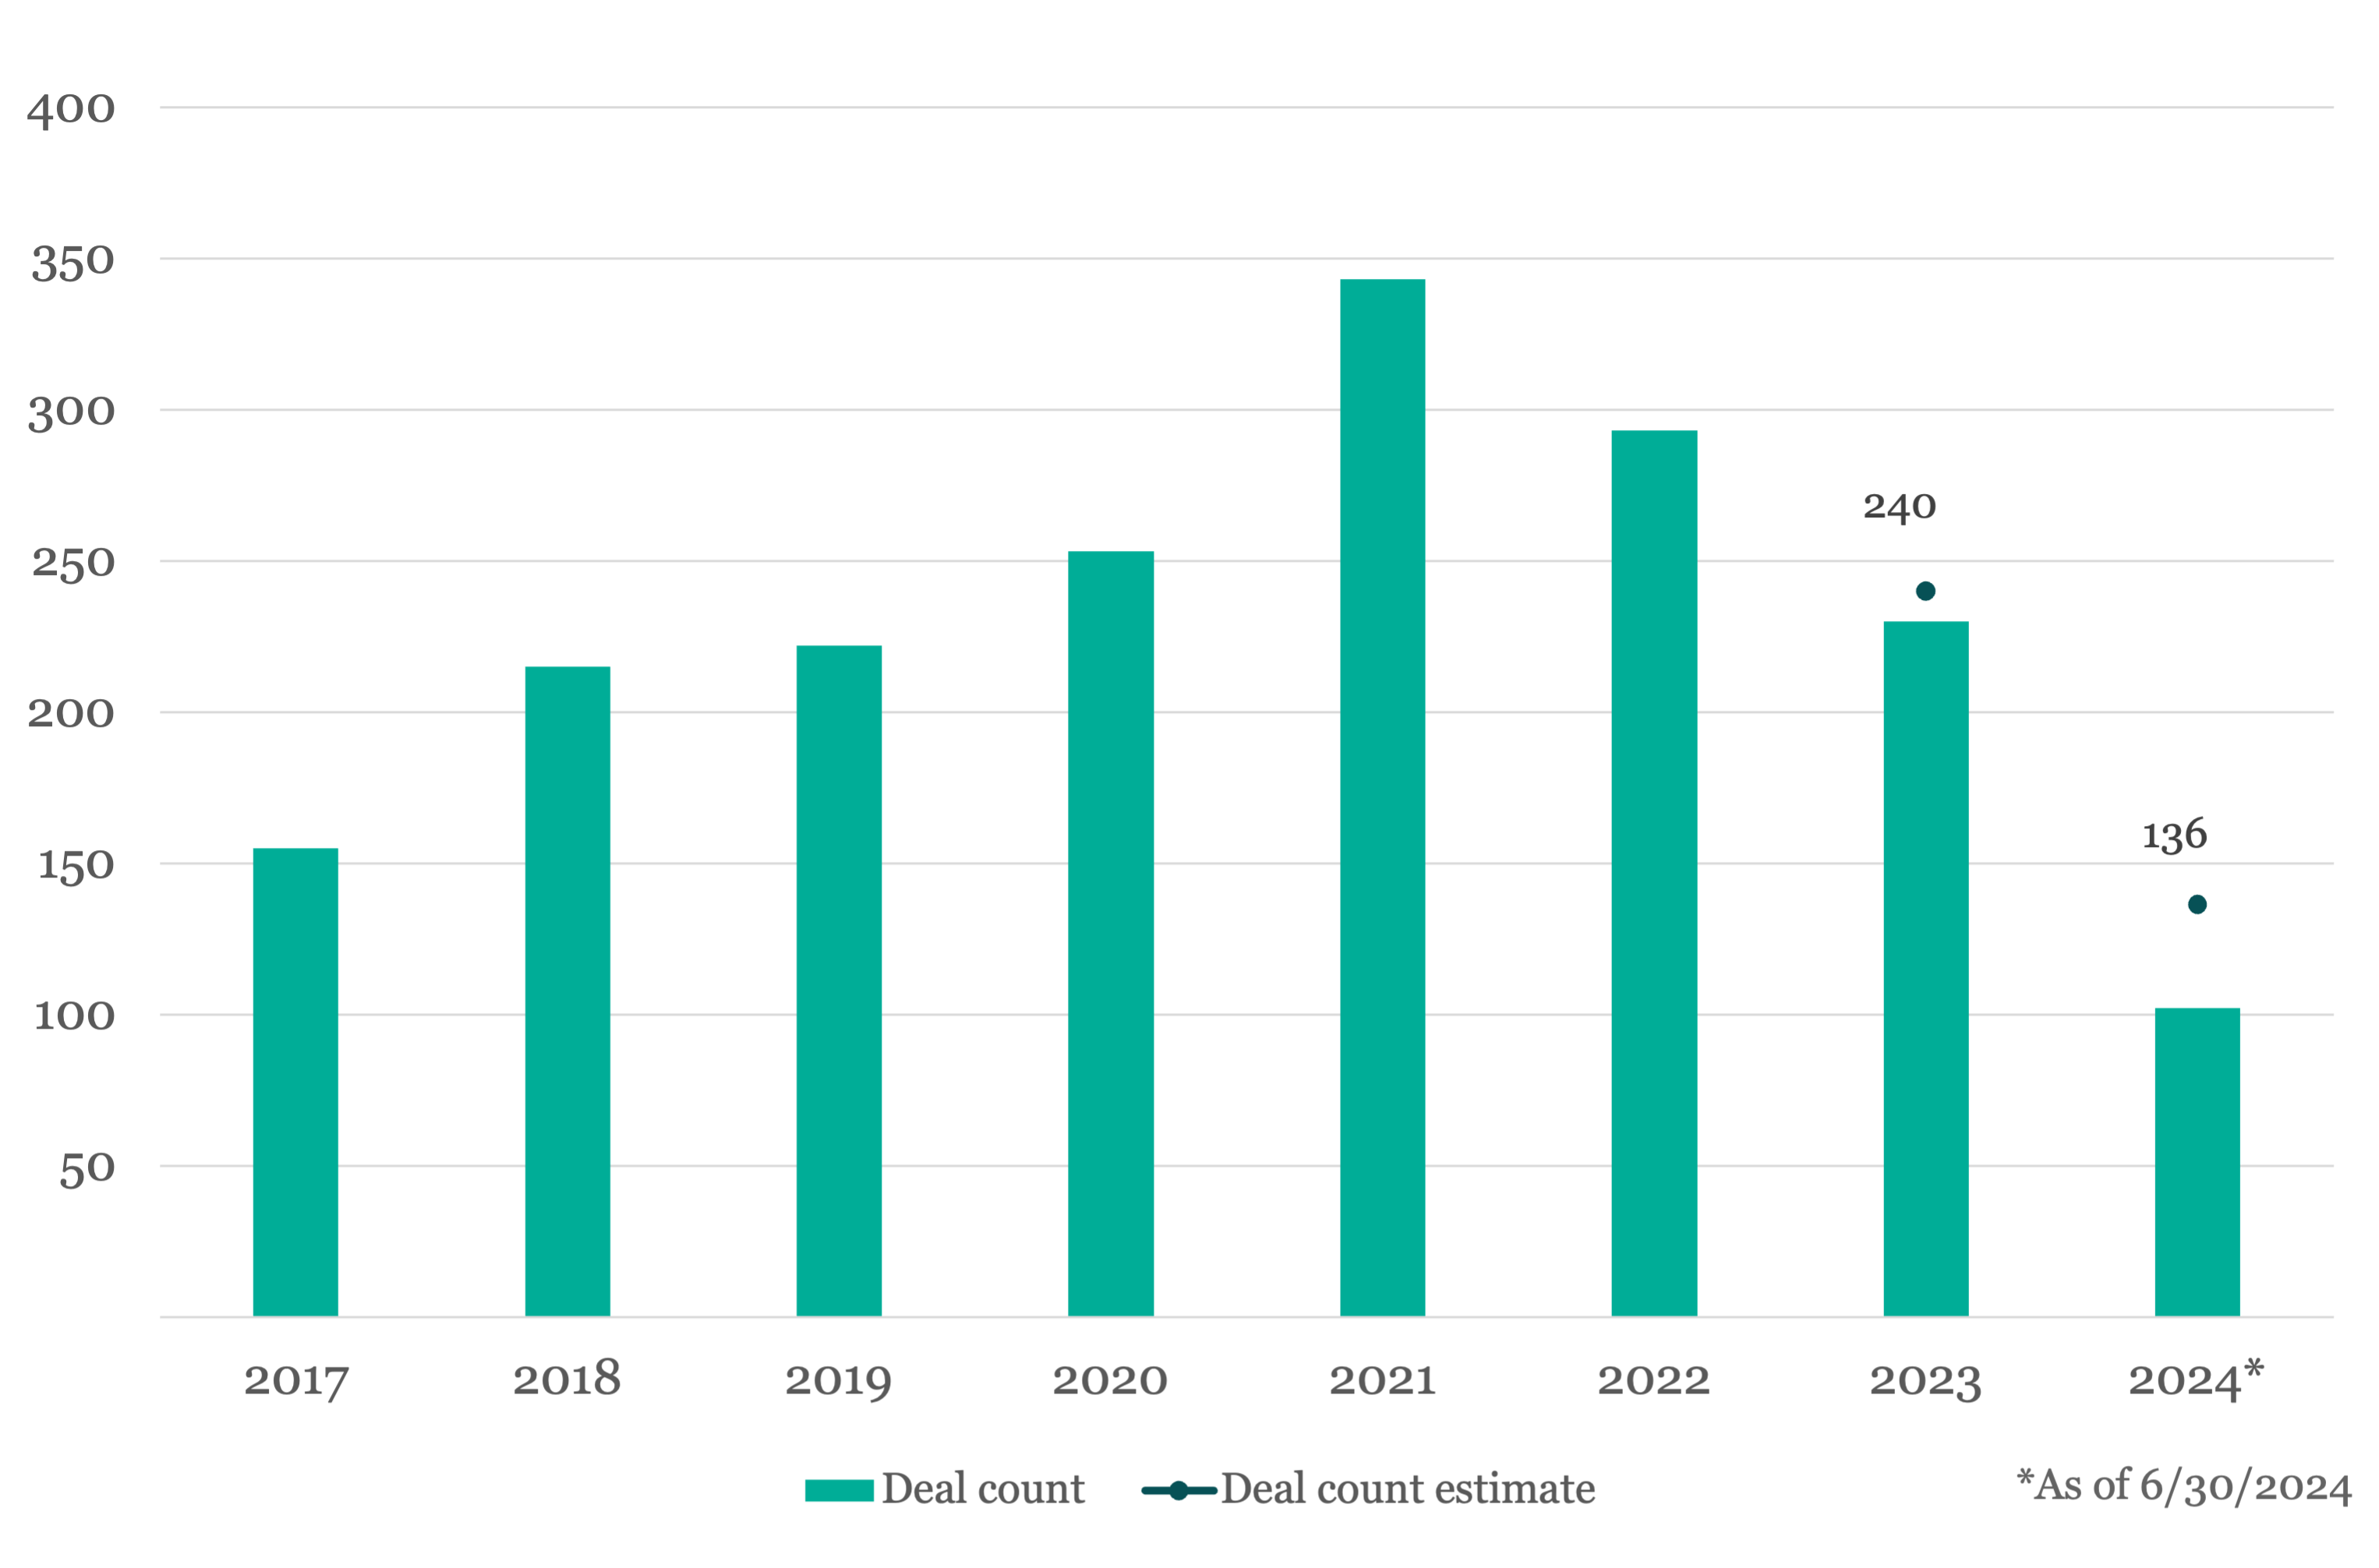
In the lower middle market, we are beginning to see more examples of a phenomenon we have anticipated for a while: PE firms and PE-backed companies acquiring VC-backed startups. Lower-middle-market PE firms perennially complain that VC-backed companies expect too-high multiples, and these firms would generally prefer to invest on a multiple of EBITDA rather than a multiple of revenue. However, we expect a greater convergence of the two asset classes over the next few years.These deals will generally take two forms: PE acquisitions of larger, profitable or nearly profitable VC-backed companies that have seen the writing on the wall and started to prioritize margin over growth; and PE-backed tuck-ins of smaller VC-backed companies that have run out of runway and sell at a discount to their previous valuation but can deliver a useful technology enhancement to a PE-backed platform.
(Past performance is no guarantee of future results.)



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
