



Download PitchBook’s Report here.
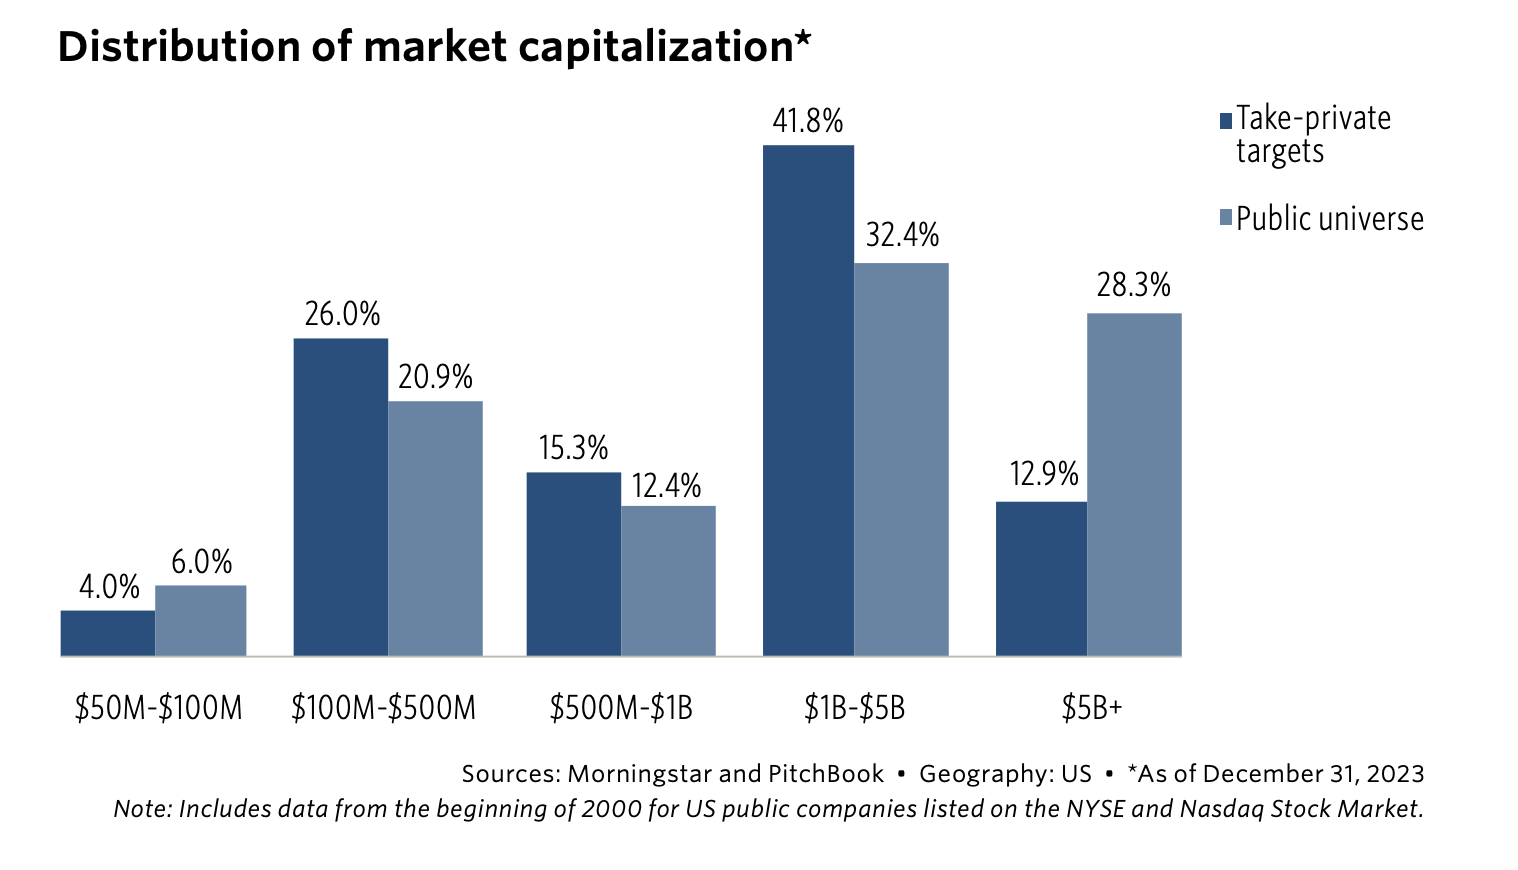
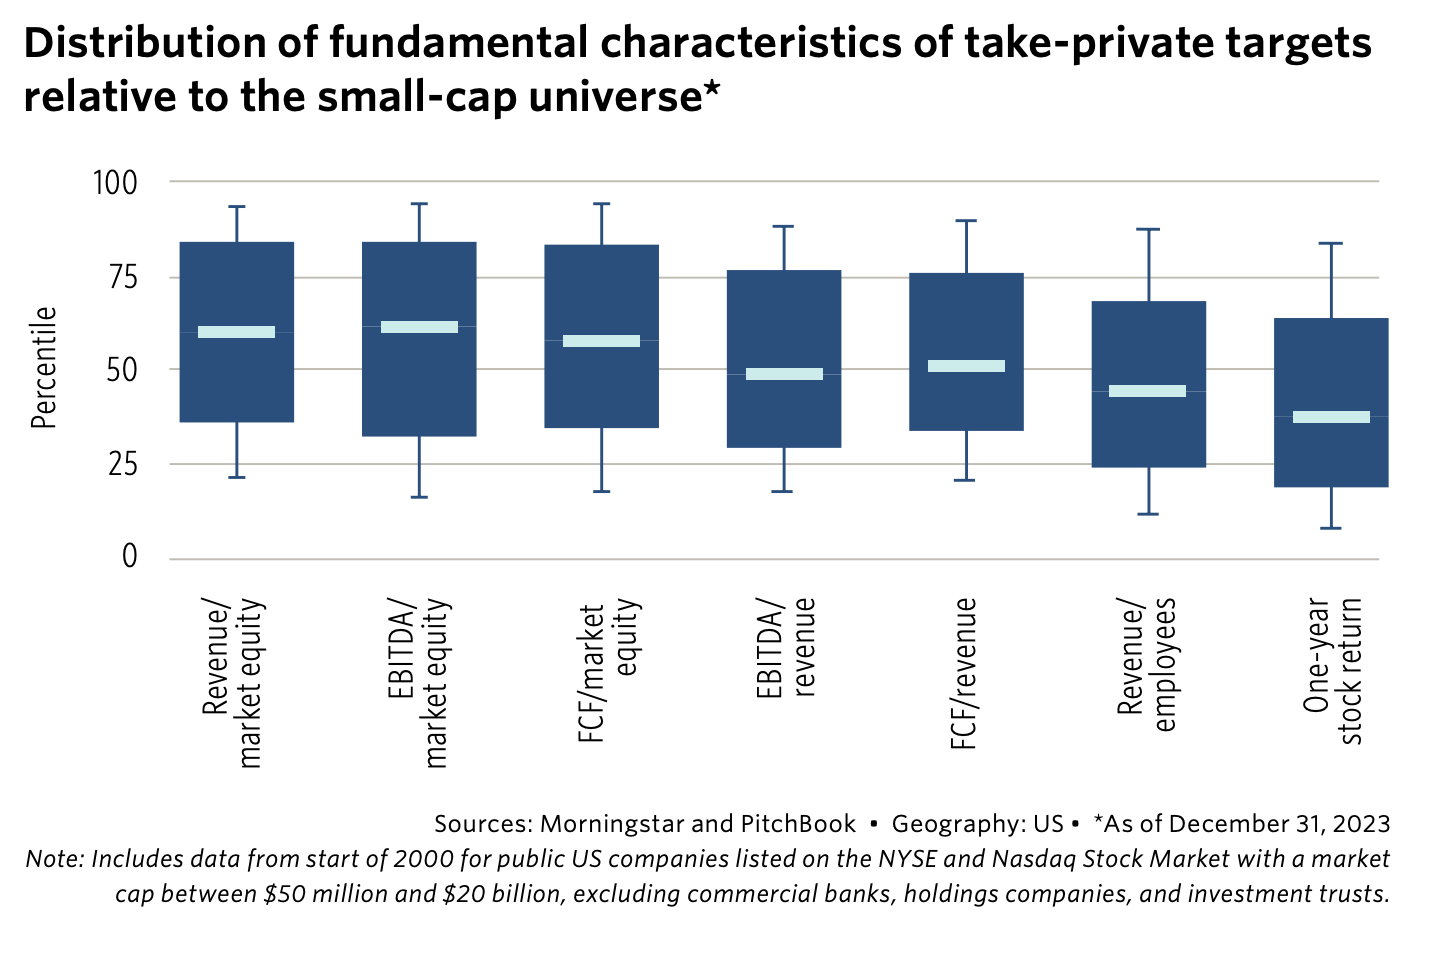
Since the inception of the strategy in the 1980s, buyout managers have maintained a core playbook: Invest in relatively small, underperforming companies at a reasonable price that still generate enough free cash flow (FCF) to service an increased debt burden. Evidence from take-private transactions over the past 30 years confirms this playbook is being used. We found that take-private targets are more likely to be relatively cheap with respect to a variety of equity price ratios despite relatively neutral EBITDA and cash flows margins. Underperformance is apparent in both the trailing one-year stock return as well as operating efficiency in terms of revenue generated per employee.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
