


Managers could face 16% increase in cash-flow challenged issuers next year
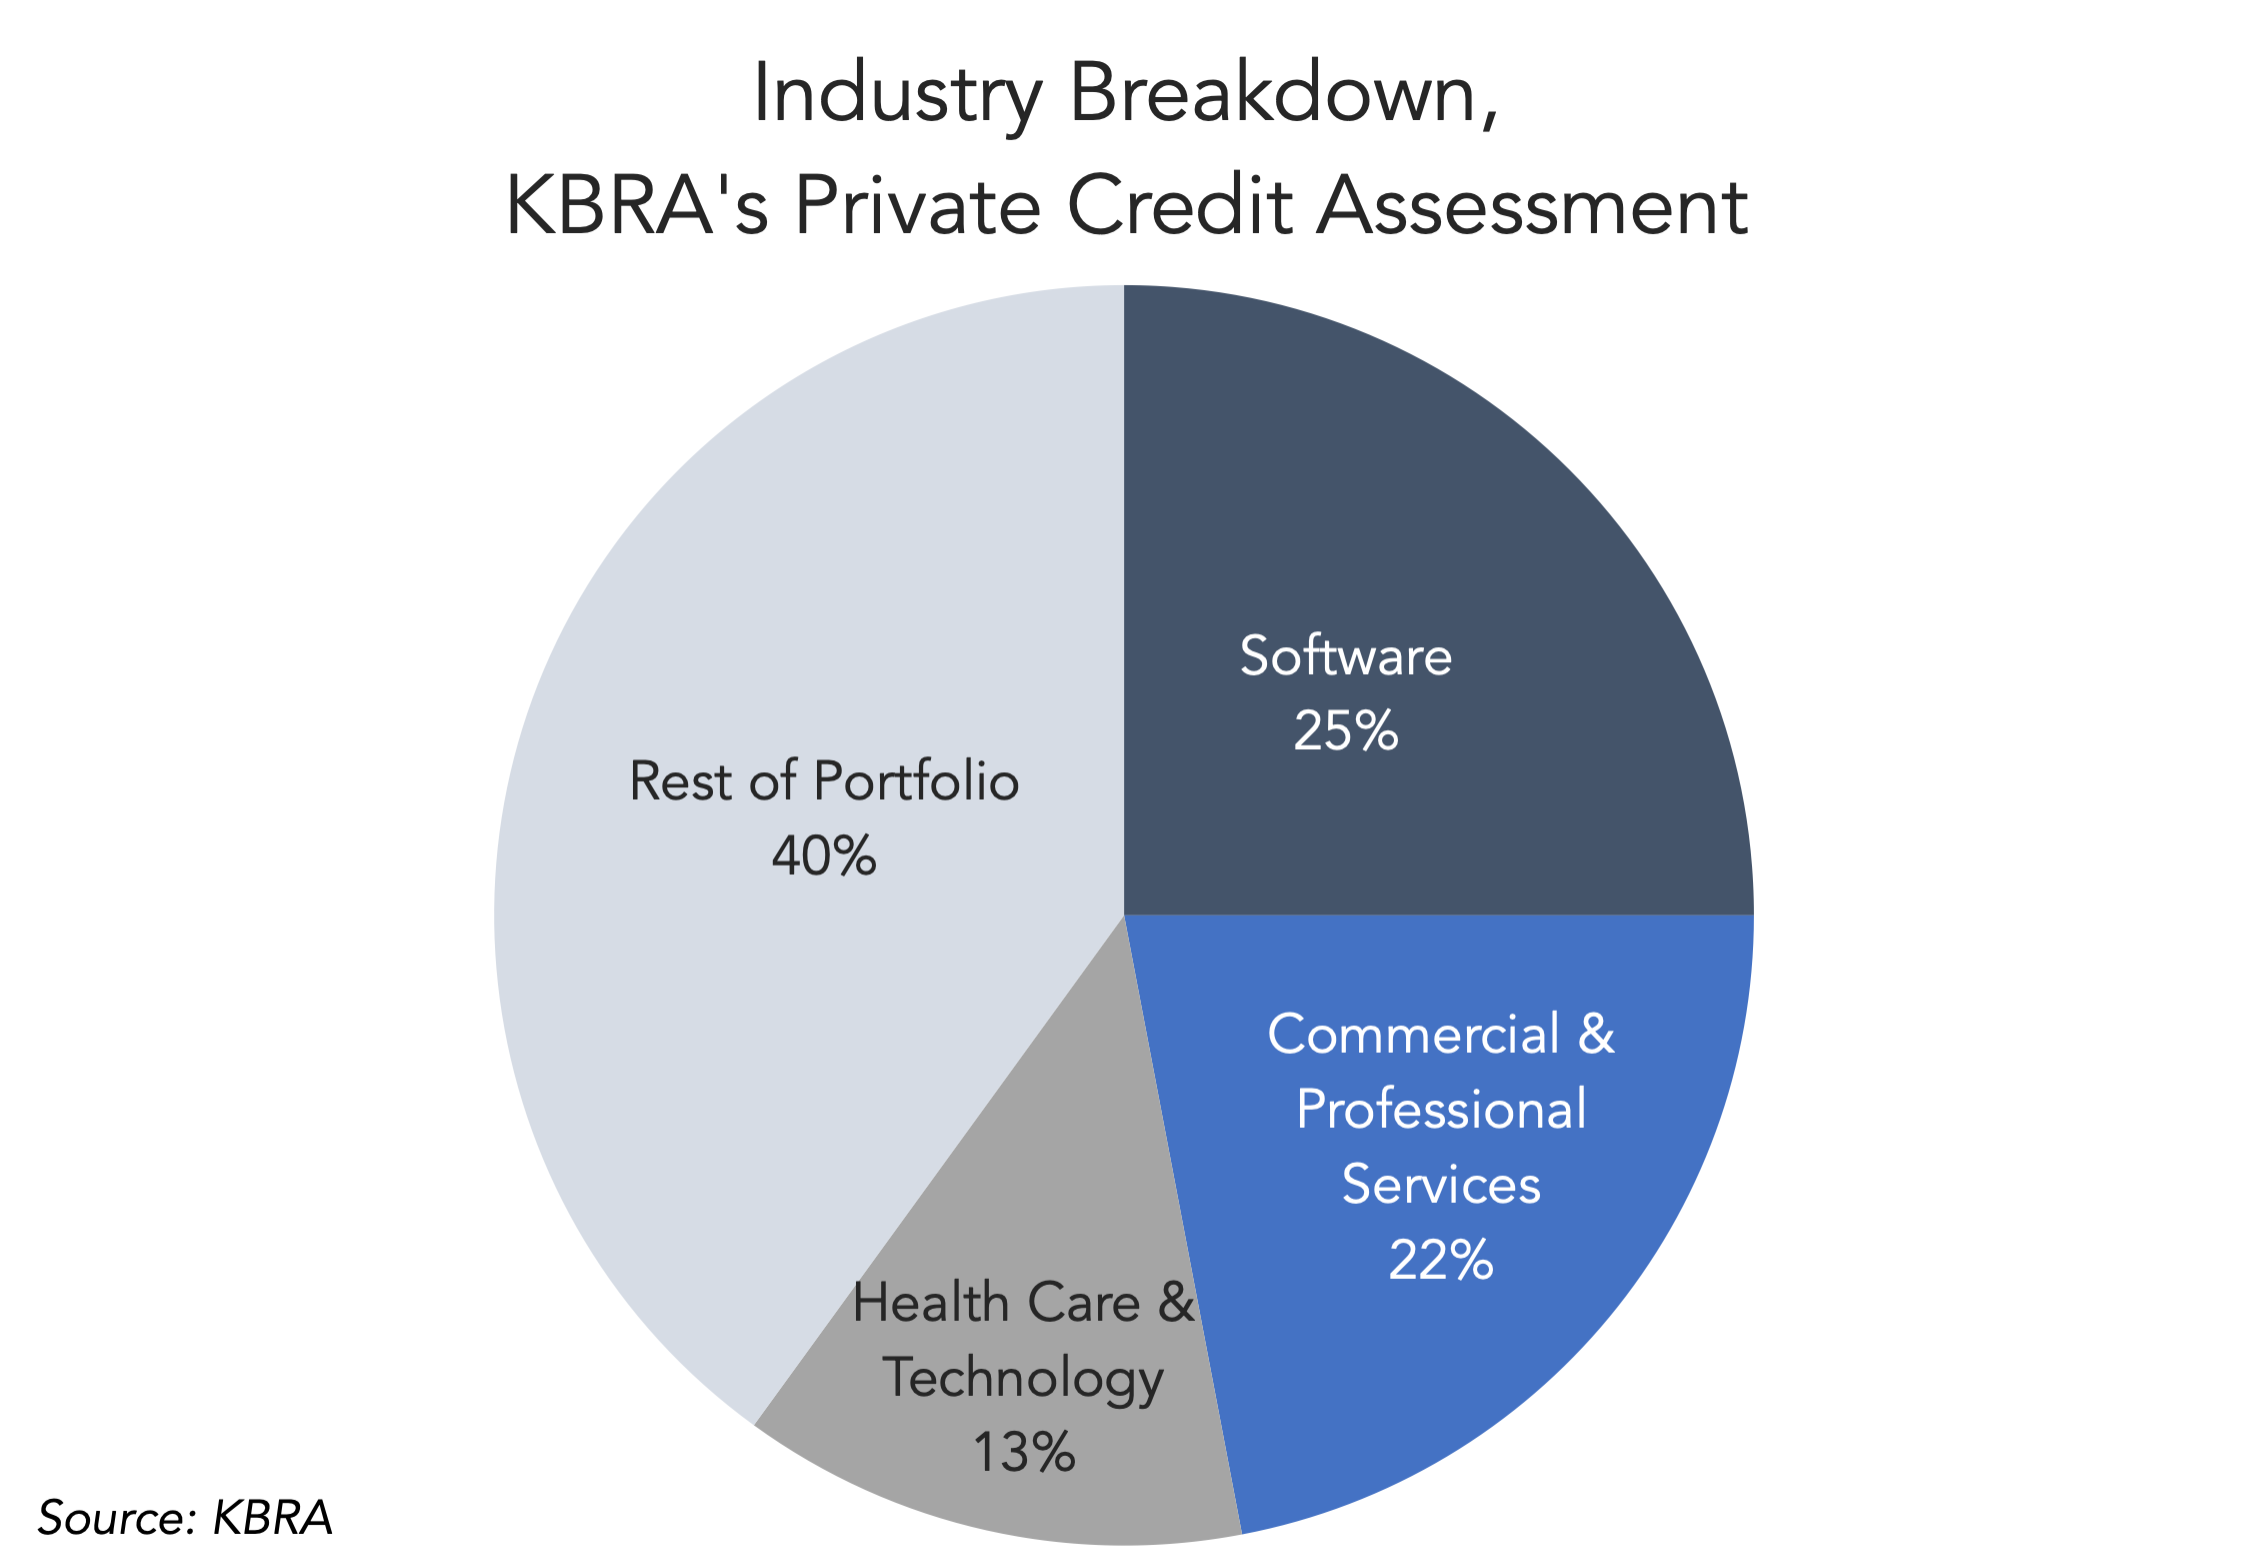
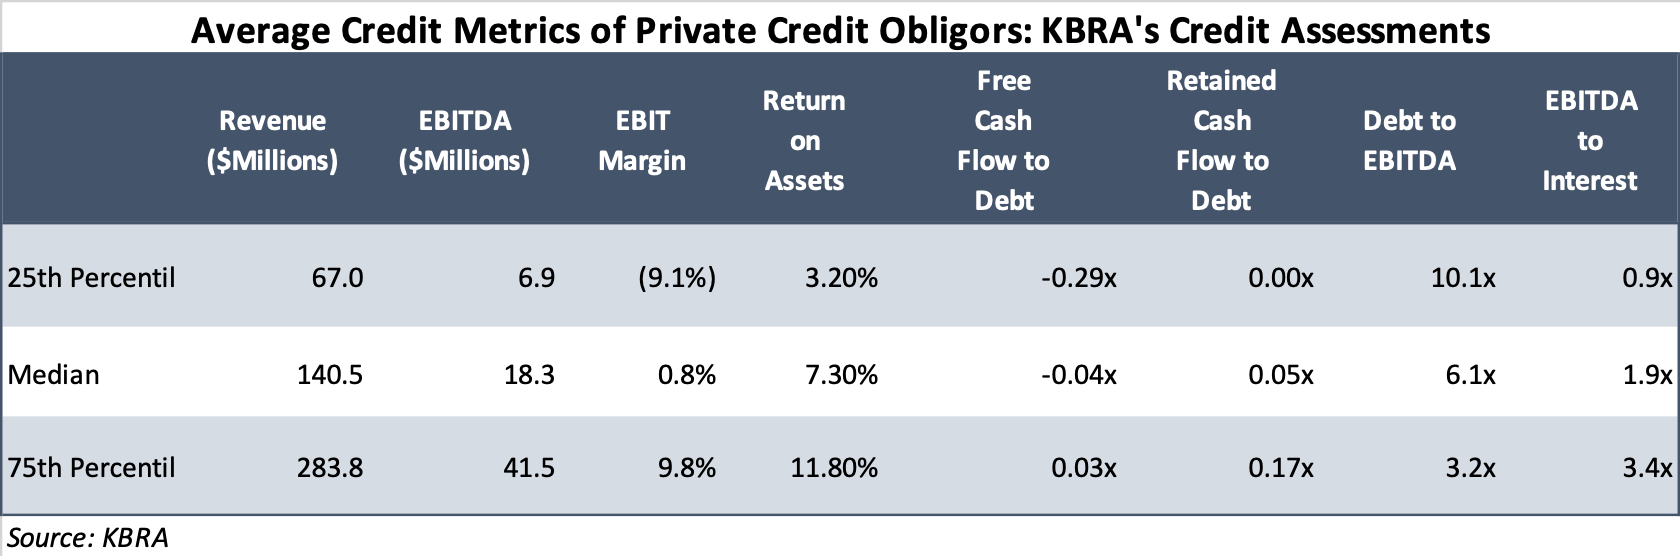
Portfolio managers are potentially facing a 16% rise in the number of borrowers that cannot generate enough cash flow to meet interest expenses by the end of 2023, based on an analysis by KBRA DLD’s new parent, Kroll Bond Rating Agency (KBRA).
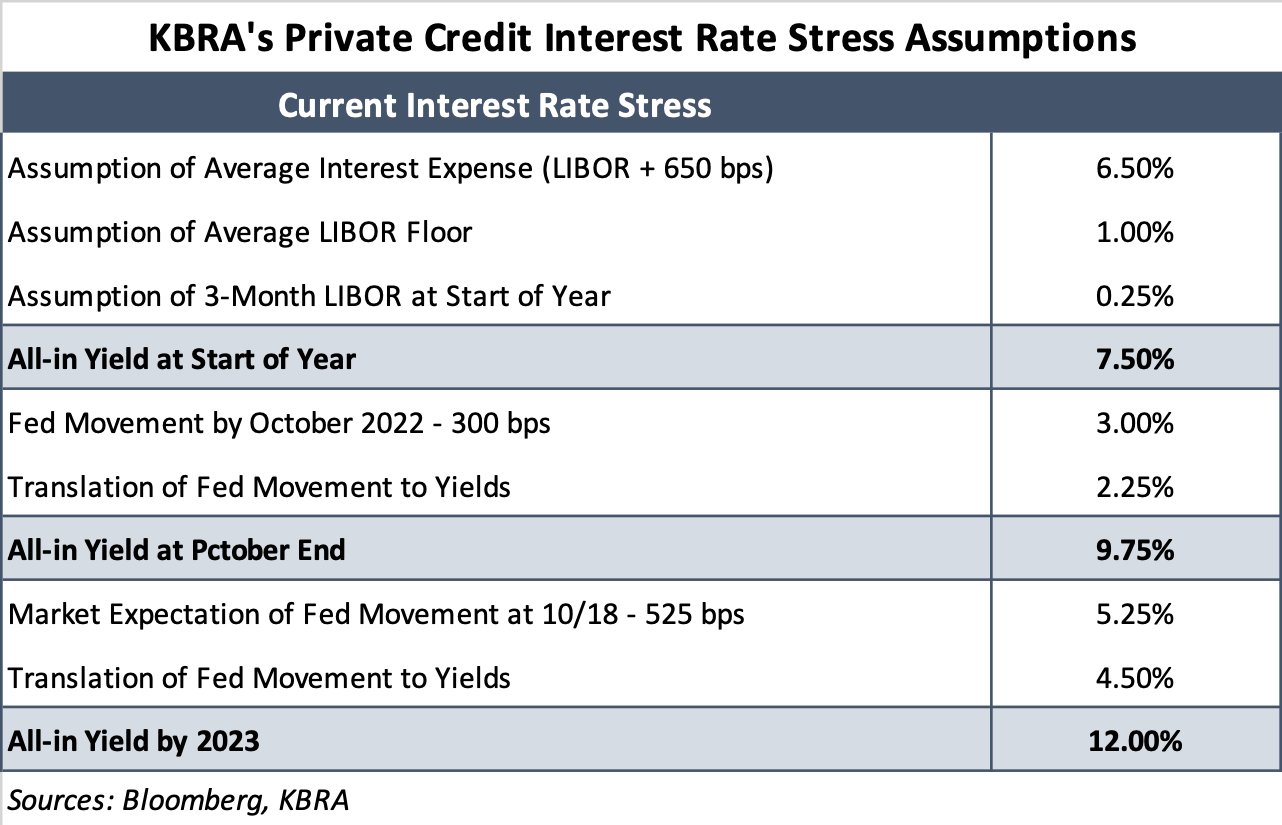
The analysis dissects a portfolio of roughly 2,000 direct lending loans that have been privately assessed by KBRA (not DLD). The 16% increase assumes 12% debt costs by 2Q 2023, based on widely anticipated Fed rate hikes.
At the start of the year, average borrowing costs for the KBRA portfolio were 7.5%, and 27% were underwritten with the expectation they would not cover interest payments through operating cash flow and were using other sources of liquidity to meet obligations, such as cash on hand or equity raises. But that cohort has likely grown to 34% of the portfolio as of this month, as the average yield has increased to 9.75%. By the middle of next year, 43% could fall into this group, on 12% interest.
As noted by KBRA, there are factors excluded from the analysis that could pull these numbers in either direction: 1) recessionary pressure on revenue, 2) inflationary pressure on expenses 3) interest rate hedges. On the last factor, KBRA says that up to 50% of private credit borrowers may have some hedges in place, although the degree to which they are hedged and the level of protection provided are uncertain.
How the market with deal with rising rates will differ from the remedies applied during the Covid pandemic. KBRA predicts that the standard “amend and extend” and equity infusions may be insufficient if higher rates simply mean that borrowers find their interest unaffordable.
Lenders, sponsors, and borrowers will have to work to either reduce the spread or the company’s leverage relative to its newer valuation. KBRA also suggests that lenders are likely already enhancing their credit monitoring process by building robust early detection systems to find those companies that will be most exposed to higher interest rates and develop customized restructuring solutions that may be needed to address the borrower’s capital structure.
The resolution of lower leverage may come at the expense of equity holders, and so lenders may need to make difficult choices, such as the trade-off between harvesting the returns from rising variable interest charges or managing their portfolio toward more workouts and restructuring activities at the expense of their relationship with equity sponsors, according to KBRA.


Why Capital Solutions: The Walking Debt
The word “zombie” traces to Haitian folklore and entered the English language in the early 1800s.