


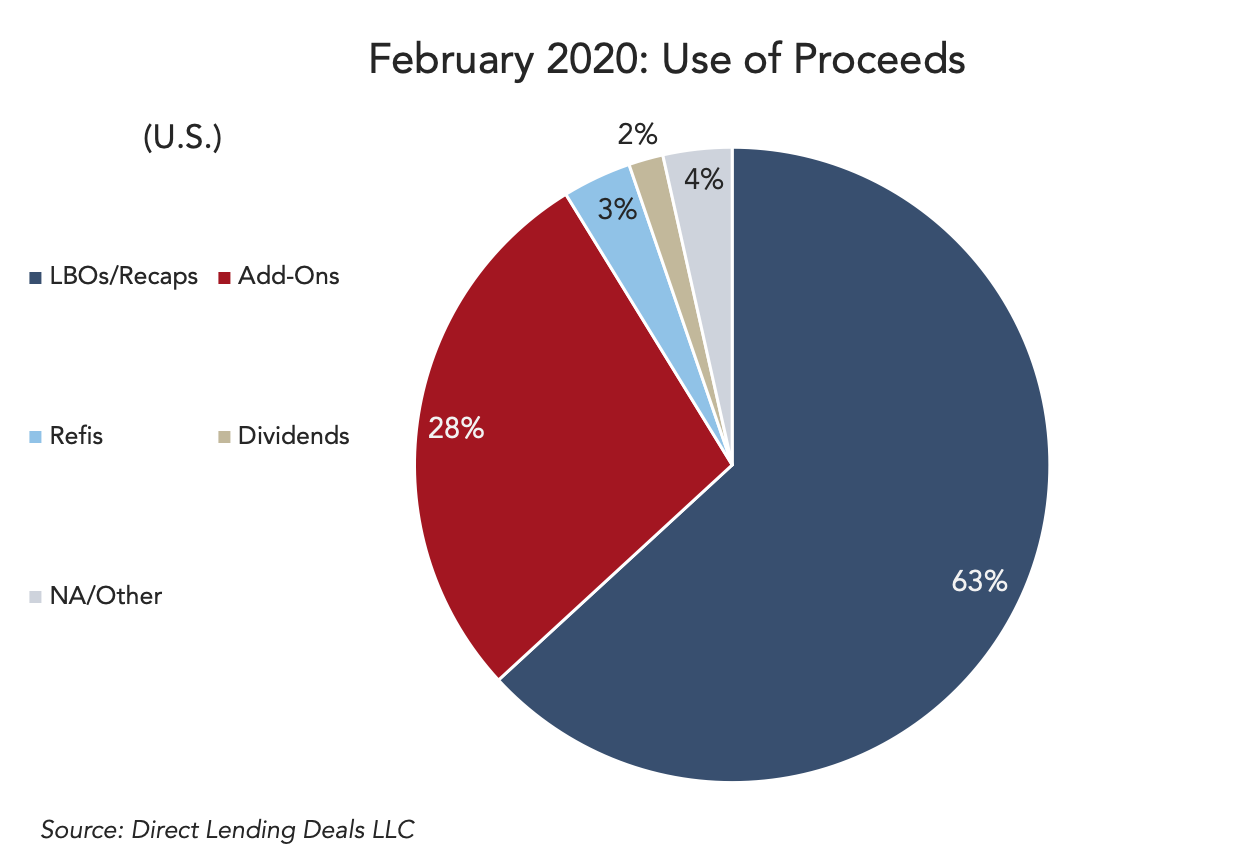
February’s tally of direct lending loans softened to 57, from 73 in January, according to Direct Lending Deals. The decreased flow was mainly due to slower-than-expected M&A — all deals were baked before coronavirus fears torpedoed markets last week. Add-on M&A activity declined to 28% from 33%.
LBO financings dominated the smaller pool of loans, with a 63% share, up from 53% in January. The increase follows earlier predictions that sponsors would make their move sooner in 2020 rather than later to avoid potential volatility nearer the election.
Many were hoping this month would yield more M&A, but then last week happened, and visibility on the forward pipeline disintegrated. Even though direct lending — most of which is lower middle market — is largely insulated from wild swings in the broader markets, a 3,000 point bloodbath for the Dow will flash caution in front of any investor. This week’s furious fluctuations and string of unknowns don’t help either. How the unprecedented volatility will affect originations going forward is anyone’s guess.



Latest news

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.

US private debt AUM ($B) by channel
In 2025 and the early part of 2026, the retail channel added AUM to the asset class at a much faster rate than institutional investors in both regions, with growth rates of 43.7% globally, 41.4% in the US, and 73. 1% in Europe through the beginning of 2026 compared with year-end 2024 figures.
