
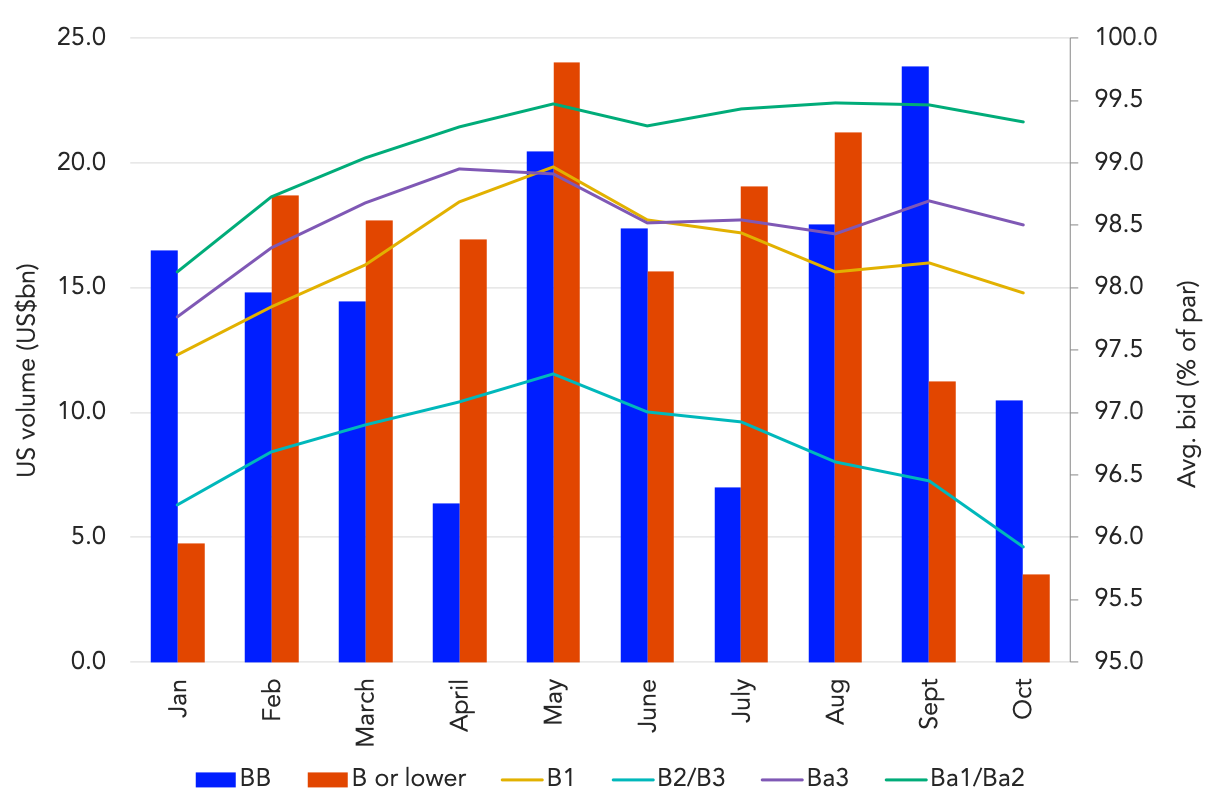
Looking at year-to-date average secondary bids along with loan volume highlights the flight to quality seen in the US loan market over the past few months. Corporates with a rating of single-B or lower peaked in 2019 monthly volume with US$24bn back in May. That same month, the average monthly bid for single-B cohorts also peaked, when B1 rated names averaged near the 99 context and the B2/B3 cohort averaged 97.3. Since then, the B1 and B2/B3 cohorts have sunk considerably, to their October average of 98 and 95.9 areas, respectively. Average bids for double-B names have declined as well, but far less dramatically since their May peak. In the primary market, investors have also been shifting over to higher-quality deals. Double-B rated volume totaled US$24bn in September and US$10.5bn in October. This is far higher than single-B volume which declined to US$11.3bn in September and just US$3.5bn so far in October.
Latest news
Share of PE middle-market deal count by backing type
Add-ons remain the workhorse for middle-market deployment, accounting for 67. 1% of all middle-market transactions YTD, in line with activity seen in recent years.
Software deal share falls in middle markets, rises in large caps
In Q3’26 software’s share of total deals fell in both the Lower Middle Market (to 7%) and Upper Middle Market (to 9%), while Large Cap saw a modest uptick in share to 8%.
Secondary loan prices stabilize following steep declines
Secondary loan prices came under significant pressure through September and October, with the Bloomberg U.S. Leveraged Loan Index declining 119…