


Private debt may be in the process of demonstrating its resilience in the face of the latest challenges.
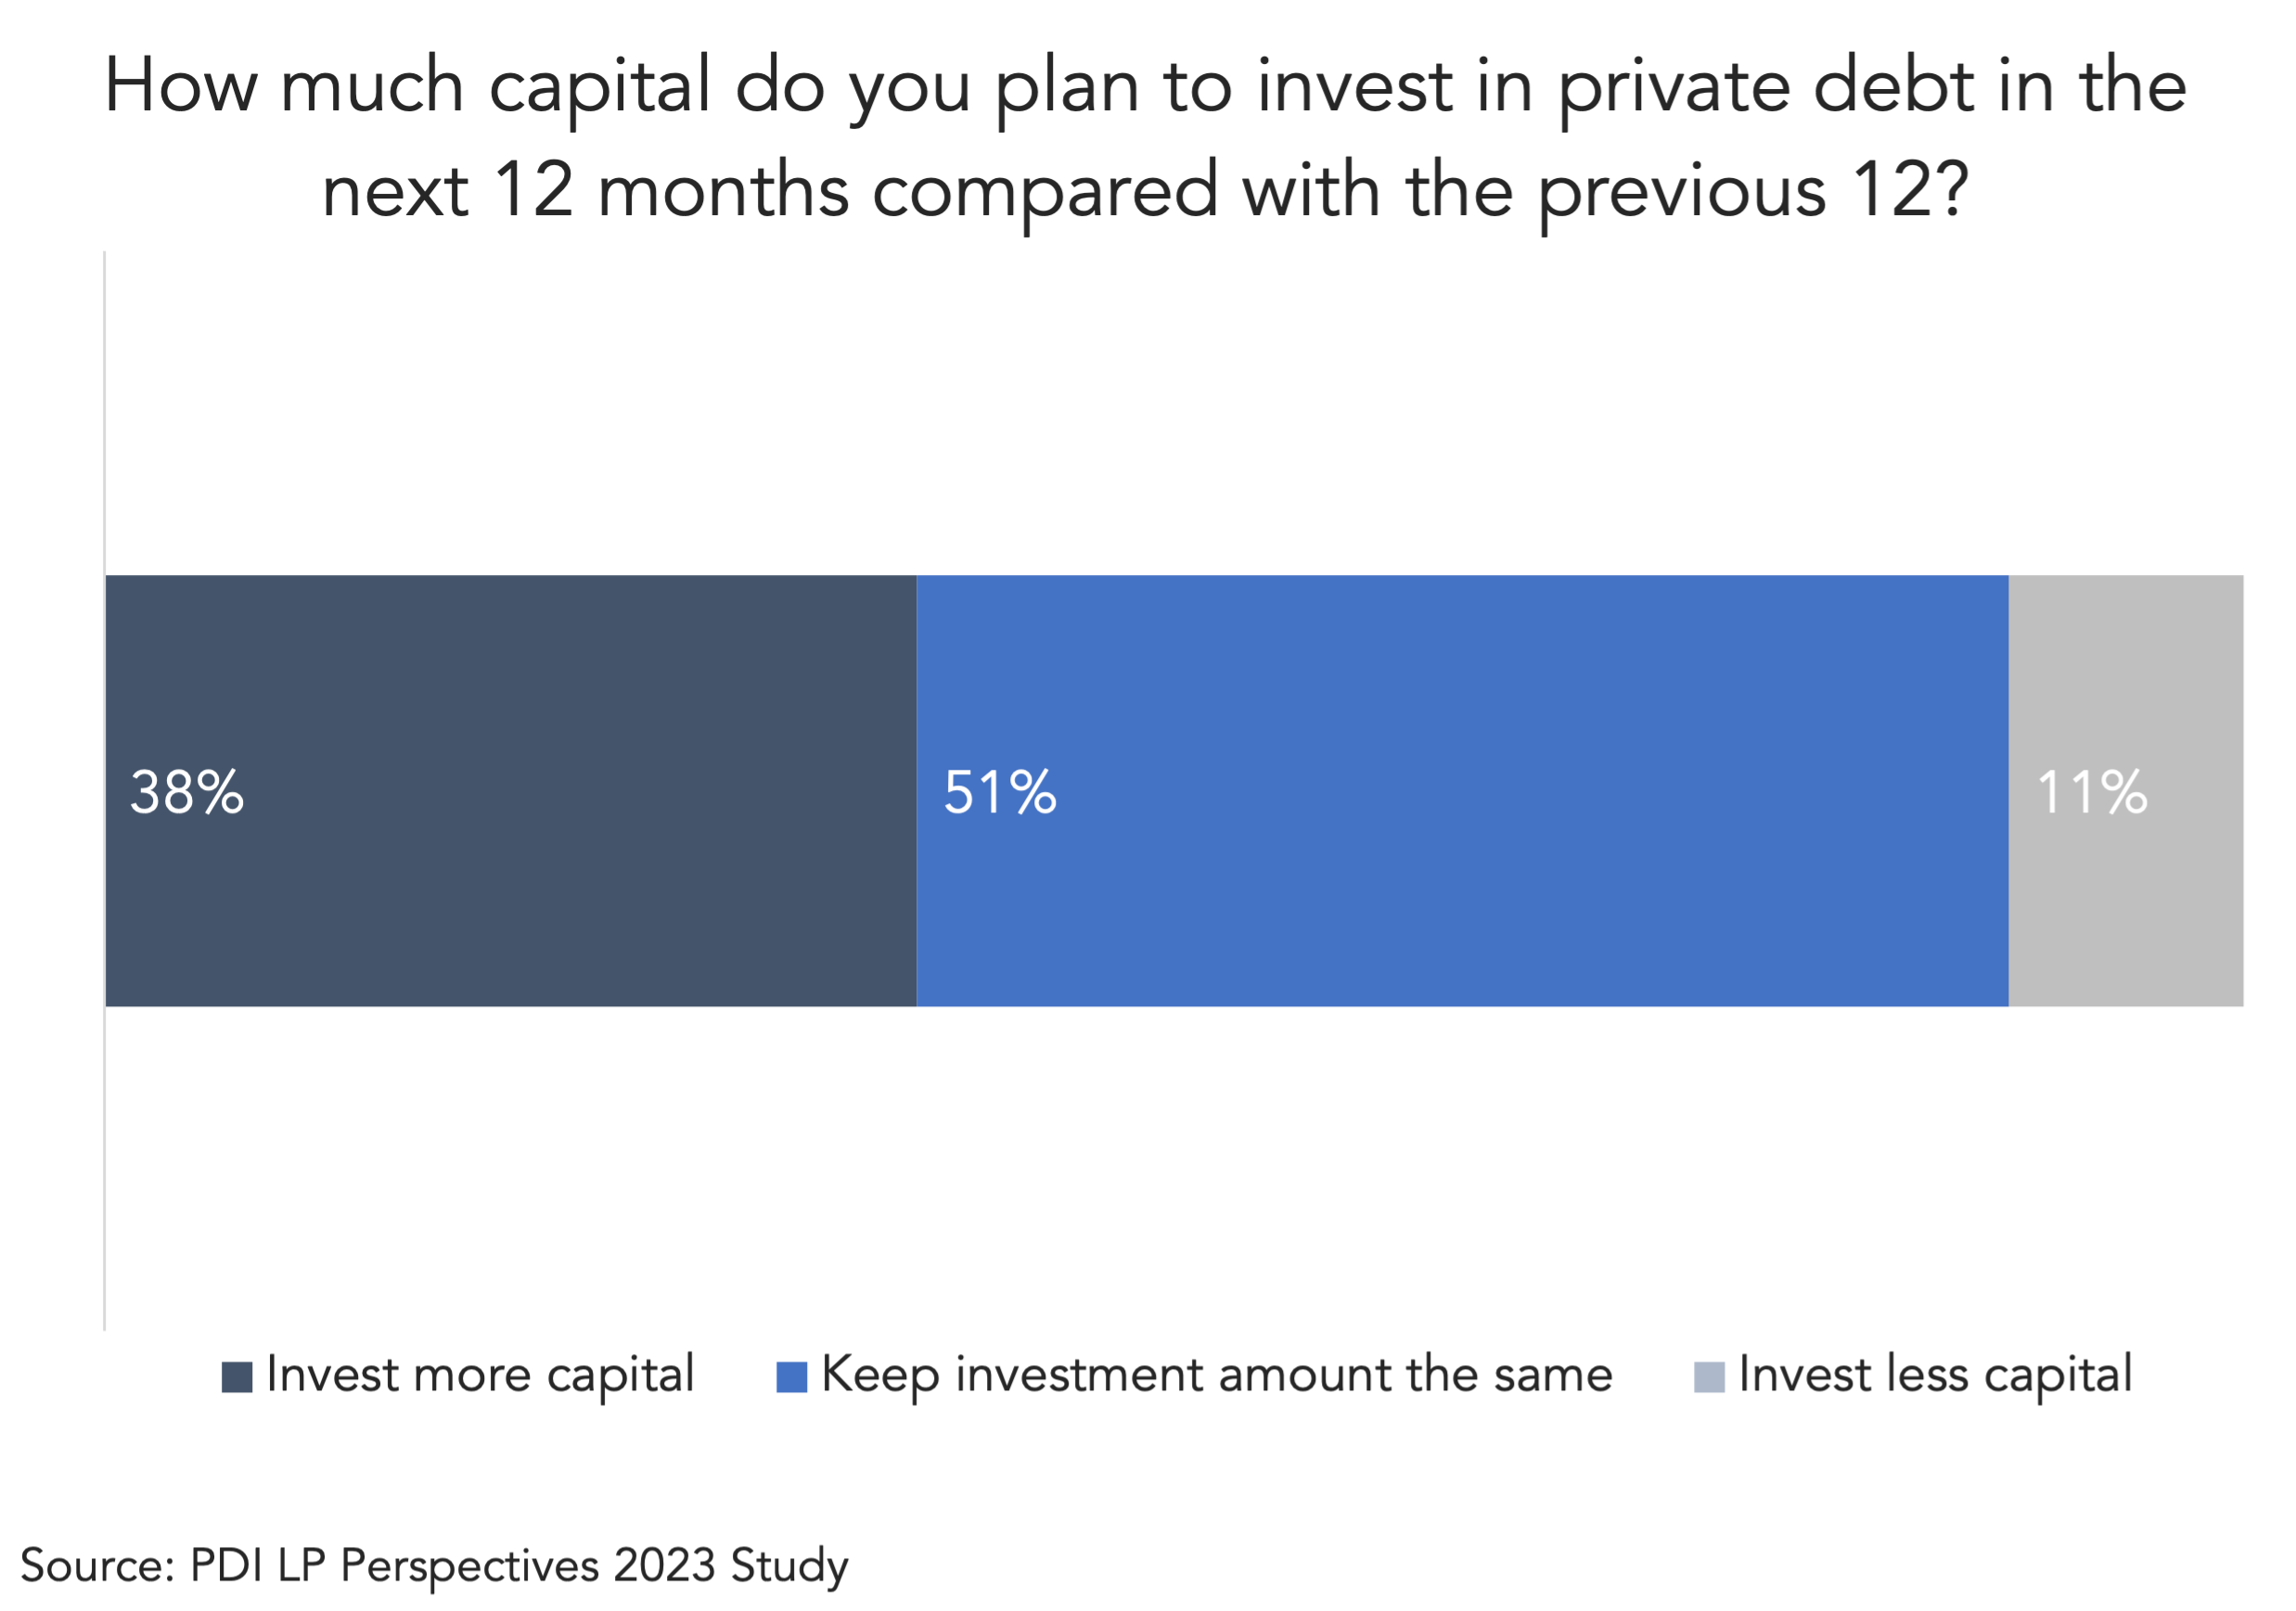
One thing that studies consistently show – including our own Perspectives survey, see chart above – is that investors are still scrambling to access private debt. Tough times we may be living through, but nearly 90 percent of LPs appear keen to either increase their private debt exposure or keep it at the same level.
Perhaps this investor confidence is down to emerging evidence that the asset class can successfully weather the storms. A recent study from Kroll Bond Rating Agency determined that a distressed wave was unlikely to be building since it would by now have already appeared, washing over those companies that had failed to hedge themselves against interest rate rises.
The lack of interest rate hedging is acknowledged to be widespread, likely driven by the complacency that arose from operating in what seemed like a permanent ultra-low interest rate environment. When rates went up, they went up very quickly and caught some companies by surprise.
But the demands of higher interest rates appear not to have taken a particularly heavy toll on borrowers. It’s striking that there are no predictions of default Armageddon. Lincoln International’s Senior Debt Index for the first quarter of this year showed the default rate rising to 4.5 percent from 4.2 percent in the previous quarter. This is certainly above the long-term private debt default rate – which is closer to 2 percent – but well below the 8 percent rate recorded in the aftermath of the economic stasis that followed the initial covid outbreaks.
Given the fact that interest rate pressures have now existed for well over a year – the US Federal Reserve’s first rate hike in more than three years took place in March 2022 – market sources tend to agree with Kroll’s assessment that many of the worst outcomes have probably already been seen.
There is a view that capital has been used more efficiently and innovatively than in previous cycles, for example through increased use of payment in kind rather than cash, while cost-cutting measures of various kinds have been deployed to maintain margins in the face of wage inflation. Managers also appear to have done a good job – on the whole – of identifying sectors more resilient to downturns, even if that’s meant going the extra yard on multiples and leverage.
For private credit as a whole, riding the latest storm would be seen as welcome evidence of its durability by investors who up to now have yet to see how it performs under a sustained period of pressure.
(Past performance is no guarantee of future results.)




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
